













Beni Hydropower Project Ltd – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
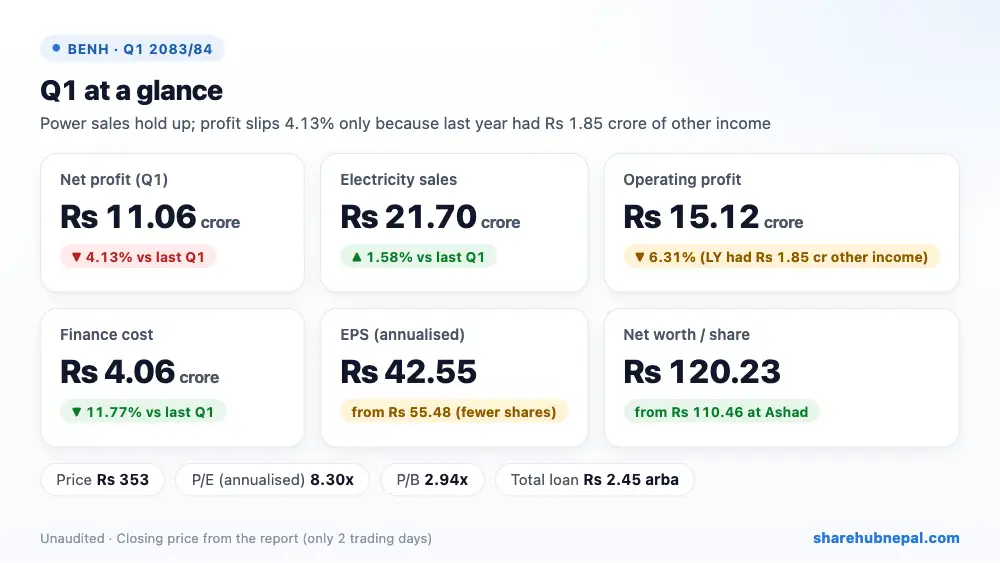
Summary
Beni Hydropower Project, newly listed on NEPSE on 27 Ashwin 2083, earned a net profit of Rs 11.06 crore in the first quarter of FY 2083/84, down 4.13% from Rs 11.54 crore a year ago. Its core business did better: electricity sales rose 1.58% to Rs 21.70 crore (the report credits a 3% higher tariff), cost of sales fell 27.08% and finance cost fell 11.77%. The fall comes only from last year's Rs 1.85 crore of other income, which did not repeat. EPS is Rs 10.64 for the quarter (Rs 42.55 annualised) on a larger share base after the IPO, and net worth per share rose to Rs 120.23.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sales | Rs 216,964,981 | Rs 213,581,317 | +1.58% |
| Cost of sales | Rs 17,274,304 | Rs 23,690,195 | −27.08% |
| Other income | Rs 0 | Rs 18,458,555 | −100.00% |
| Operating profit | Rs 151,239,811 | Rs 161,424,811 | −6.31% |
| Finance cost | Rs 40,615,634 | Rs 46,031,461 | −11.77% |
| Income tax | Rs 0 | Rs 0 | – |
| Net profit | Rs 110,624,177 | Rs 115,393,350 | −4.13% |
| EPS (annualised) | 42.55 | 55.48 | – |
| Net worth per share | 120.23 | 105.14 | – |
1. Where the profit came from
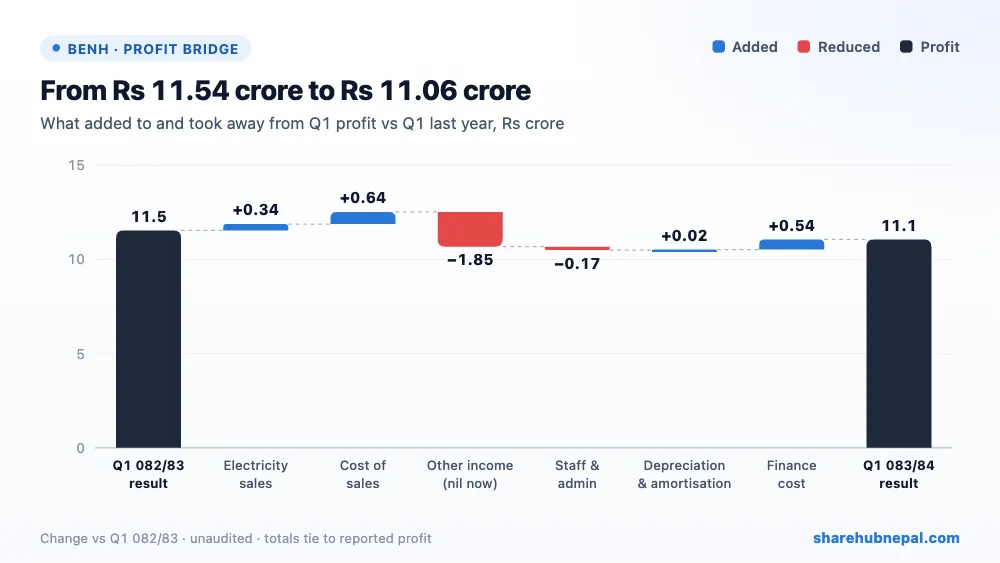
Electricity sales were Rs 21.70 crore against Rs 21.36 crore. Cost of sales fell to Rs 1.73 crore from Rs 2.37 crore, so gross profit rose 5.16% to Rs 19.97 crore. Staff and admin costs rose to Rs 1.15 crore (Rs 97.07 lakh) and depreciation and amortisation stayed at Rs 3.70 crore. There was no other income this time, against Rs 1.85 crore last year, so operating profit fell 6.31% to Rs 15.12 crore. Finance cost fell to Rs 4.06 crore from Rs 4.60 crore. No tax or bonus was charged, so net profit equals profit before tax at Rs 11.06 crore.
2. Profit through the year
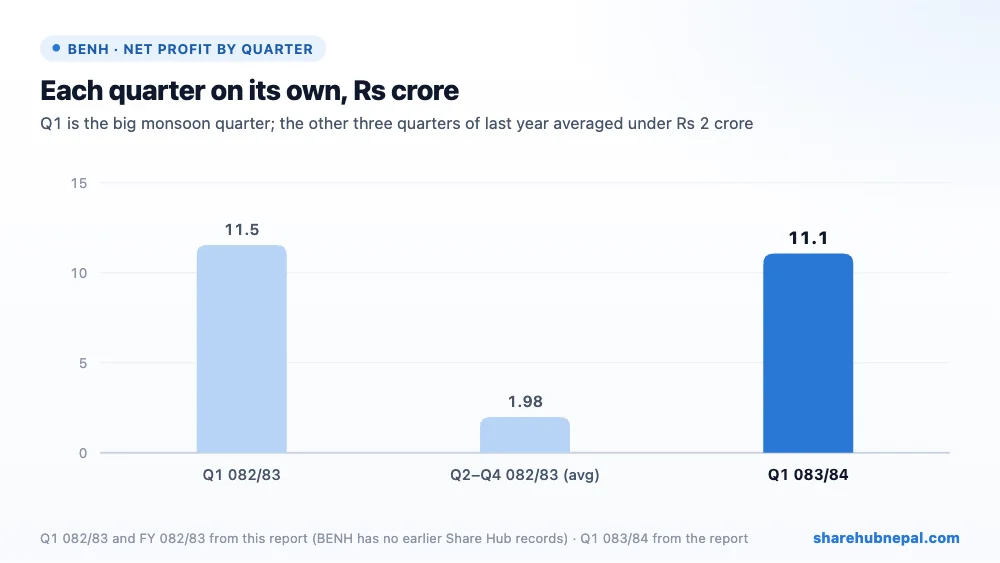
Profit by quarter (from this report and Share Hub records): Q1 082/83: Rs 11.54 crore, Q2–Q4 082/83 (avg): Rs 1.98 crore, Q1 083/84: Rs 11.06 crore. Beni has no earlier records on Share Hub because it was listed only in Ashwin 2083. From this report, FY 2082/83 profit was Rs 17.48 crore, of which Rs 11.54 crore came in Q1 alone, so the other three quarters made only about Rs 1.98 crore each. Expect much lower profit in the dry season; annualised EPS of Rs 42.55 is far above last year's actual EPS of Rs 18.33.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 3,740,758,498 | Rs 3,598,804,800 | +3.94% |
| Total equity | Rs 1,250,374,763 | Rs 1,053,430,587 | +18.70% |
| Long-term borrowing | Rs 2,445,674,910 | Rs 2,404,405,890 | +1.72% |
| Short-term loans | Rs 0 | Rs 129,974,333 | −100.00% |
| Trade and other receivables | Rs 145,857,589 | Rs 76,763,479 | +90.01% |
| Cash and equivalents | Rs 109,805,834 | Rs 14,889,976 | +637.45% |
| Current assets | Rs 299,215,850 | Rs 120,262,574 | +148.80% |
| Current liabilities | Rs 42,125,095 | Rs 138,384,594 | −69.56% |
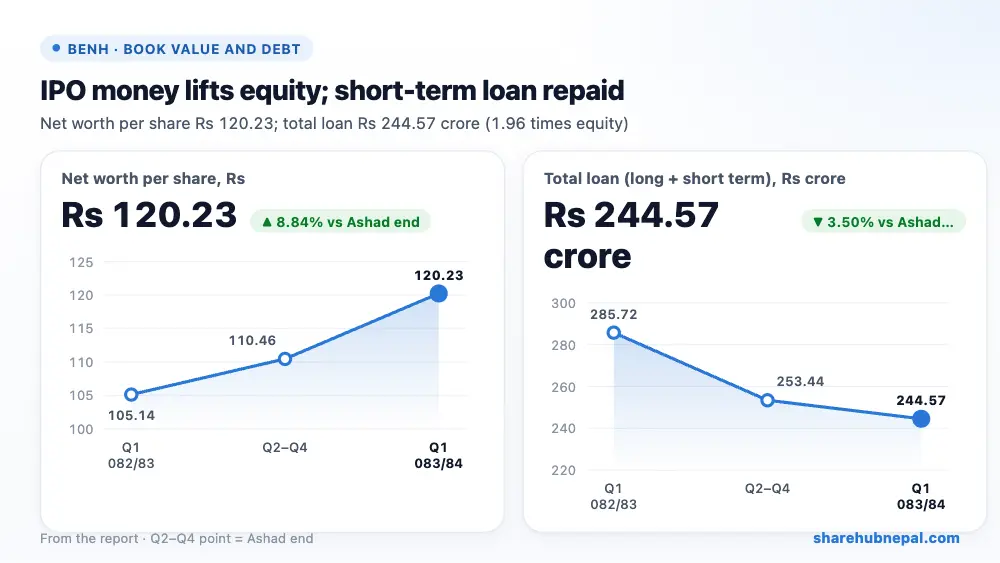
The IPO brought in Rs 8.63 crore of new capital, and the company used its cash to clear the Rs 13.00 crore short-term loan. Long-term borrowing is Rs 2.45 arba, so total debt is 1.96 times equity — still high, but falling (Rs 2.86 arba a year ago). Cash rose to Rs 10.98 crore and receivables (mostly from NEA) to Rs 14.59 crore, while current liabilities fell to Rs 4.21 crore. Equity rose 18.70% to Rs 1.25 arba.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 42.55 |
| Net worth per share | Rs 120.23 |
| Market price (Ashwin end) | Rs 353 |
| P/E (annualised) | 8.30x |
| P/B | 2.94x |
At the Ashwin-end price of Rs 353, the share trades at 8.30 times annualised EPS and 2.94 times net worth per share. The share had traded only two days by Ashwin end (Rs 313.90–353). On last year's actual EPS of Rs 18.33 the P/E is about 19 times, and the report prints 33.19 using the quarter EPS.
Conclusion
Positives: steady power sales with a 3% higher tariff, lower cost of sales and finance cost, the short-term loan fully repaid, cash of Rs 10.98 crore after the IPO, and no legal cases.
Watch: profit is very seasonal (most of last year's profit came in Q1), debt is still 1.96 times equity, last year's Rs 1.85 crore other income is not explained, receivables nearly doubled since Ashad, and the company names weak transmission lines and policy uncertainty as risks.
Watch dry-season profit, how fast long-term debt comes down, and whether NEA payments keep up with sales.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

