













Balephi Hydropower Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
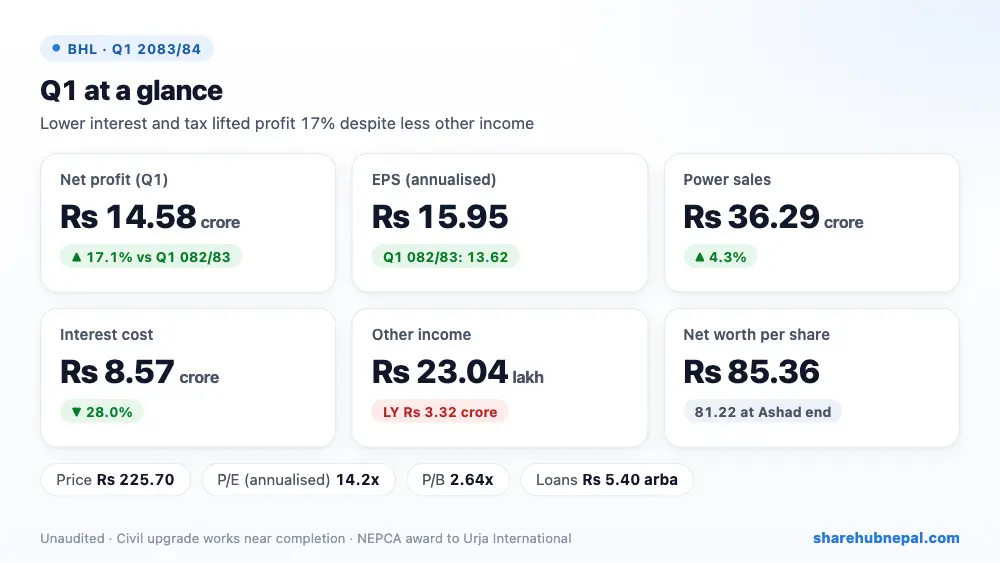
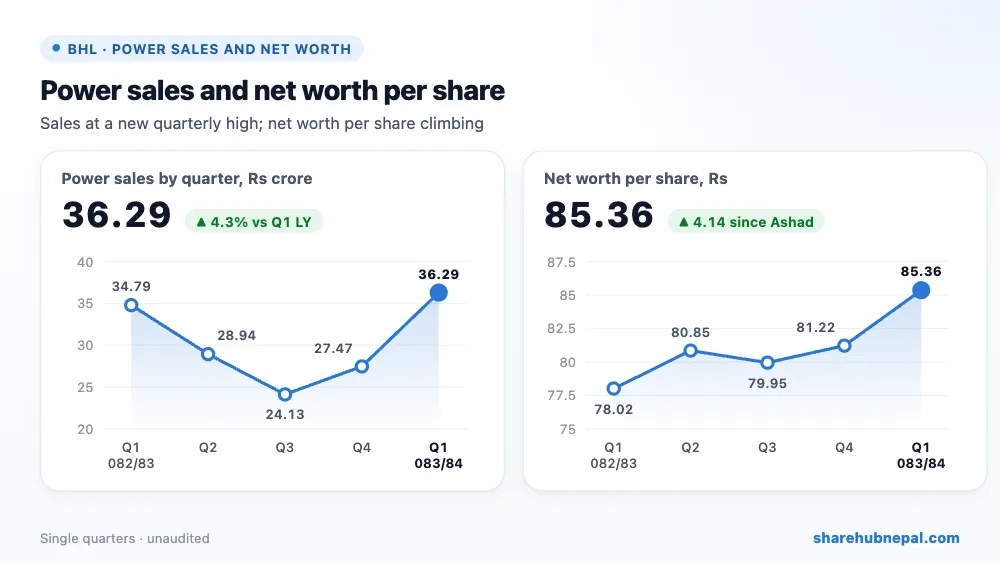
Balephi Hydropower earned a net profit of Rs 14.58 crore in the first quarter of 2083/84, up 17.10% from Rs 12.45 crore a year ago. Annualised EPS is Rs 15.95 and net worth per share rose to Rs 85.36.
Power sales rose 4.33% to Rs 36.29 crore, including Rs 71.24 lakh billed to NEA for energy it could not take (non-dispatch over 72 hours). The main help came from lower interest (Rs 8.57 crore, down 28.04%) and lower tax. Other income fell from Rs 3.32 crore to Rs 23.04 lakh, and depreciation rose. No staff bonus or CSR was provided in Q1.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from power sales | Rs 362,931,614 | Rs 347,858,379 | +4.33% |
| Cost of sales | Rs 19,003,422 | Rs 23,867,288 | −20.38% |
| Other income | Rs 2,303,657 | Rs 33,185,749 | −93.06% |
| Administrative expenses | Rs 13,530,684 | Rs 13,685,358 | −1.13% |
| Profit before interest and depreciation | Rs 332,701,165 | Rs 343,491,483 | −3.14% |
| Finance cost | Rs 85,713,678 | Rs 119,105,825 | −28.04% |
| Depreciation and amortisation | Rs 90,205,171 | Rs 78,533,585 | +14.86% |
| Income taxes | Rs 11,020,880 | Rs 21,376,715 | −48.44% |
| Net profit | Rs 145,761,436 | Rs 124,475,358 | +17.10% |
1. Where the profit came from
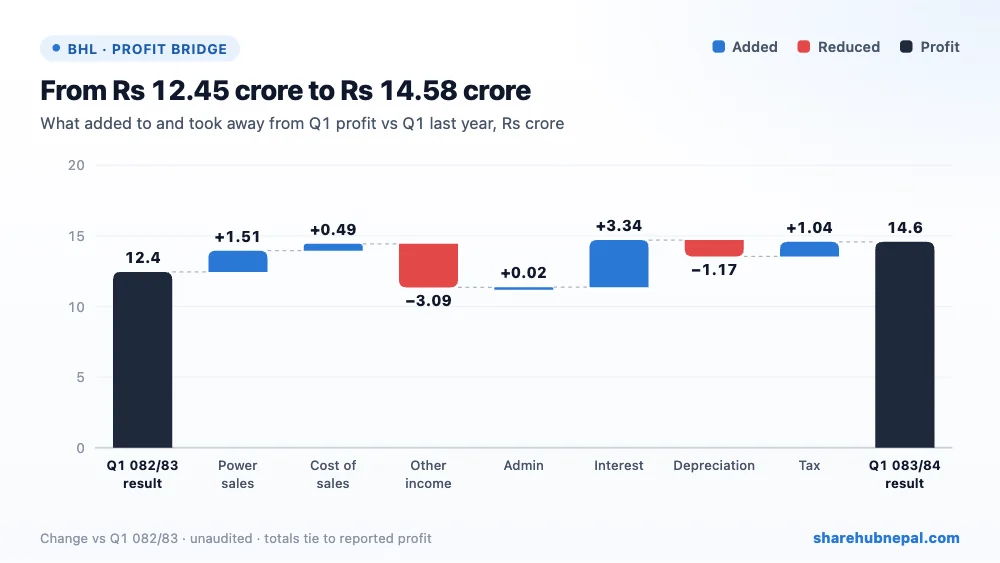
Against Q1 last year, lower interest added Rs 3.34 crore, lower tax Rs 1.04 crore, higher power sales Rs 1.51 crore and lower cost of sales Rs 48.64 lakh. Lower other income took away Rs 3.09 crore and higher depreciation Rs 1.17 crore. Net: profit up Rs 2.13 crore.
2. Profit through the year
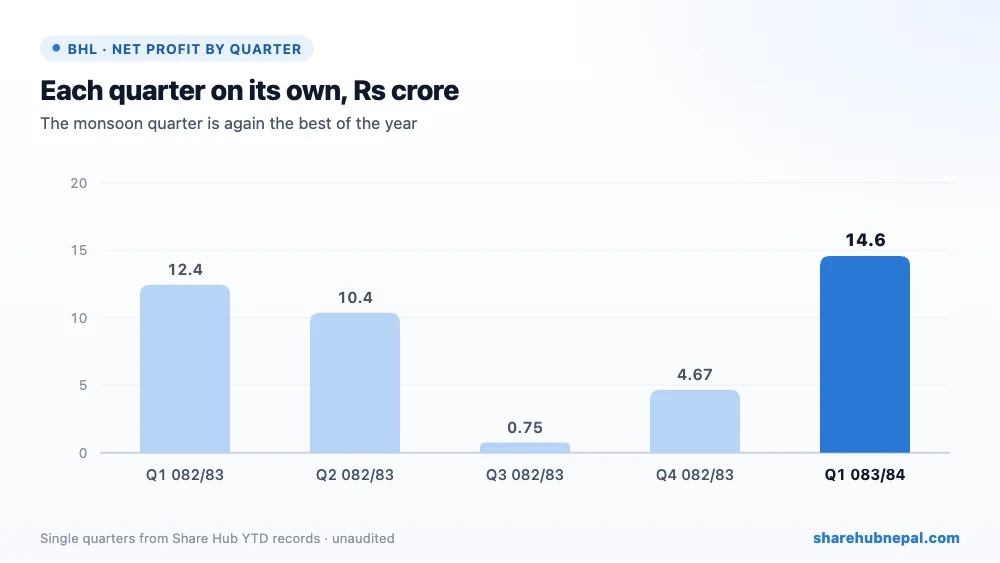
Last year BHL earned Rs 12.45 crore in Q1, Rs 10.37 crore in Q2, only Rs 75.11 lakh in Q3 and Rs 4.67 crore in Q4, for a full-year profit of Rs 28.23 crore (EPS 7.72). Q1 is again the strongest quarter; the annualised EPS of 15.95 will likely fall through the dry season, as it did last year.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Hydropower project (intangible) assets | Rs 7,544,637,913 | Rs 7,600,439,659 | −0.73% |
| Assets under development (upgrade) | Rs 768,900,120 | Rs 741,052,619 | +3.76% |
| Trade receivables | Rs 241,577,620 | Rs 237,435,254 | +1.74% |
| Cash and cash equivalents | Rs 1,678,914 | Rs 727,878 | +130.66% |
| Long-term borrowings | Rs 5,280,000,000 | Rs 5,379,290,000 | −1.85% |
| Short-term borrowings | Rs 120,553,801 | Rs 107,601,763 | +12.04% |
| Total equity | Rs 3,120,722,399 | Rs 2,969,529,191 | +5.09% |
Loans are heavy at Rs 5.40 arba (1.73 times equity), though long-term borrowing fell Rs 9.93 crore this quarter. Cash is very low (Rs 16.79 lakh). Accumulated losses (Rs 53.52 crore) keep net worth per share below Rs 100. Civil upgrade works (Rs 76.89 crore capitalised so far) are nearly complete and should raise generation. An arbitration over the 132 kV transmission line ended with a NEPCA award partly in favour of Urja International on 7 August 2026; the company booked it in its annual accounts.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised, report) | Rs 15.95 |
| EPS (quarter, derived) | Rs 3.99 |
| Net worth per share | Rs 85.36 |
| Total assets per share | Rs 240.51 |
| Market price (Q1 close) | Rs 225.70 |
| P/E (report) | 56.62x |
| P/E (annualised EPS) | 14.15x |
| P/B | 2.64x |
| Debt to equity | 1.73x |
The Q1 closing price was Rs 225.70 (range Rs 195 to Rs 229.80). On the annualised EPS the P/E is 14.2 times (the report's 56.62 uses the quarter EPS), and the price is 2.64 times net worth per share.
Conclusion
Positives: higher sales, interest down 28%, falling long-term loans, a near-complete upgrade that should lift generation, and the arbitration now closed.
Watch: heavy loans, very low cash, NEA non-dispatch and forced outages, flood and sediment damage, year-end bonus and CSR not yet booked, and an unexplained Rs 54 lakh difference between profit and the rise in equity.
BHL had a good monsoon quarter, helped mainly by lower interest. The completed upgrade and continued loan repayment are the keys to better results through the year.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

