













Bottlers Nepal (Terai) Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082).
Summary
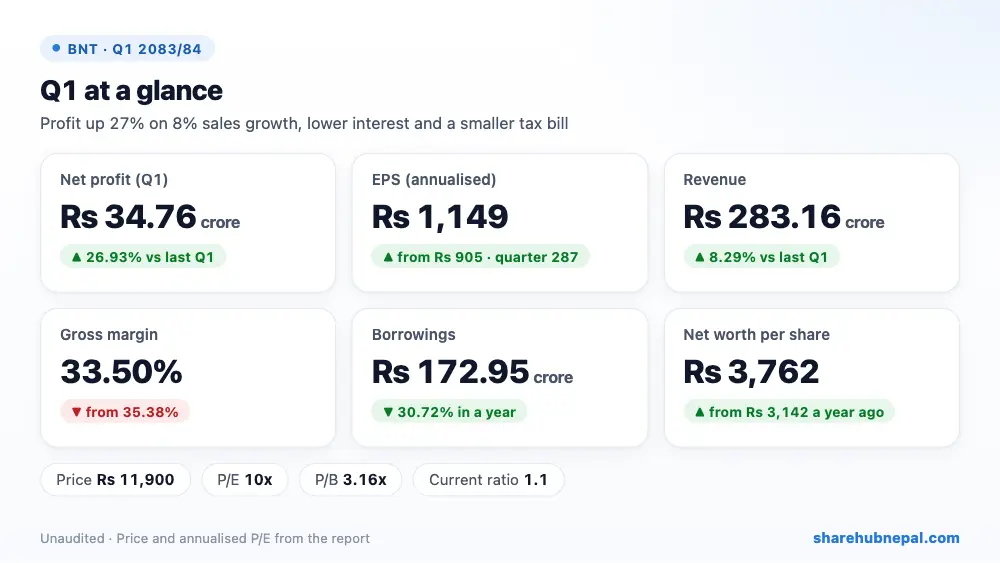
Bottlers Nepal (Terai), which bottles Coca-Cola products at Bharatpur, earned a net profit of Rs 34.76 crore in the first quarter, up 26.93% from Rs 27.39 crore a year ago. Quarter EPS is Rs 287 (Rs 1,149 annualised).
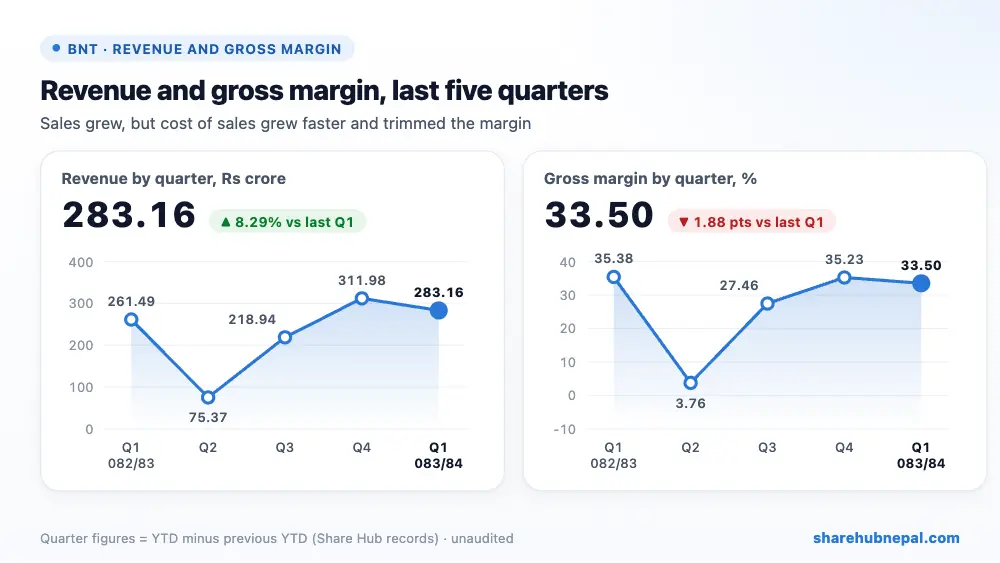
Revenue rose 8.29% to Rs 283.16 crore. Cost of sales rose faster (11.43%), so the gross margin fell to 33.50% from 35.38%; the company names higher excise duty, a weaker rupee, the Middle East crisis and input costs, and says the August floods and the later festival dates hurt demand. Profit still grew strongly because selling costs fell 3.92%, finance costs fell 38.81% and the net tax charge was Rs 1.69 crore lower. The net profit margin rose to 12.28% from 10.47%.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from operations | Rs 2,831,572,000 | Rs 2,614,892,000 | +8.29% |
| Gross profit | Rs 948,627,000 | Rs 925,137,000 | +2.54% |
| Selling and distribution expenses | Rs 420,817,000 | Rs 437,964,000 | −3.92% |
| Administrative and operating expenses | Rs 118,271,000 | Rs 118,144,000 | +0.11% |
| Profit from operations | Rs 420,496,000 | Rs 376,916,000 | +11.56% |
| Finance costs | Rs 20,950,000 | Rs 34,239,000 | −38.81% |
| Income tax (net) | Rs 51,955,000 | Rs 68,824,000 | −24.51% |
| Net profit | Rs 347,591,000 | Rs 273,853,000 | +26.93% |
| EPS (annualised) | 1,149 | 905 | – |
1. Where the profit came from
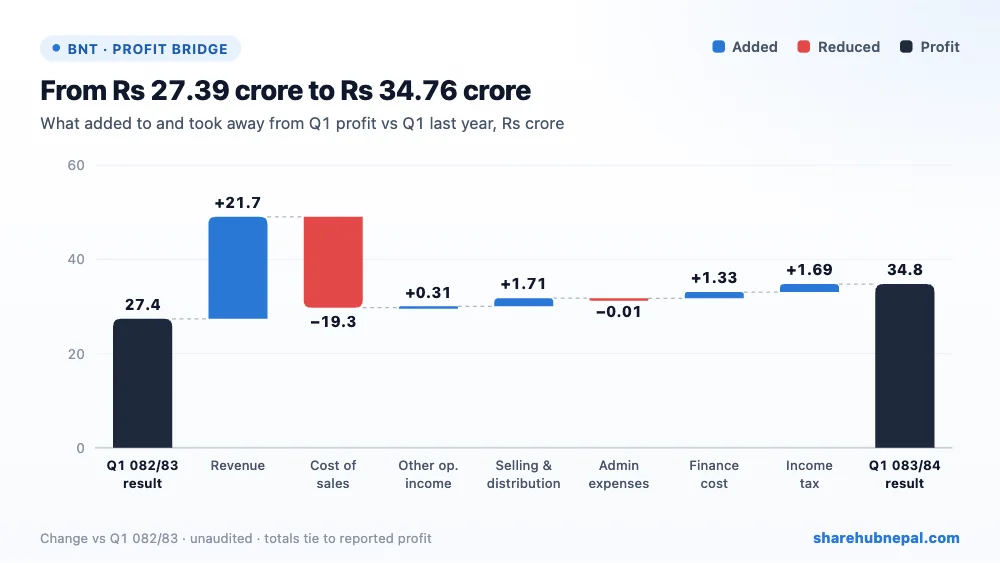
Compared with last year's Q1, higher revenue added Rs 21.67 crore but higher cost of sales took away Rs 19.32 crore. Lower selling and distribution expenses added Rs 1.71 crore, a lower tax charge Rs 1.69 crore, lower finance cost Rs 1.33 crore and other operating income Rs 30.68 lakh. Administrative expenses were almost unchanged.
2. Profit through the year
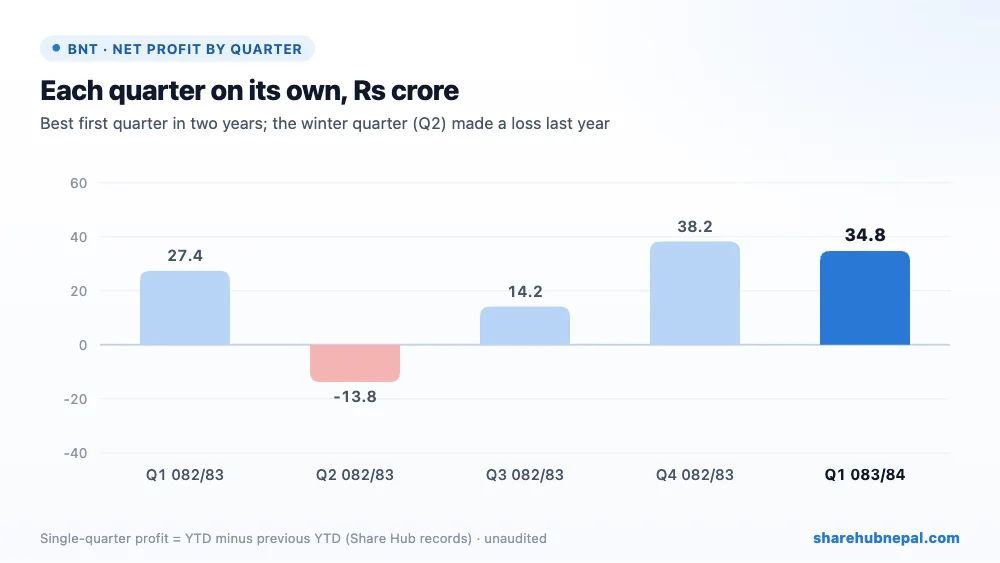
Based on Share Hub's records, single-quarter profit in 2082/83 was Rs 27.39 crore in Q1, a loss of Rs 13.84 crore in Q2 (winter), then Rs 14.16 crore in Q3 and Rs 38.22 crore in Q4 (full year Rs 65.93 crore, EPS 544.86). Q1 and Q4 carry the year.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashwin 2082 | Change |
| Borrowings | Rs 1,729,487,000 | Rs 2,496,200,000 | −30.72% |
| Inventories | Rs 2,094,907,000 | Rs 1,799,879,000 | +16.39% |
| Trade receivables | Rs 1,367,466,000 | Rs 1,020,490,000 | +34.00% |
| Advances | Rs 423,132,000 | Rs 930,933,000 | −54.55% |
| Cash and cash equivalents | Rs 315,031,000 | Rs 773,750,000 | −59.29% |
| Total assets | Rs 9,304,095,000 | Rs 9,532,726,000 | −2.40% |
| Total equity | Rs 4,552,300,000 | Rs 3,801,645,000 | +19.75% |
The report compares the balance sheet with a year ago (Ashwin 2082). Borrowings fell 30.72% to Rs 172.95 crore, while advances fell 54.55% to Rs 42.31 crore and cash fell to Rs 31.50 crore from Rs 77.38 crore. Inventories rose 16.39% to Rs 209.49 crore and trade receivables 34.00% to Rs 136.75 crore. Equity rose 19.75% to Rs 455.23 crore and net worth per share to Rs 3,762. BNT bought concentrate worth Rs 65.81 crore from Pacific Refreshments in the quarter.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (quarter, YTD) | Rs 287 |
| EPS (annualised) | Rs 1,149 |
| Net worth per share | Rs 3,762 |
| Market price (report) | Rs 11,900 |
| P/E (annualised, report) | 10x |
| P/B | 3.16x |
| ROE (annualised) | 31% |
| Current ratio | 1.1 |
At Rs 11,900 the share trades at 10 times annualised EPS (as reported) and 3.16 times net worth per share. On last year's full-year EPS of Rs 544.86 the P/E is about 21.8, a more realistic measure given the seasonal winter loss.
Conclusion
Positives: profit up 26.93%, revenue up 8.29%, finance cost down 38.81%, borrowings down 30.72% in a year, a higher net margin (12.28%) and strong annualised ROE (31%).
Watch: a lower gross margin as costs rise faster than prices, receivables up 34%, rising inventories, lower cash, excise and currency pressure, and the seasonal Q2 loss pattern.
BNT had a strong first quarter despite cost pressure. Like BNL, it expects some festival demand to show up in Q2; protecting the gross margin is the main task for the rest of the year.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

