













Chandragiri Hills Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
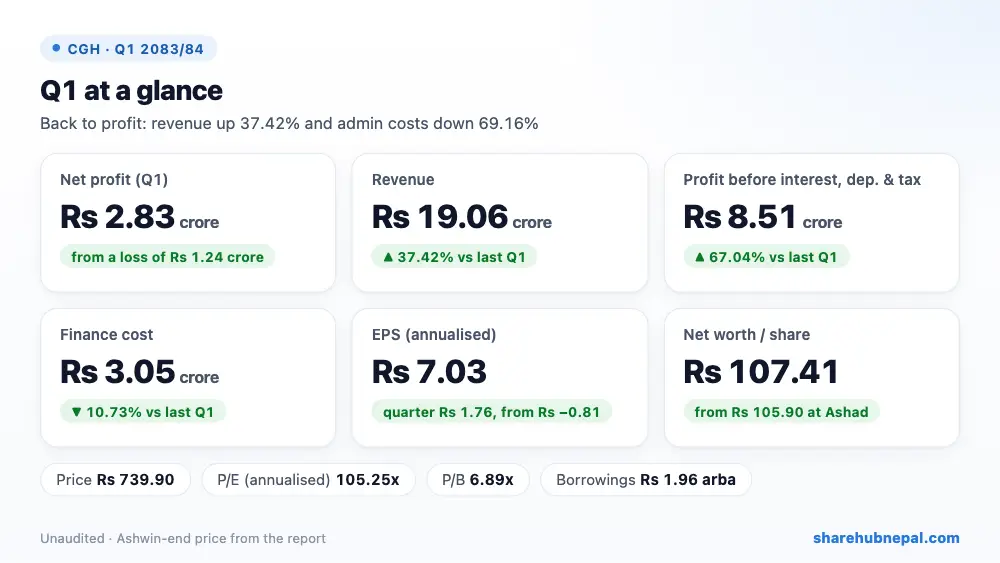
Chandragiri Hills earned a net profit of Rs 2.83 crore in the first quarter of FY 2083/84, against a loss of Rs 1.24 crore a year ago. Revenue from its cable car and resort rose 37.42% to Rs 19.06 crore, and administrative and other expenses fell 69.16% to Rs 1.03 crore. Cost of sales more than doubled (up 110.95%) and staff costs rose 21.36%, but profit before interest, depreciation and tax still rose 67.04% to Rs 8.51 crore. The company says visitors fell for about one and a half months after the 10 Bhadra 2083 Bhotekoshi flood blocked roads. Quarter EPS is Rs 1.76 (Rs 7.03 annualised) and net worth per share Rs 107.41.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from operation | Rs 190,609,600 | Rs 138,707,763 | +37.42% |
| Cost of sales | Rs 48,256,044 | Rs 22,875,257 | +110.95% |
| Gross income | Rs 142,353,555 | Rs 115,832,506 | +22.90% |
| Other income | Rs 3,740,370 | Rs 10,288,867 | −63.65% |
| Employee benefit expenses | Rs 50,717,481 | Rs 41,791,932 | +21.36% |
| Administrative and other expenses | Rs 10,299,554 | Rs 33,396,166 | −69.16% |
| Profit before interest, depreciation and tax | Rs 85,076,889 | Rs 50,933,275 | +67.04% |
| Finance cost | Rs 30,460,434 | Rs 34,122,520 | −10.73% |
| Depreciation and amortisation | Rs 26,304,626 | Rs 29,242,483 | −10.05% |
| Net profit | Rs 28,311,830 | −Rs 12,431,728 | Turned to profit |
| EPS (quarter) | 1.76 | -0.81 | – |
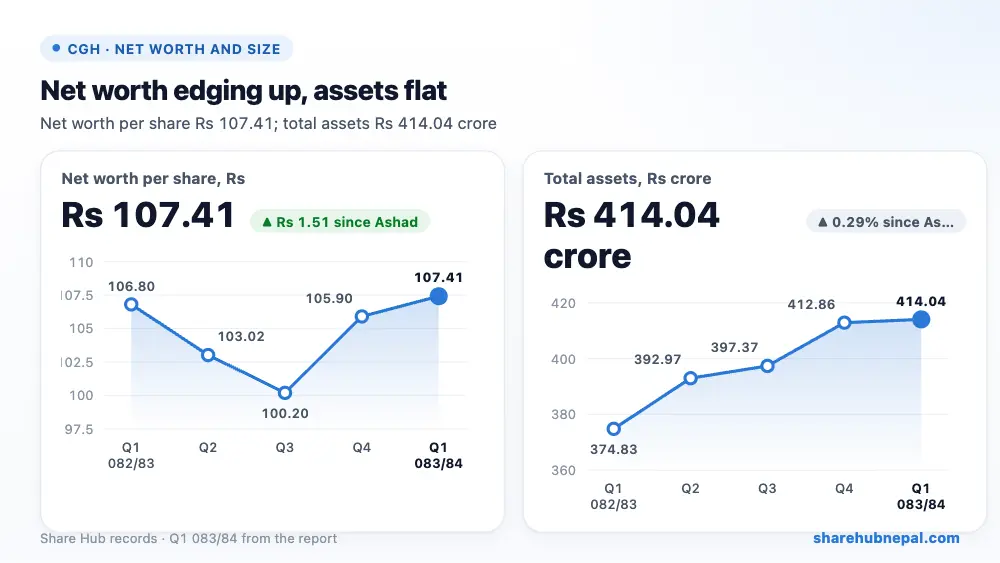
| Net worth per share | 107.41 | 106.8 | – |
1. Where the profit came from
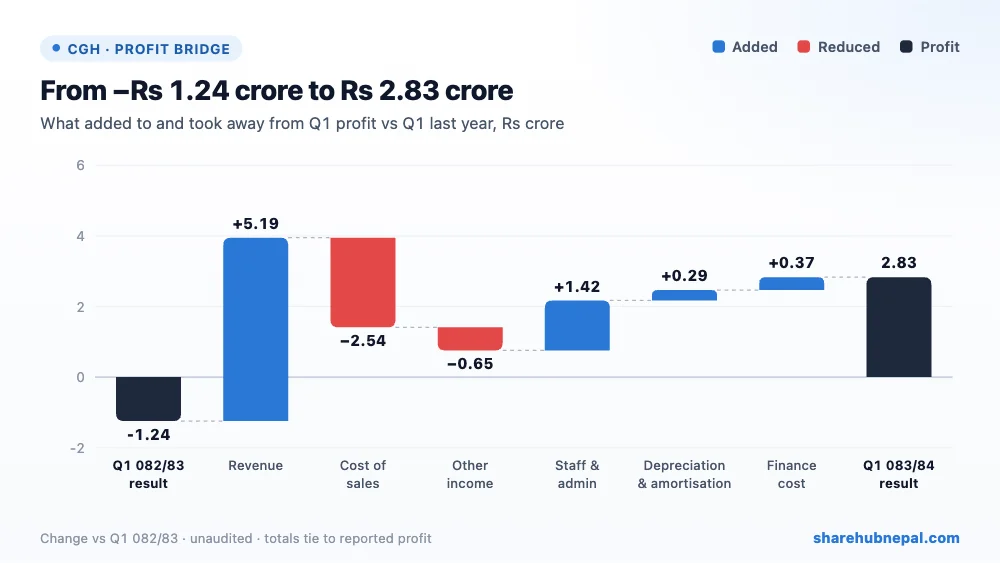
Higher revenue added Rs 5.19 crore and lower administrative and other expenses saved Rs 2.31 crore (staff costs rose Rs 89.26 lakh, so staff and admin together saved Rs 1.42 crore). Cost of sales took Rs 2.54 crore more and other income was Rs 65.48 lakh lower. Finance cost (−Rs 36.62 lakh) and depreciation (−Rs 29.38 lakh) both fell. No tax was charged.
2. Profit through the year
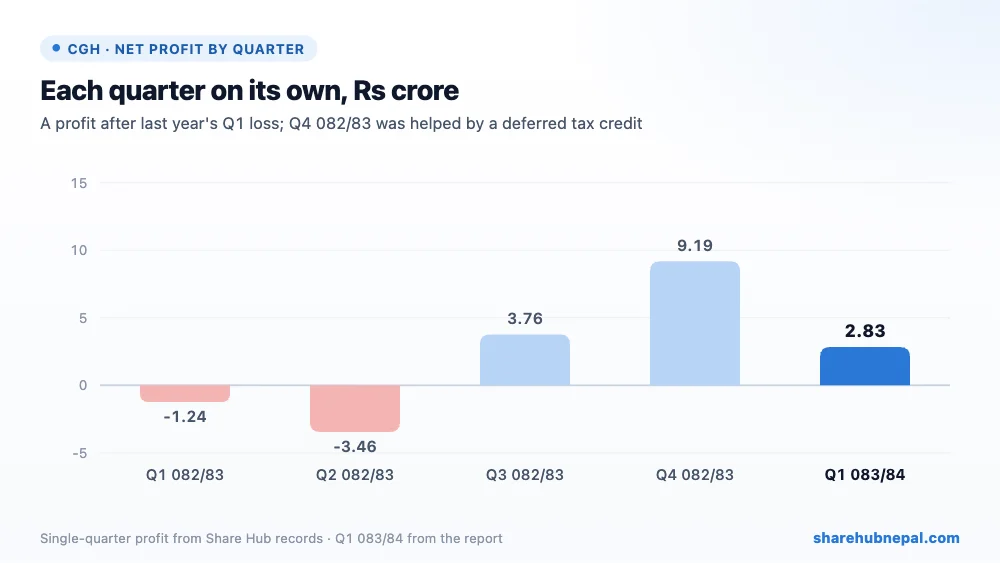
Profit by quarter (Share Hub records): Q1 082/83: −Rs 1.24 crore, Q2 082/83: −Rs 3.46 crore, Q3 082/83: Rs 3.76 crore, Q4 082/83: Rs 9.19 crore, Q1 083/84: Rs 2.83 crore. Share Hub quarter figures are worked out from year-to-date records. FY 2082/83 profit was Rs 8.25 crore (EPS Rs 5.12), and it included a deferred tax income of Rs 5.16 crore; profit before tax was Rs 13.41 crore. Last year's first half was hit by the Gen Z protests; the company says that damage has now been repaired.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 4,140,439,171 | Rs 4,128,613,363 | +0.29% |
| Property, plant and equipment | Rs 3,019,055,780 | Rs 3,045,131,030 | −0.86% |
| Capital work in progress | Rs 267,975,677 | Rs 208,568,297 | +28.48% |
| Borrowings (long-term) | Rs 1,960,766,226 | Rs 1,961,660,751 | −0.05% |
| Total equity | Rs 1,730,190,592 | Rs 1,705,833,878 | +1.43% |
| Cash and equivalents | Rs 202,471,116 | Rs 240,908,963 | −15.96% |
Total assets are Rs 4.14 arba, mostly the cable car and resort (property and equipment Rs 3.02 arba) plus Rs 26.80 crore of capital work in progress, which rose Rs 5.94 crore in the quarter. Borrowings are Rs 1.96 arba, about the same as at Ashad end, and the debt-to-equity ratio is 1.13. Equity rose to Rs 1.73 arba (Rs 107.41 per share), about Rs 39.55 lakh less than the quarter's profit. Cash fell to Rs 20.25 crore from Rs 24.09 crore; the current ratio is 3.34.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 7.03 |
| Net worth per share | Rs 107.41 |
| Market price (Ashwin end) | Rs 739.9 |
| P/E (annualised) | 105.25x |
| P/B | 6.89x |
At the Ashwin-end price of Rs 739.9, the share trades at 105.25 times annualised EPS and 6.89 times net worth per share. The report's own P/E of 420.96 uses the quarter EPS. Either way the share is priced far above what the company earns now and about 6.9 times its net worth.
Conclusion
Positives: back to profit, revenue up 37.42%, profit before interest, depreciation and tax up 67.04%, admin costs down 69.16%, finance cost down 10.73%, current ratio 3.34.
Watch: cost of sales more than doubled (gross margin 74.68% vs 83.51%), Rs 1.96 arba of debt, tourism hit by the Bhadra flood, global conflict and natural disasters (named by the company), cash down, very high P/E and P/B.
A good recovery quarter for visitor numbers and profit; the coming tourist seasons and control of direct costs will show if the improvement lasts.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

