













Chilime Hydropower Company Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
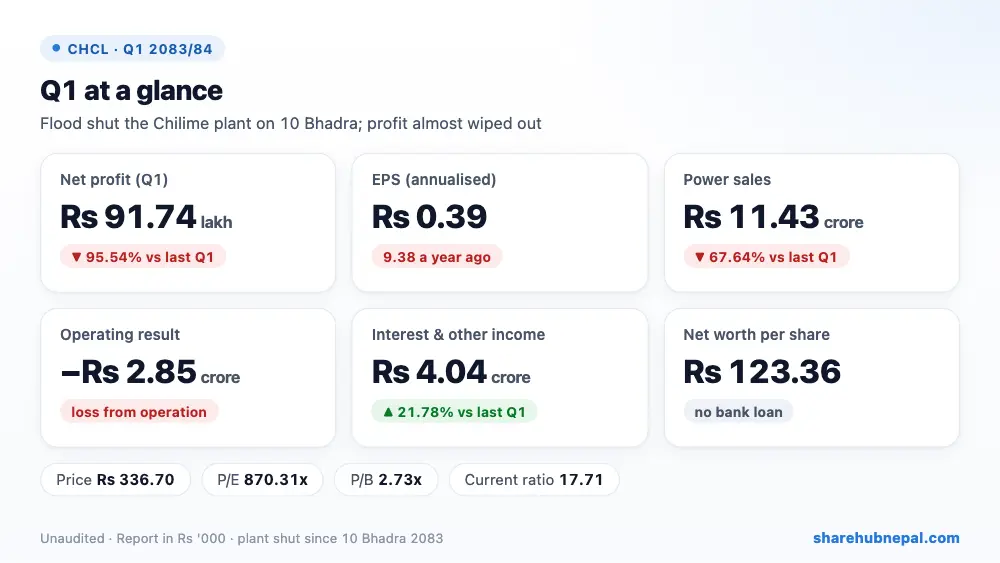
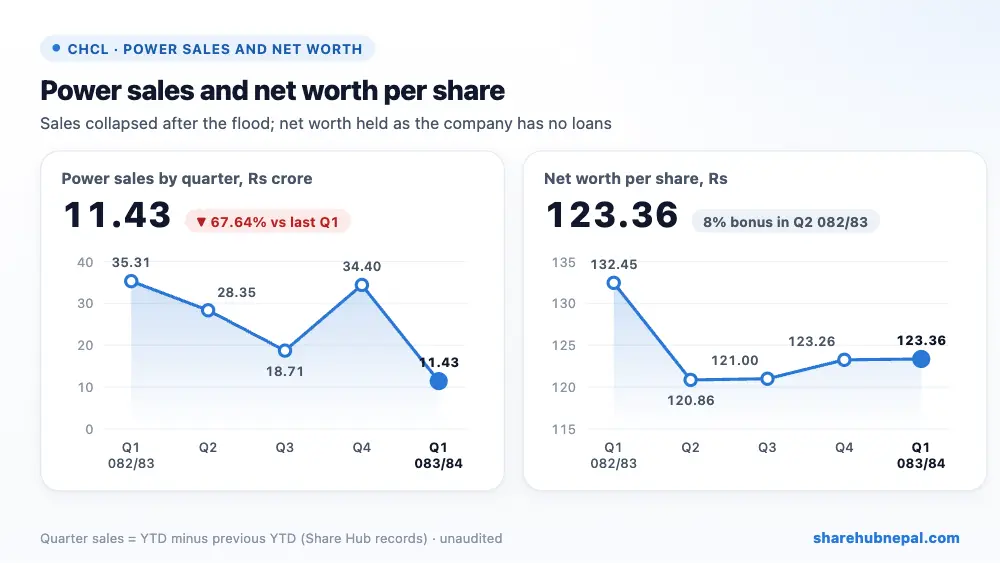
Chilime Hydropower earned a net profit of only Rs 91.74 lakh in the first quarter, down 95.54% from Rs 20.58 crore a year ago. Annualised EPS fell to Rs 0.39 from Rs 9.38. The reason is the sudden flood on the Bhotekoshi river on 10 Bhadra 2083: water and debris entered the Chilime powerhouse, six staff lost their lives, and power generation has been fully shut since then.
Power sales fell 67.64% to Rs 11.43 crore, which is mostly what the plant sold before the flood. Staff and administrative costs jumped 158.58% to Rs 5.41 crore, partly because of rescue and search work and higher staff insurance and salary. The company made a loss of Rs 2.85 crore from operations; the small profit came from Rs 3.19 crore of interest income (mostly on short-term loans to its subsidiaries) and Rs 84.29 lakh of other income such as Chilime Tower rent.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Income from power sales | Rs 114,272,260 | Rs 353,082,700 | −67.64% |
| Direct expenses | Rs 34,050,990 | Rs 26,593,440 | +28.04% |
| Royalty | Rs 33,527,230 | Rs 57,408,270 | −41.60% |
| Employee and administrative expenses | Rs 54,053,240 | Rs 20,903,620 | +158.58% |
| Depreciation | Rs 21,181,200 | Rs 14,000,000 | +51.29% |
| Profit (loss) from operation | −Rs 28,540,400 | Rs 234,177,370 | Turned to loss |
| Finance and other income | Rs 40,359,790 | Rs 33,141,640 | +21.78% |
| Tax | Rs 2,316,600 | Rs 54,051,610 | −95.71% |
| Net profit | Rs 9,173,740 | Rs 205,841,810 | −95.54% |
| EPS (annualised) | 0.39 | 9.38 | – |
1. Where the profit came from
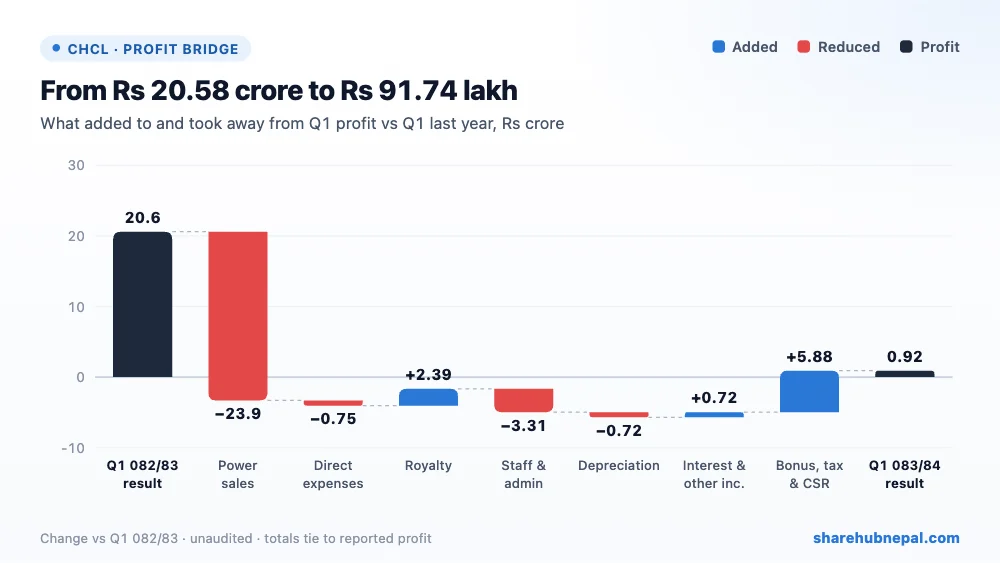
Compared with last year's Q1, lower power sales took away Rs 23.88 crore, higher staff and admin costs Rs 3.31 crore, higher direct expenses Rs 74.58 lakh and higher depreciation Rs 71.81 lakh. Lower bonus, tax and CSR (because profit was small) gave back Rs 5.88 crore, lower royalty Rs 2.39 crore and higher interest and other income Rs 72.18 lakh.
2. Profit through the year
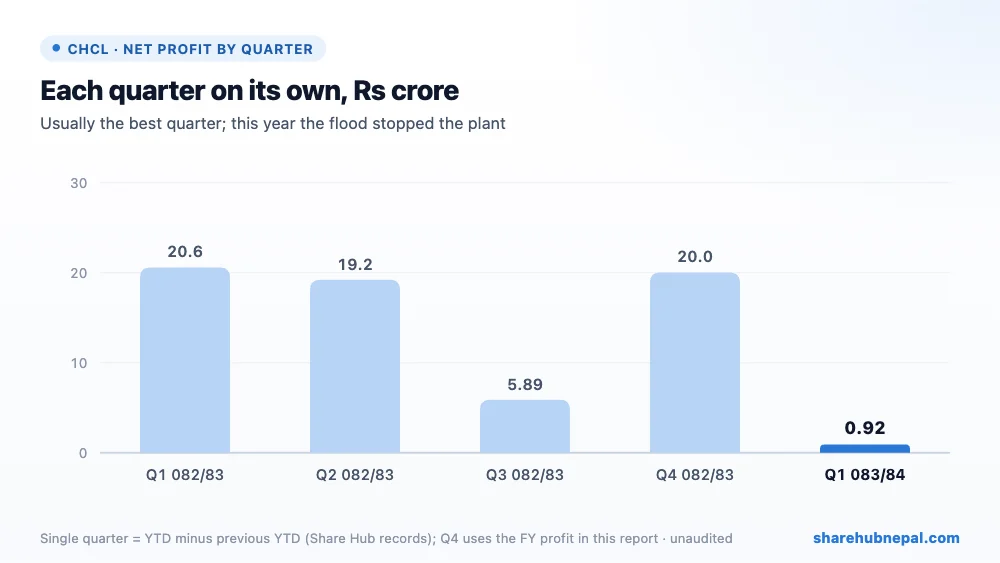
Based on Share Hub's records, single-quarter profit in 2082/83 was Rs 20.58 crore in Q1, Rs 19.22 crore in Q2, Rs 5.89 crore in Q3 and about Rs 20.03 crore in Q4 (using the FY profit of Rs 65.73 crore printed in this report; Share Hub's Q4 record shows Rs 72.01 crore). Q1 is normally one of the best quarters. With the plant still shut, the company itself expects core operating revenue to stay close to zero in the current and coming quarters.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Property, plant and equipment (net) | Rs 2,096,938,420 | Rs 2,118,119,610 | −1.00% |
| Investment in subsidiary and associates | Rs 6,595,375,900 | Rs 6,594,625,900 | +0.01% |
| Cash and cash equivalents | Rs 285,133,460 | Rs 149,042,650 | +91.31% |
| Current assets | Rs 3,217,035,920 | Rs 3,189,426,290 | +0.87% |
| Current liabilities | Rs 181,643,340 | Rs 175,021,420 | +3.78% |
| Total equity | Rs 11,700,680,390 | Rs 11,691,506,660 | +0.08% |
Chilime has no bank loan. Equity is Rs 11.70 arba, and Rs 6.60 arba of its assets are investments in its subsidiary and associate hydropower companies. Current assets of Rs 3.22 arba (including short-term loans to subsidiaries, Rs 21.72 crore of term deposits and Rs 28.51 crore of cash) are 17.71 times current liabilities. The plant's book value (Rs 2.10 arba) has not yet been reduced for the flood damage; the insurance claim and the damage assessment are still in progress.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 0.39 |
| Net worth per share | Rs 123.36 |
| Total assets per share | Rs 129.08 |
| Market price (Q1 last trade) | Rs 336.70 |
| P/E (report) | 870.31x |
| P/B | 2.73x |
| Current ratio | 17.71 |
The last trade in the quarter was Rs 336.70. On annualised EPS of Rs 0.39 the P/E is 870, which has little meaning while the plant is shut. The price is 2.73 times net worth per share, so investors are pricing the strong balance sheet, the associate companies and an eventual restart, not current earnings.
Conclusion
Positives: no bank loan, strong liquidity (current ratio 17.71), large investments in other hydropower companies, steady interest and rent income, and an insurance claim in process.
Watch: how long the plant stays shut (riverbed rise at the tailrace and a new access tunnel are needed), the size of the damage write-off and the insurance payout, near-zero core revenue in the next quarters, higher costs, and the gap between this report's FY 2082/83 profit (Rs 65.73 crore) and Share Hub's Q4 record (Rs 72.01 crore).
This quarter shows the full effect of the Bhadra flood: Chilime's own plant is earning almost nothing for now. Its debt-free balance sheet and investments give it a cushion, but earnings depend on how quickly the powerhouse can be restored and how much the insurance pays.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

