













Chhyangdi Hydropower Ltd – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
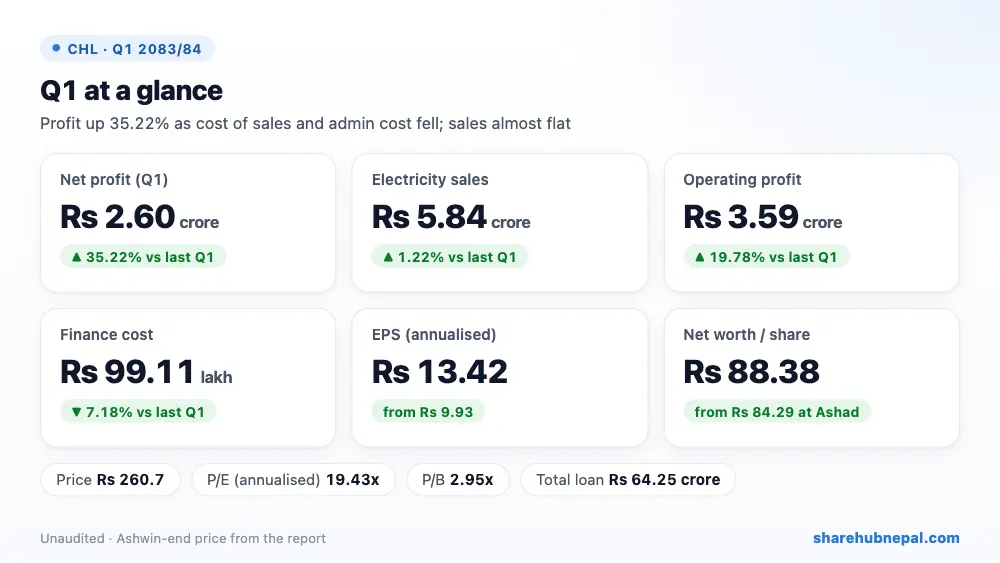
Chhyangdi Hydropower earned a net profit of Rs 2.60 crore in the first quarter of FY 2083/84, up 35.22% from Rs 1.92 crore a year ago. Electricity sales rose only 1.22% to Rs 5.84 crore, but cost of sales fell 17.56% and administrative expenses fell 52.34%, so operating profit rose 19.78% to Rs 3.59 crore. Finance cost fell 7.18% to Rs 99.11 lakh as the loan is repaid. The company says the monsoon came on time, generation was as expected and finance cost is coming down. Quarter EPS is Rs 3.36 (Rs 13.42 annualised) and net worth per share is Rs 88.38.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sales | Rs 58,407,175 | Rs 57,700,824 | +1.22% |
| Cost of sales | Rs 6,969,778 | Rs 8,454,302 | −17.56% |
| Other income | Rs 0 | Rs 0 | – |
| Operating profit | Rs 35,868,201 | Rs 29,944,610 | +19.78% |
| Finance cost | Rs 9,911,395 | Rs 10,678,091 | −7.18% |
| Income tax | −Rs 14,346 | Rs 59,484 | Turned to loss |
| Net profit | Rs 25,971,151 | Rs 19,207,035 | +35.22% |
| EPS (annualised) | 13.42 | 9.93 | – |
| Net worth per share | 88.38 | 85.16 | – |
1. Where the profit came from
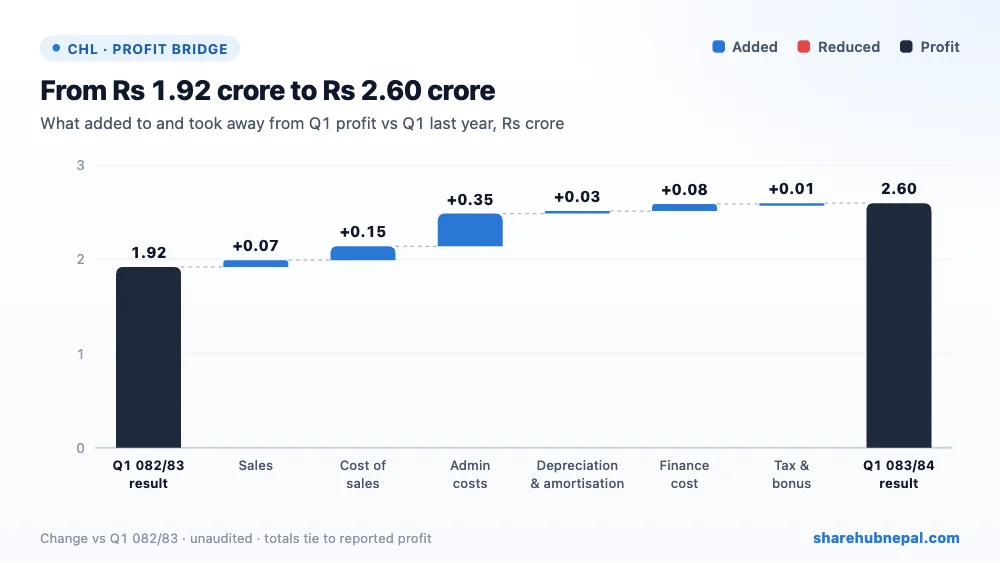
Sales added Rs 7.06 lakh and cost of sales fell by Rs 14.85 lakh, so gross profit rose 4.45% to Rs 5.14 crore and the gross margin improved to 88.07% from 85.35%. Administrative expenses fell by Rs 34.78 lakh to Rs 31.67 lakh (the report does not explain why), and depreciation was almost flat at Rs 1.24 crore. Finance cost fell by Rs 7.67 lakh. There was no other income and no current tax; a small deferred tax credit of Rs 14,346 was booked (a Rs 59,484 charge a year ago). Together these lifted net profit by Rs 67.64 lakh.
2. Profit through the year
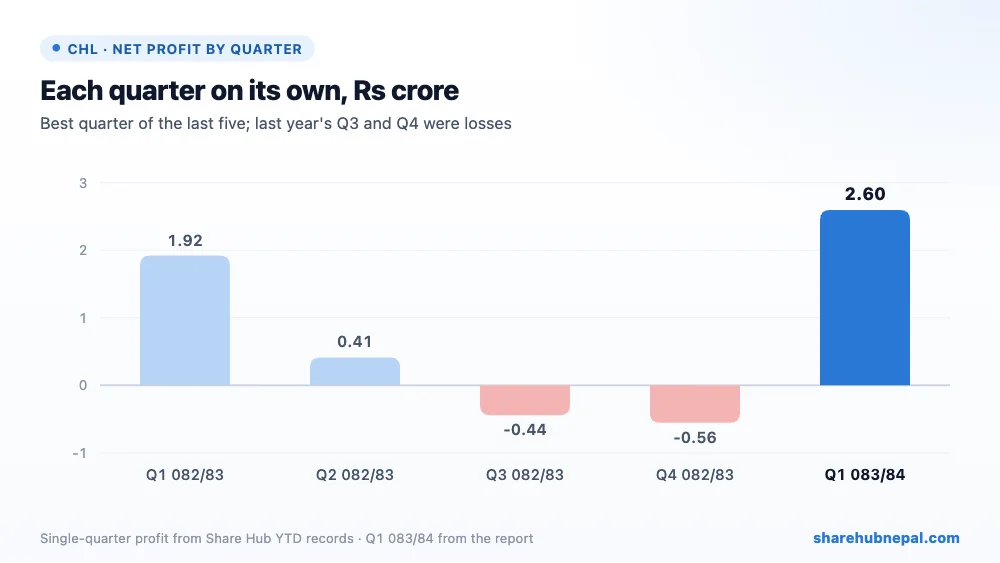
Profit by quarter (Share Hub records): Q1 082/83: Rs 1.92 crore, Q2 082/83: Rs 41.17 lakh, Q3 082/83: −Rs 44.38 lakh, Q4 082/83: −Rs 55.68 lakh, Q1 083/84: Rs 2.60 crore. Last year Q1 and Q2 were profitable, but Q3 and Q4 made losses of Rs 44.38 lakh and Rs 55.68 lakh, so FY 2082/83 ended with only Rs 1.33 crore profit (EPS Rs 1.72). This Q1 is again the monsoon peak, and the dry-season quarters may again be weak.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 1,341,510,686 | Rs 1,323,949,365 | +1.33% |
| Total equity | Rs 684,015,992 | Rs 652,388,273 | +4.85% |
| Long-term borrowings | Rs 616,560,713 | Rs 627,689,953 | −1.77% |
| Current borrowings | Rs 25,958,243 | Rs 25,958,243 | +0.00% |
| Cash and equivalents | Rs 47,876,097 | Rs 30,206,982 | +58.49% |
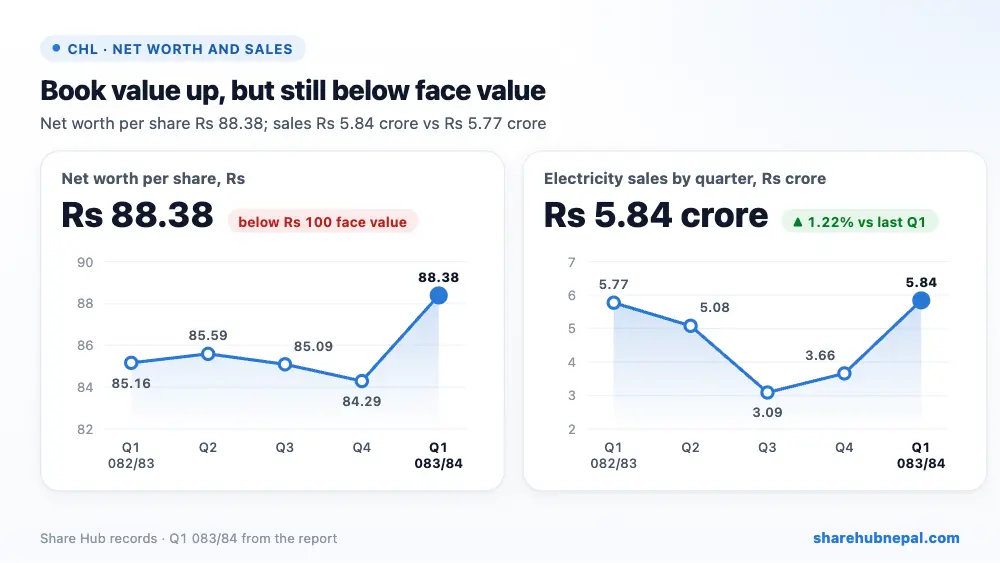
Total loans fell to Rs 64.25 crore (long-term Rs 61.66 crore and short-term Rs 2.60 crore) from Rs 65.36 crore at Ashad end and Rs 68.36 crore a year ago, and are now 0.94 times equity. Cash rose to Rs 4.79 crore and trade receivables to Rs 3.85 crore, so current assets are 2.95 times current liabilities. Equity rose by Rs 3.16 crore to Rs 68.40 crore, Rs 56.57 lakh more than the Q1 profit; the report does not explain the difference. Retained earnings are still negative (Rs −16.29 crore), so net worth per share (Rs 88.38) is below the Rs 100 face value.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 13.42 |
| Net worth per share | Rs 88.38 |
| Market price (Ashwin end) | Rs 260.7 |
| P/E (annualised) | 19.43x |
| P/B | 2.95x |
At the Ashwin-end price of Rs 260.7, the share trades at 19.43 times annualised EPS and 2.95 times net worth per share. The report's P/E of 77.69 uses the quarter EPS. Q1 is the strongest season: FY 2082/83 EPS was only Rs 1.72, a P/E of about 151.57 at today's price, so on full-year earnings the share looks expensive.
Conclusion
Positives: profit up 35.22%, gross margin 88.07%, admin cost cut by more than half, loans and interest cost falling, strong liquidity (current ratio 2.95), and no legal cases.
Watch: sales are almost flat, last year's dry-season quarters made losses, net worth per share is still below Rs 100, equity rose Rs 56.57 lakh more than profit without explanation, and the company warns of flood and landslide risk and that a cut in the government's customs exemption on machinery may raise operating cost.
Watch whether Chhyangdi can avoid losses in the dry-season quarters this year, whether admin cost stays low, and whether the loan keeps falling.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

