













Daramkhola Hydro Energy Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with Q4 2082/83 (no Q1 2082/83 figures are available) and with Ashad end 2083.
Summary
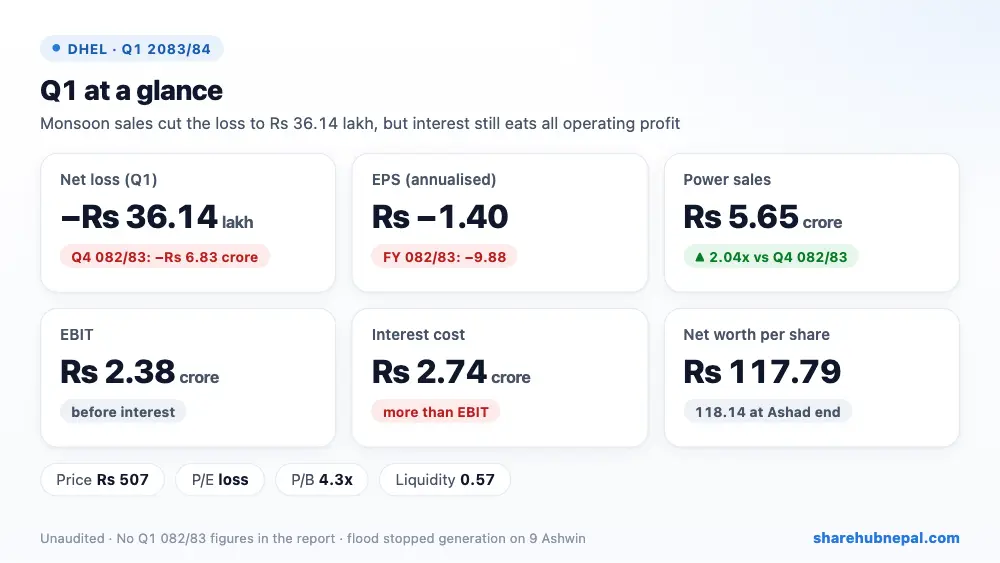
Daramkhola Hydro Energy made a net loss of Rs 36.14 lakh in the first quarter of 2083/84 (quarter EPS −0.35, annualised −1.40). The report does not show last year's first quarter, and Share Hub has no Q1 2082/83 record for DHEL, so this analysis compares Q1 with Q4 2082/83 (a loss of Rs 6.83 crore) and with the full year 2082/83 (a loss of Rs 10.18 crore).
The monsoon helped: electricity sales were Rs 5.65 crore, double Q4 and almost half of the whole of last year's Rs 11.40 crore. Cost of sales was only Rs 27.02 lakh. After Rs 39.89 lakh of staff and admin cost and Rs 2.60 crore of depreciation, the plant earned Rs 2.38 crore before interest, but interest on loans was Rs 2.74 crore, so the quarter still ended in a small loss. The company also reports that the flood of 9 Ashwin 2083 damaged the transmission line from the switchyard to Harichaur substation and regular generation has stopped; repair is in its final stage.
| Indicator | Q1 2083/84 | Q4 2082/83 (quarter) | Change |
| Revenue from sale of energy | Rs 56,484,406 | Rs 27,704,710 | +103.88% |
| Cost of sales | Rs 2,702,447 | Rs 42,797,045 | −93.69% |
| Employee and administrative expenses | Rs 3,989,424 | Rs 2,866,177 | +39.19% |
| Depreciation and amortisation | Rs 26,020,874 | Rs 18,644,310 | +39.56% |
| Earning before interest and tax | Rs 23,771,660 | −Rs 36,602,822 | Turned to profit |
| Financial expenses (interest) | Rs 27,385,165 | Rs 31,729,475 | −13.69% |
| Net profit (loss) | −Rs 3,613,504 | −Rs 68,332,297 | Loss narrowed 94.71% |
1. Where the profit came from
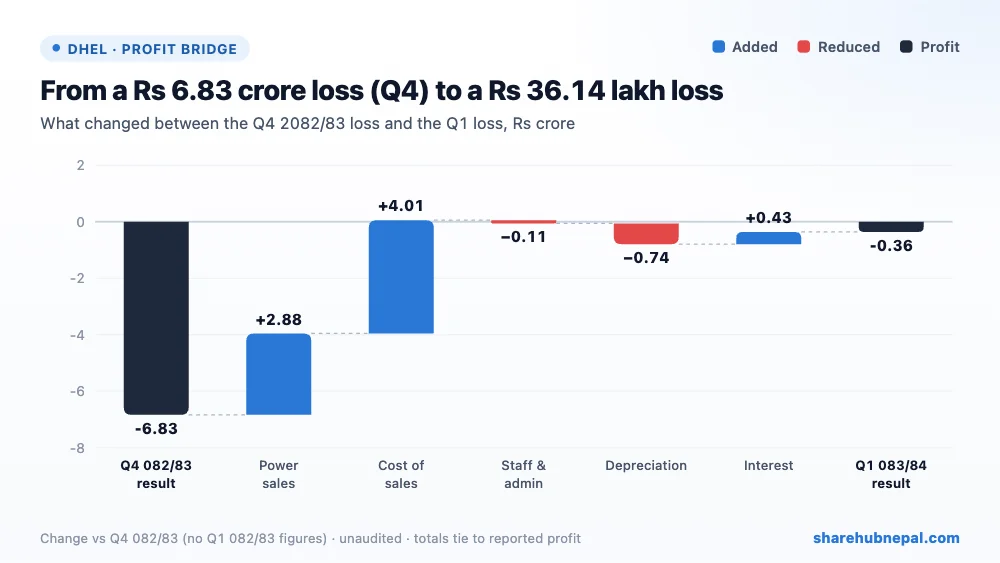
Compared with Q4 2082/83, higher power sales added Rs 2.88 crore and much lower cost of sales added Rs 4.01 crore (Q4 carried large year-end costs). Lower interest added Rs 43.44 lakh. Higher depreciation took away Rs 73.77 lakh and higher staff and admin cost Rs 11.23 lakh. Together these cut the loss by Rs 6.47 crore.
2. Profit through the year
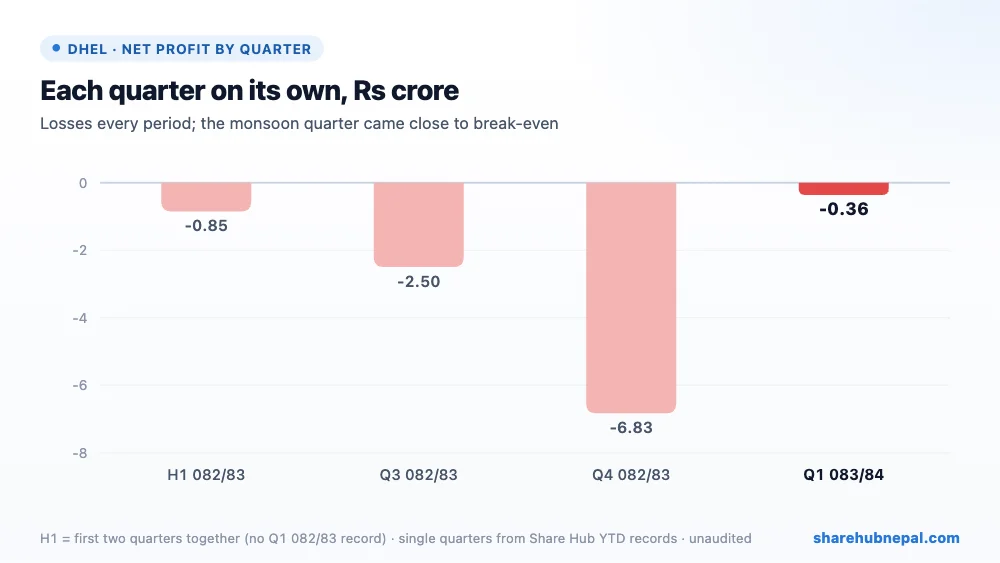
DHEL has made a loss in every period on Share Hub's records: Rs 85.08 lakh in the first half of 2082/83, Rs 2.50 crore in Q3, Rs 6.83 crore in Q4, and now Rs 36.14 lakh. The first quarter is the high-water season, so it should be the best quarter of the year; if even this quarter cannot cover interest, the dry-season quarters are likely to show bigger losses, especially with generation stopped by the flood damage.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Property, plant and project assets (net) | Rs 2,738,965,719 | Rs 2,777,207,084 | −1.38% |
| Trade and other receivables | Rs 44,128,119 | Rs 21,386,711 | +106.33% |
| Cash and cash equivalents | Rs 3,913,377 | Rs 9,508,958 | −58.85% |
| Long-term borrowings | Rs 1,427,269,441 | Rs 1,427,519,441 | −0.02% |
| Current liabilities (incl. Rs 16 crore short-term loan) | Rs 226,625,061 | Rs 240,306,629 | −5.69% |
| Total equity | Rs 1,213,799,715 | Rs 1,217,413,219 | −0.30% |
Loans are heavy for a small plant: Rs 1.43 arba long-term plus Rs 16 crore short-term, about 1.31 times equity of Rs 1.21 arba. Cash fell to just Rs 39.13 lakh, current liabilities (Rs 22.66 crore) are bigger than current assets (Rs 12.87 crore), and the liquidity ratio is 0.57. Receivables doubled to Rs 4.41 crore as NEA had not yet paid for the monsoon sales. Project (intangible) assets fell Rs 3.85 crore in Q1, about Rs 1.24 crore more than the amortisation charged — the report does not explain the gap.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (quarter, report) | Rs −0.35 |
| EPS (annualised) | Rs −1.40 |
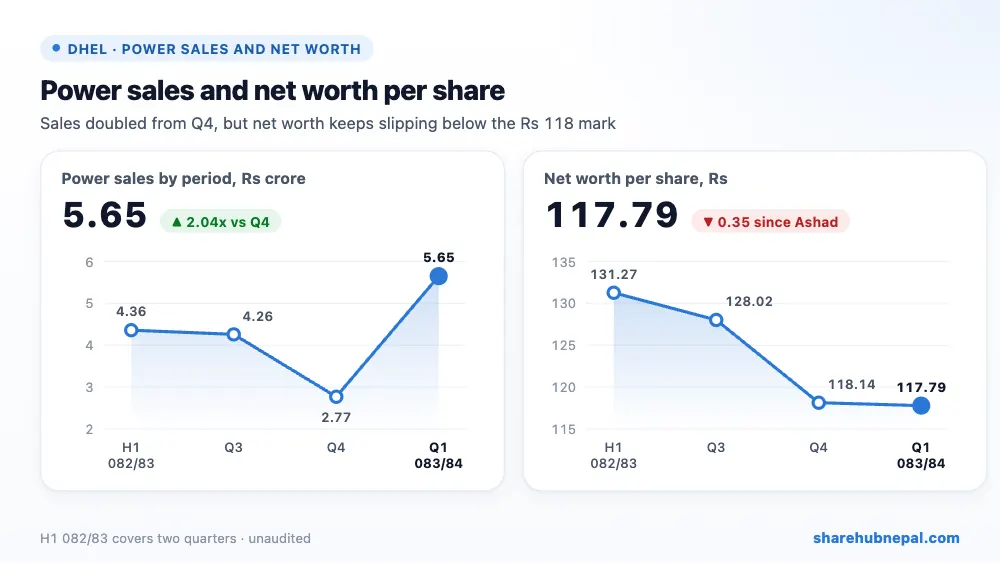
| Net worth per share | Rs 117.79 |
| Total assets per share | Rs 278.28 |
| Market price (Q1 close) | Rs 507 |
| P/E | loss (report −1,445.86) |
| P/B | 4.3x |
| Liquidity ratio | 0.57 |
| Debt to equity | 1.31x |
The Q1 closing price was Rs 507 (range Rs 485.10 to Rs 630). With a loss there is no meaningful P/E (the report prints −1,445.86). The price is 4.3 times net worth per share of Rs 117.79, which is expensive for a company that has not yet made a profit and whose net worth is falling.
Conclusion
Positives: the best monsoon sales so far (Rs 5.65 crore in one quarter), very low cost of sales, earning before interest of Rs 2.38 crore, a court decision in the project's favour against the hydro-mechanical contractor, and interest cost that fell from Q4.
Watch: how long generation stays stopped after the 9 Ashwin flood damage to the transmission line, interest that is bigger than operating profit, very low cash and a liquidity ratio of 0.57, the civil contractor's claim (now a writ at the Patan High Court) and the hydro-mechanical contractor's appeal, the unexplained fall in project assets, and the missing Q1 2082/83 comparison.
The monsoon quarter brought DHEL close to break-even, but the plant still cannot earn enough to pay its interest, and the flood damage to the transmission line puts the next quarters at risk. Until generation is steady and debt comes down, losses and a slowly falling net worth are likely to continue.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

