













Dibyashwori Hydropower Ltd. – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
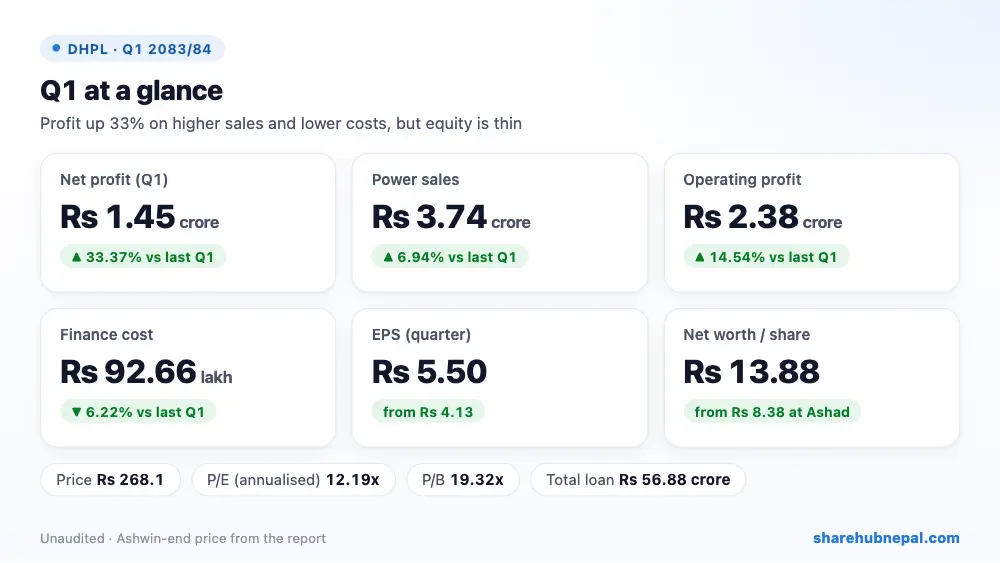
Dibyashwori Hydropower earned Rs 1.45 crore in the first quarter of 2083/84, up 33.37% from Rs 1.09 crore a year ago (restated). Power sales rose 6.94% to Rs 3.74 crore, admin cost fell and finance cost dropped 6.22%. Quarter EPS is Rs 5.50 (about Rs 22 annualised). The weak point is the balance sheet: accumulated losses of Rs 22.73 crore leave net worth at only Rs 13.88 per share, and the company says it has not been able to pay bank principal and interest on time.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sales | Rs 37,389,168 | Rs 34,962,934 | +6.94% |
| Cost of sales | Rs 2,780,803 | Rs 1,819,233 | +52.86% |
| Other income | Rs 0 | Rs 0 | – |
| Operating profit | Rs 23,797,148 | Rs 20,776,210 | +14.54% |
| Finance cost | Rs 9,265,832 | Rs 9,880,667 | −6.22% |
| Income tax | Rs 0 | Rs 0 | – |
| Net profit | Rs 14,531,316 | Rs 10,895,543 | +33.37% |
| EPS (quarter) | 5.5 | 4.13 | – |
| Net worth per share | 13.88 | 6.99 | – |
1. Where the profit came from
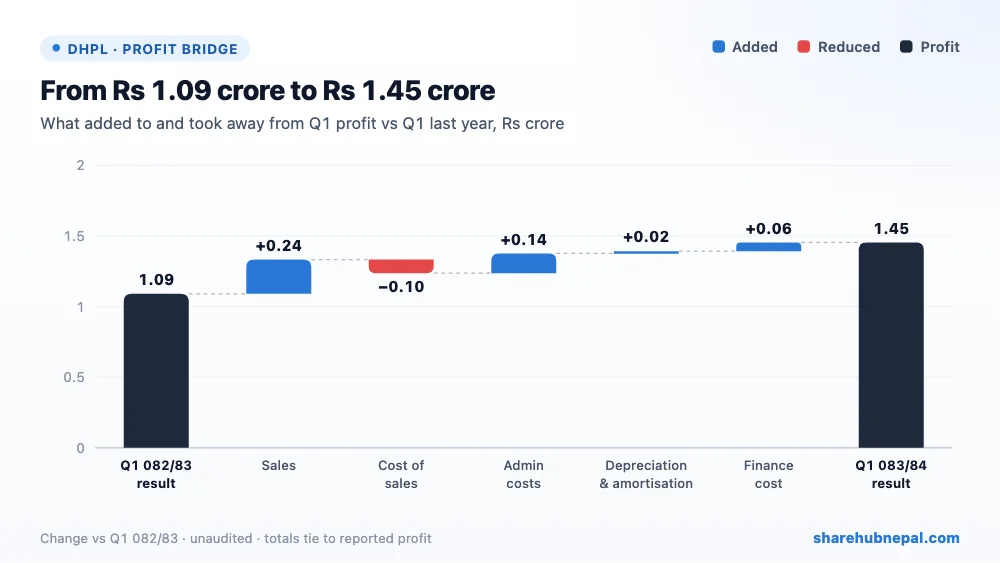
Higher sales added Rs 24.26 lakh, lower admin cost Rs 13.96 lakh, lower finance cost Rs 6.15 lakh and lower depreciation Rs 1.60 lakh. Cost of sales rose by Rs 9.62 lakh. Net effect: profit up Rs 36.36 lakh. There is no tax or bonus provision in either year.
2. Profit through the year
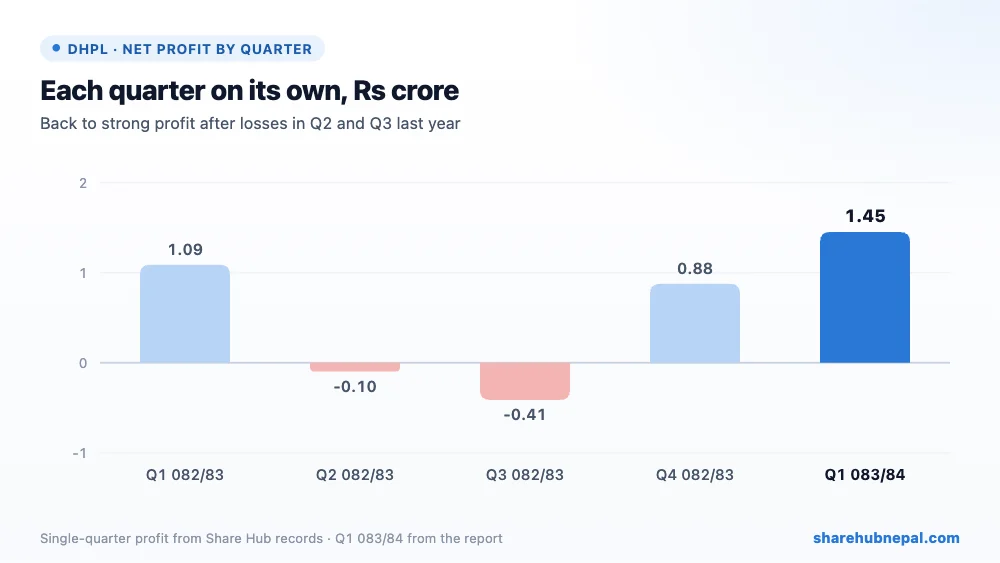
Profit by quarter (Share Hub records): Q1 082/83: Rs 1.09 crore, Q2 082/83: −Rs 9.77 lakh, Q3 082/83: −Rs 41.34 lakh, Q4 082/83: Rs 87.71 lakh, Q1 083/84: Rs 1.45 crore. Q2 and Q3 of 2082/83 were loss-making (dry season), and the full year ended with a profit of Rs 1.46 crore (EPS Rs 5.51). This one quarter has already earned about as much as the whole of last year.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 769,963,741 | Rs 754,291,208 | +2.08% |
| Total equity | Rs 36,655,537 | Rs 22,124,221 | +65.68% |
| Long-term borrowings | Rs 495,623,999 | Rs 500,261,197 | −0.93% |
| Current borrowings | Rs 73,158,317 | Rs 73,158,317 | +0.00% |
| Cash and equivalents | Rs 241,659 | Rs 437,840 | −44.81% |
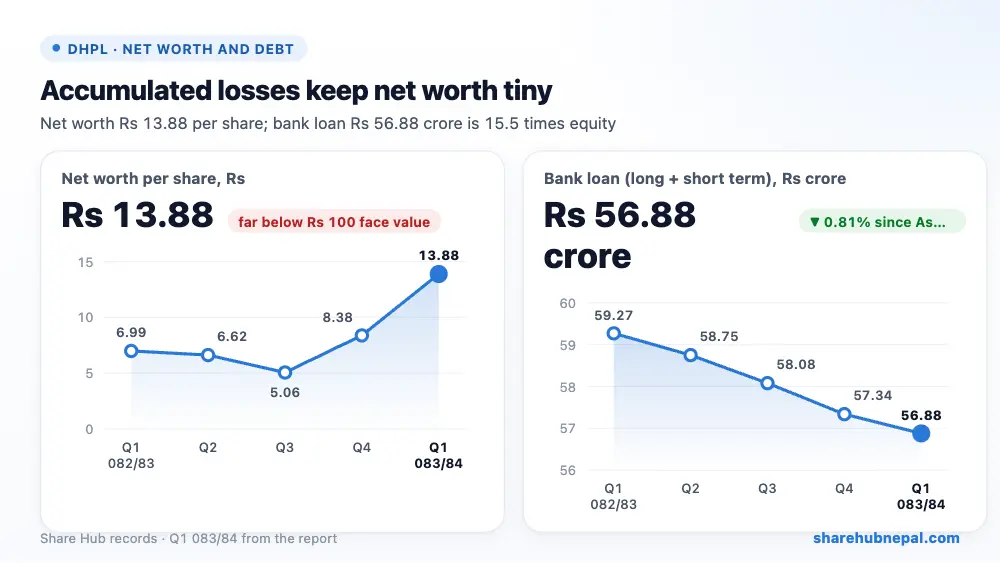
Equity rose by the quarter's profit to Rs 3.67 crore on Rs 26.40 crore of share capital, so net worth per share is Rs 13.88 against the Rs 100 face value. Bank borrowing is Rs 56.88 crore (Rs 49.56 crore long-term plus Rs 7.32 crore short-term), about 15.5 times equity, and other financial liabilities of Rs 15.55 crore sit in current liabilities. Trade receivables doubled to Rs 5.14 crore since Ashad while cash is only Rs 2.42 lakh. The current ratio is 0.26.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 22.00 |
| Net worth per share | Rs 13.88 |
| Market price (Ashwin end) | Rs 268.1 |
| P/E (annualised) | 12.19x |
| P/B | 19.32x |
At the Ashwin-end price of Rs 268.1, the share trades at 12.19 times annualised EPS and 19.32 times net worth per share. The low P/E reflects a seasonal quarter; on last year's full-year EPS of Rs 5.51 the P/E is about 49, and the price is more than 19 times net worth per share.
Conclusion
Positives: profit up 33%, sales up 7%, lower admin and finance cost, best quarter in five.
Watch: accumulated losses (net worth Rs 13.88/share), debt 15.5x equity, irregular loan repayment, receivables doubled, almost no cash, current ratio 0.26, dry-season losses, two pending court cases.
Operations improved, but DHPL is still a highly indebted company with a very thin equity base; dry-season quarters will show whether it can keep paying its bank.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

