













Dolti Power Company Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
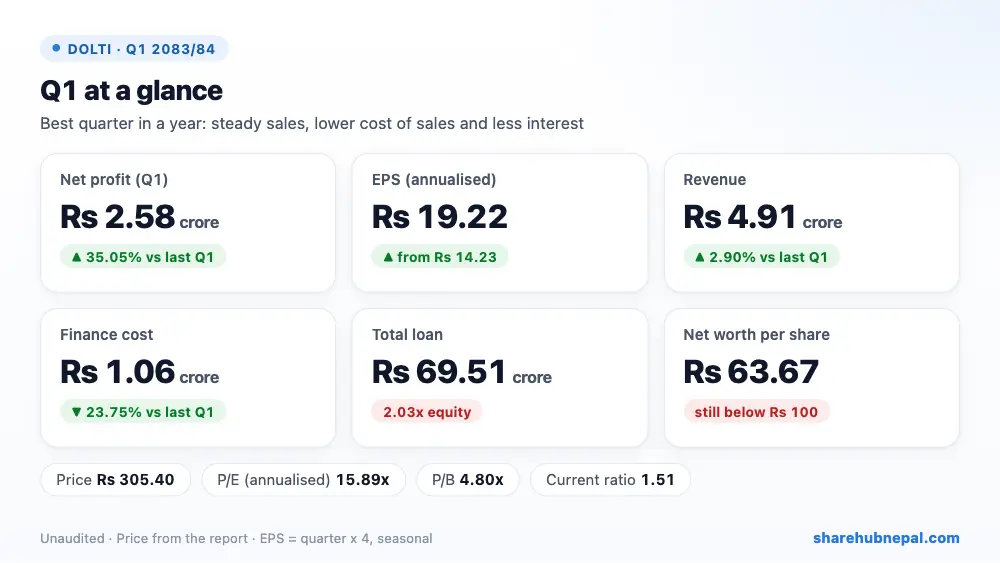
Dolti Power, which runs the 4.8 MW Padam Khola small hydropower project, earned a net profit of Rs 2.58 crore in the first quarter, up 35.05% from Rs 1.91 crore a year ago. Quarter EPS is Rs 4.81, or Rs 19.22 annualised.
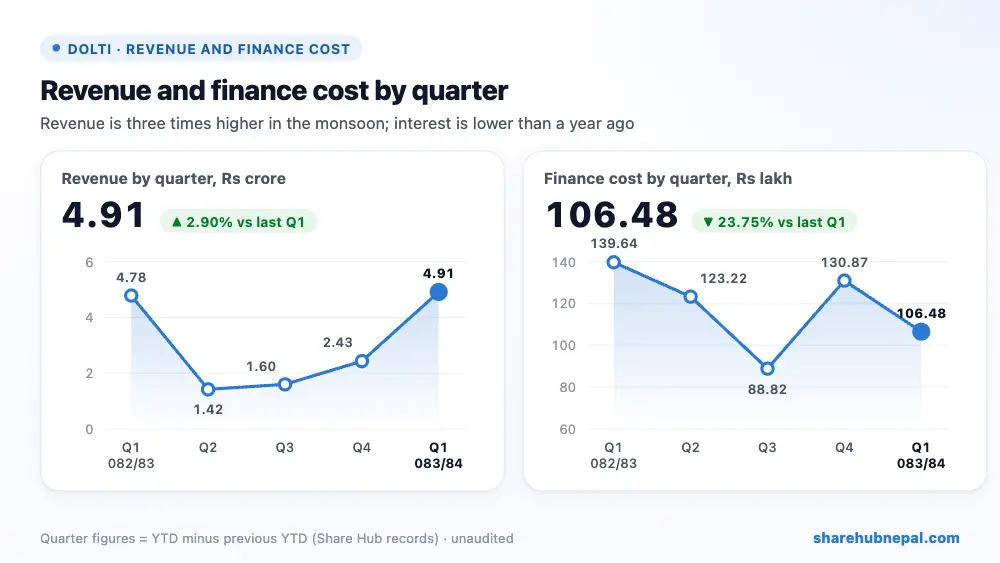
Revenue rose only 2.90% to Rs 4.91 crore. Profit grew mainly because cost of sales fell to Rs 18.90 lakh from Rs 44.44 lakh and finance cost fell 23.75% to Rs 1.06 crore. The company says NEA paid its power bills regularly this quarter. Net margin rose to 52.46% from 39.97%.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sale of energy | Rs 49,139,243 | Rs 47,753,556 | +2.90% |
| Cost of sales | Rs 1,889,594 | Rs 4,443,931 | −57.48% |
| Employee and administrative expenses | Rs 2,173,163 | Rs 1,499,141 | +44.96% |
| Depreciation and amortisation | Rs 8,648,738 | Rs 8,757,373 | −1.24% |
| Earnings before interest and tax | Rs 36,427,748 | Rs 33,053,112 | +10.21% |
| Finance cost | Rs 10,648,061 | Rs 13,964,054 | −23.75% |
| Net profit | Rs 25,779,687 | Rs 19,089,057 | +35.05% |
| EPS (quarter) | 4.81 | 3.56 | – |
1. Where the profit came from
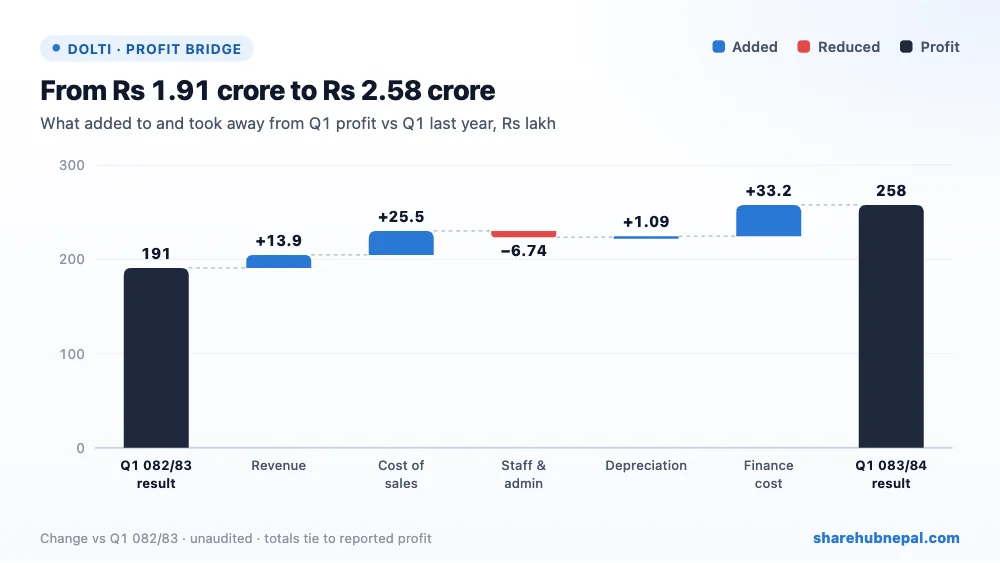
Compared with last year's Q1, lower finance cost added Rs 33.16 lakh, lower cost of sales Rs 25.54 lakh, higher revenue Rs 13.86 lakh and slightly lower depreciation Rs 1.09 lakh. Higher staff and administrative costs took away Rs 6.74 lakh.
2. Profit through the year
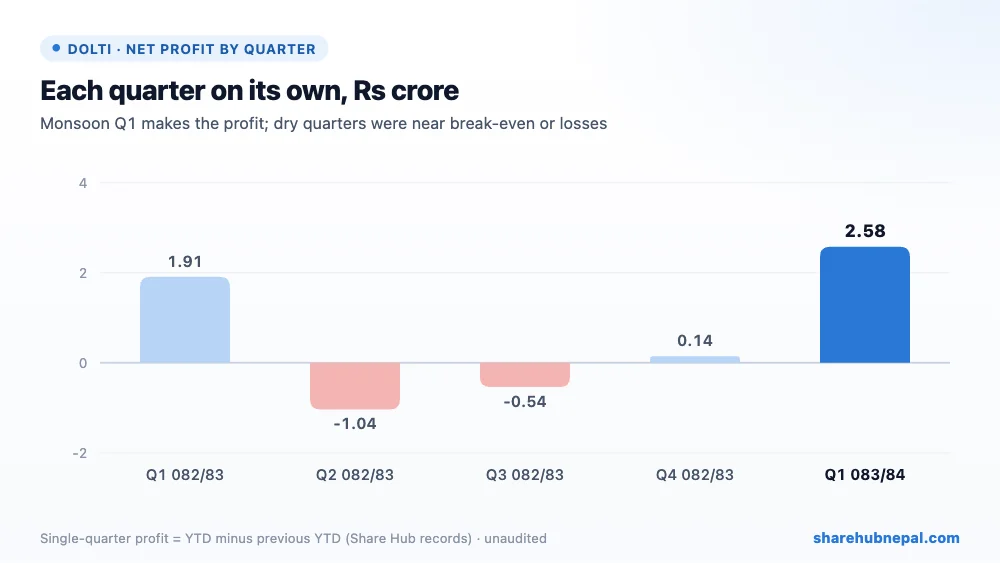
Based on Share Hub's records, single-quarter results in 2082/83 were a profit of Rs 1.91 crore in Q1, losses of Rs 1.04 crore in Q2 and Rs 53.86 lakh in Q3, and a profit of Rs 14.31 lakh in Q4 (full year Rs 47.69 lakh, EPS 0.89). So the annualised EPS of Rs 19.22 is far above what a full year usually earns.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Long-term borrowings | Rs 618,009,183 | Rs 601,084,821 | +2.82% |
| Short-term loans | Rs 77,080,668 | Rs 111,494,070 | −30.87% |
| Intangible (project) assets | Rs 907,072,288 | Rs 915,171,556 | −0.88% |
| Other current assets | Rs 124,616,787 | Rs 114,616,787 | +8.72% |
| Total assets | Rs 1,057,033,250 | Rs 1,054,550,836 | +0.24% |
| Total equity | Rs 341,579,872 | Rs 315,800,185 | +8.16% |
Total loan is Rs 69.51 crore (Rs 61.80 crore long-term and Rs 7.71 crore short-term), down from Rs 71.26 crore at Ashad end but still 2.03 times equity. The accumulated loss is Rs 19.49 crore, so equity of Rs 34.16 crore is well below paid-up capital, and net worth per share is only Rs 63.67. Other current assets of Rs 12.46 crore make up most of current assets. The report's Ashad equity (Rs 31.58 crore, capital Rs 53.65 crore) differs from Share Hub's Q4 record (Rs 32.93 crore, capital Rs 55.00 crore).
4. Per-share figures and valuation
| Indicator | Value |
| EPS (quarter) | Rs 4.81 |
| EPS (annualised, derived) | Rs 19.22 |
| Net worth per share | Rs 63.67 |
| Market price (report) | Rs 305.40 |
| P/E (annualised EPS) | 15.89x |
| P/B | 4.80x |
| Current ratio | 1.51 |
At Rs 305.40 the share trades at 15.89 times annualised EPS and 4.80 times net worth per share. The report prints a P/E of 69.56, which does not match its own price and EPS. On last year's full-year EPS of Rs 0.89 the P/E would be above 300.
Conclusion
Positives: profit up 35.05%, finance cost and cost of sales down, loans being repaid, and regular payment from NEA.
Watch: an accumulated loss of Rs 19.49 crore and net worth per share of only Rs 63.67, debt at 2.03 times equity, weak dry-season quarters, a P/B of 4.80x, and Ashad figures that differ from Share Hub's Q4 record.
Dolti had a good monsoon quarter thanks to lower costs and interest, but the dry months have usually wiped out most of the gain. The accumulated loss will take years to clear at this pace.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

