













Eastern Hydropower Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
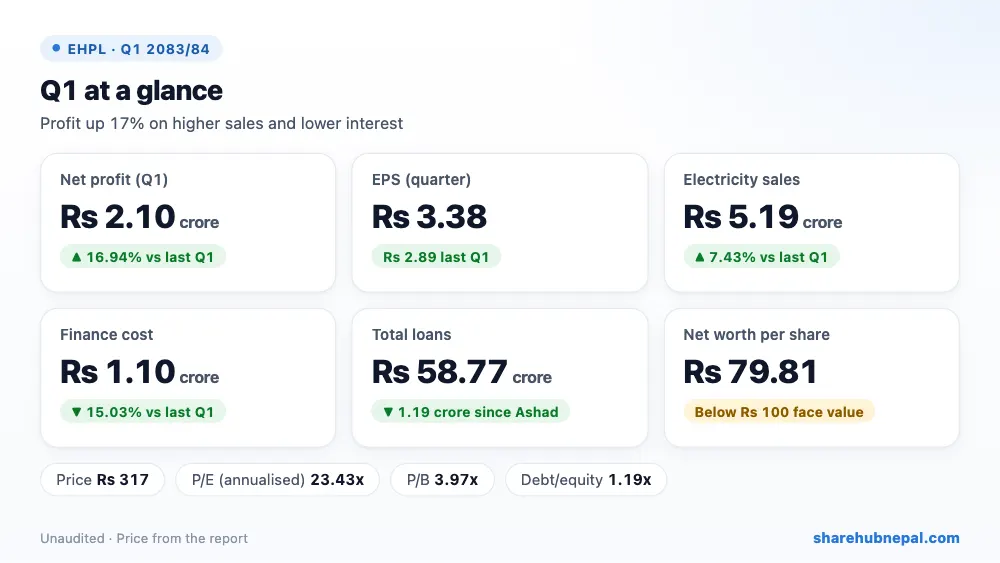
Eastern Hydropower earned a net profit of Rs 2.10 crore in the first quarter, up 16.94% from Rs 1.79 crore a year ago. EPS for the quarter is Rs 3.38.
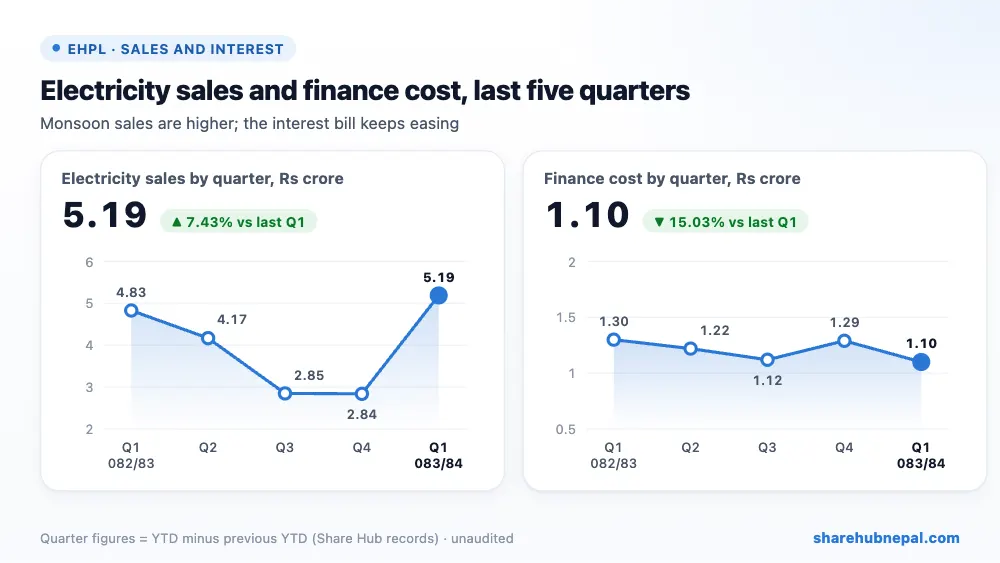
Electricity sales rose 7.43% to Rs 5.19 crore and finance cost fell 15.03% to Rs 1.10 crore as loans were paid down. Cost of sales rose 43.71% and staff and administrative costs also rose, which held back the gain.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Electricity sales | Rs 51,852,333 | Rs 48,268,395 | +7.43% |
| Gross profit | Rs 46,813,479 | Rs 44,762,240 | +4.58% |
| Profit before finance cost, bonus and tax | Rs 32,412,274 | Rs 31,258,309 | +3.69% |
| Finance cost | Rs 11,008,801 | Rs 12,955,809 | −15.03% |
| Net profit | Rs 20,975,404 | Rs 17,936,450 | +16.94% |
| EPS (quarter) | 3.38 | 2.89 | – |
1. Where the profit came from
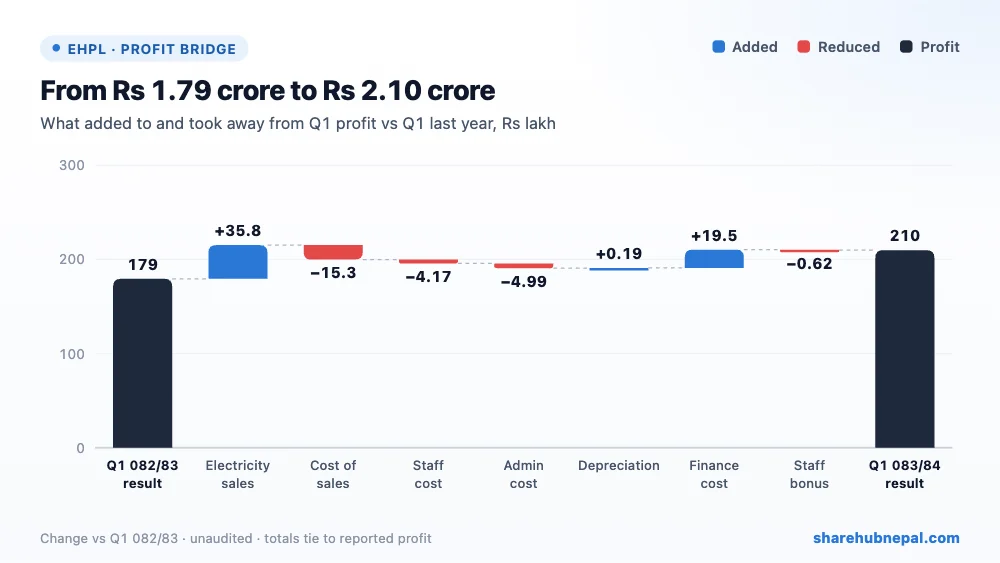
Compared with last year's Q1, higher sales added Rs 35.84 lakh and lower finance cost Rs 19.47 lakh. Higher cost of sales took away Rs 15.33 lakh, higher administrative cost Rs 4.99 lakh, higher staff cost Rs 4.17 lakh and a larger staff bonus Rs 62,019.
2. Profit through the year
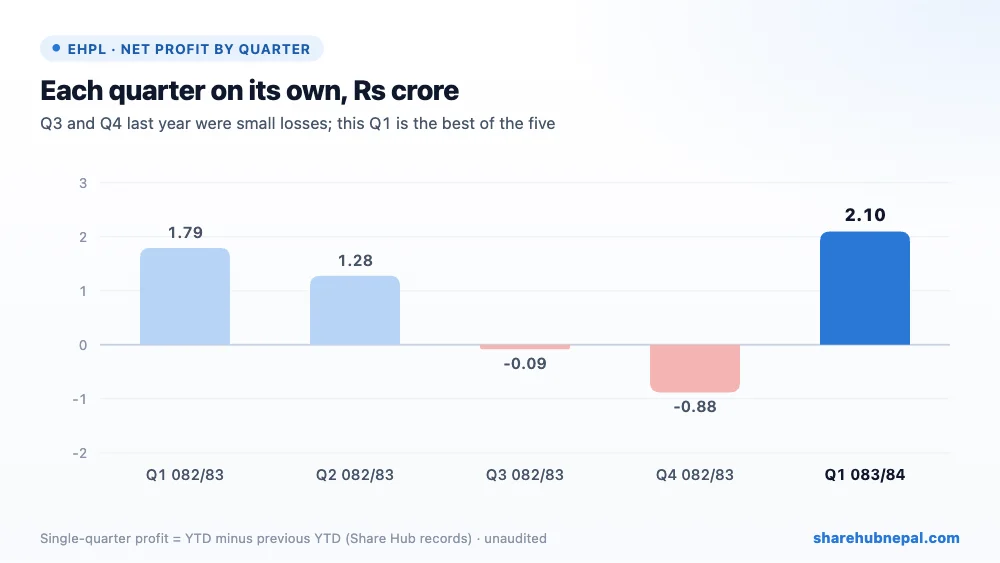
Based on Share Hub's records (annualised EPS of Q1 and Q2 2082/83 corrected in this update), single-quarter profits in 2082/83 were Rs 1.79 crore in Q1 and Rs 1.28 crore in Q2, followed by small losses of Rs 8.54 lakh in Q3 and Rs 88.24 lakh in Q4. This report shows the full-year 2082/83 profit as Rs 2.18 crore, slightly above the Rs 2.10 crore in the Q4 report. This Q1 alone has nearly matched it.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Long-term loans | Rs 545,820,503 | Rs 559,979,903 | −2.53% |
| Short-term loans | Rs 41,911,824 | Rs 39,646,320 | +5.71% |
| Intangible (project) assets | Rs 952,028,645 | Rs 964,282,320 | −1.27% |
| Trade and other receivables | Rs 80,005,104 | Rs 59,072,425 | +35.44% |
| Cash and cash equivalents | Rs 48,899,129 | Rs 52,948,589 | −7.65% |
| Total equity | Rs 494,819,645 | Rs 473,844,241 | +4.43% |
Total bank loans fell Rs 1.19 crore in the quarter to Rs 58.77 crore (long-term Rs 54.58 crore, short-term Rs 4.19 crore), 1.19 times equity. Receivables rose to Rs 8.00 crore from Rs 5.91 crore as monsoon sales came in. The current ratio is a healthy 2.79. Accumulated losses of Rs 12.52 crore keep net worth per share (Rs 79.81) below the Rs 100 face value.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (quarter) | Rs 3.38 |
| EPS (annualised) | Rs 13.53 |
| Net worth per share | Rs 79.81 |
| Market price (report) | Rs 317 |
| P/E on annualised EPS | 23.43x |
| P/B | 3.97x |
| Current ratio | 2.79 |
At Rs 317 the share trades at 23.43 times annualised Q1 EPS and 3.97 times net worth per share. The report's own P/E of 93.70 uses the quarter's EPS. On last year's full-year EPS of about Rs 3.52 the P/E is about 90, so the price already assumes a much better year.
Conclusion
Positives: profit up 16.94%, sales up 7.43%, finance cost down 15.03%, loans falling, and a good current ratio (2.79).
Watch: cost of sales up 43.71%, rising staff and admin costs, losses in Q3 and Q4 last year, net worth below face value, and a high price compared with full-year earnings.
Eastern Hydropower had a good monsoon quarter with more sales and lower interest. Controlling rising operating costs and avoiding dry-season losses will decide the full-year result.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

