













Emerging Nepal Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
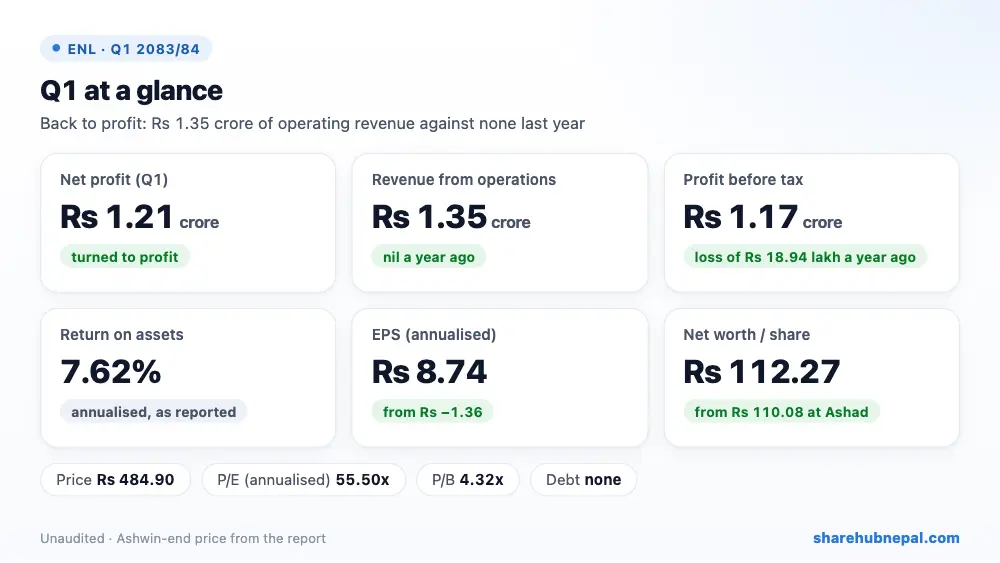
Emerging Nepal, an investment company, earned Rs 1.21 crore in the first quarter, against a loss of Rs 18.94 lakh a year ago. The change comes from Rs 1.35 crore of revenue from operations (income from its investments), which it did not have in last year's Q1. Costs are small (Rs 20.19 lakh) and the company has no debt. A deferred-tax credit of Rs 4.55 lakh added a little. Annualised EPS is Rs 8.74.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sales | Rs 13,500,108 | Rs 0 | – |
| Cost of sales | Rs 0 | Rs 0 | – |
| Other income | Rs 200,643 | Rs 513,661 | −60.94% |
| Operating profit | Rs 11,682,019 | −Rs 1,894,316 | Turned to profit |
| Finance cost | Rs 0 | Rs 0 | – |
| Income tax | −Rs 454,522 | Rs 0 | – |
| Net profit | Rs 12,136,541 | −Rs 1,894,316 | Turned to profit |
| EPS (annualised) | 8.74 | -1.36 | – |
| Net worth per share | 112.27 | 108.52 | – |
1. Where the profit came from
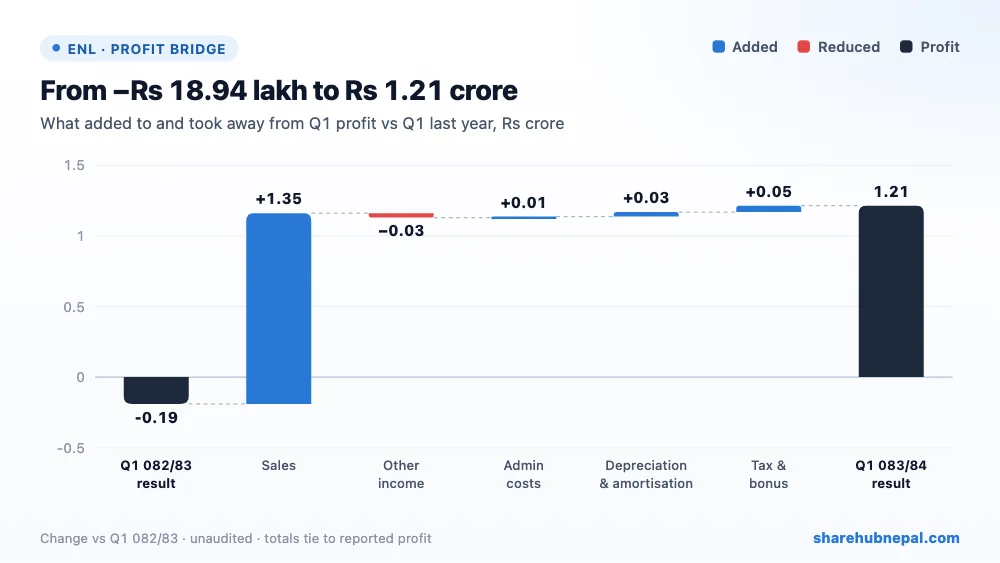
Revenue from operations added Rs 1.35 crore. Lower depreciation (Rs 3.11 lakh) and admin costs (Rs 78,114) helped a little, while other income fell Rs 3.13 lakh. The report does not say which investment paid the income; investment companies usually earn lumpy dividend income, so one quarter may not repeat.
2. Profit through the year
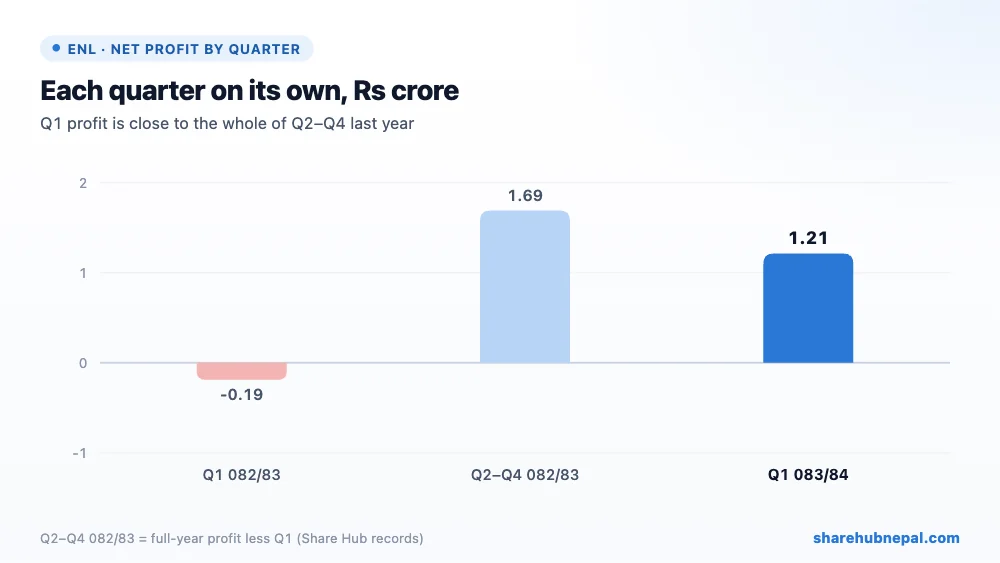
Profit by quarter (Share Hub records): Q1 082/83: −Rs 18.94 lakh, Q2–Q4 082/83: Rs 1.69 crore, Q1 083/84: Rs 1.21 crore. FY 2082/83 profit was Rs 1.50 crore (EPS Rs 2.70).
3. Balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 636,754,426 | Rs 625,166,676 | +1.85% |
| Total equity | Rs 623,764,242 | Rs 611,627,751 | +1.98% |
| Long-term borrowings | Rs 0 | Rs 0 | – |
| Cash and equivalents | Rs 22,570,161 | Rs 17,069,922 | +32.22% |
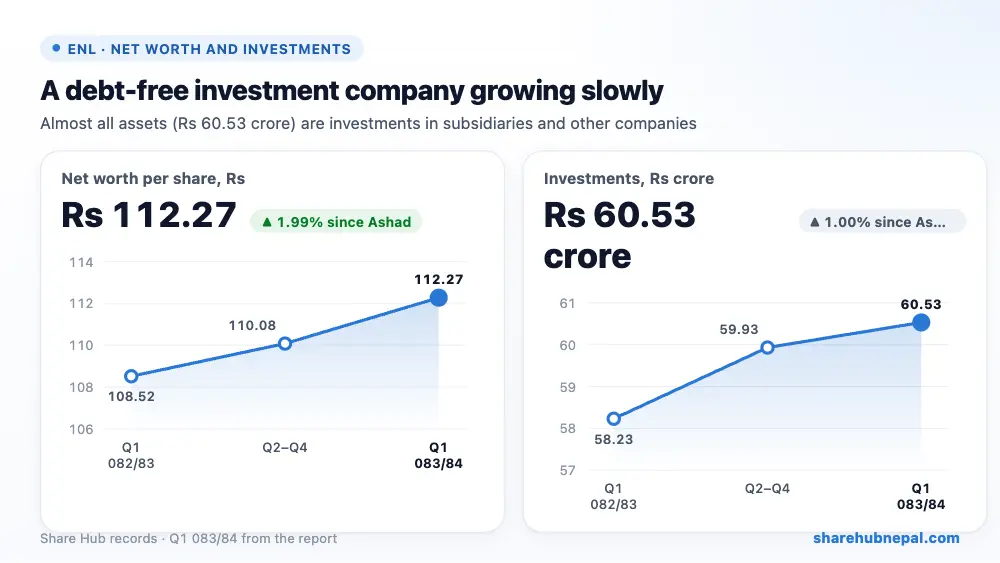
Investments are Rs 60.53 crore, 95% of total assets. The company owns 71.90% of Emerging Venture and 92.72% of Hotel Alice the Wonder; of the three hydropower projects promoted by its investee companies, one is running and two are under construction. Cash is Rs 2.26 crore, there is no loan, and net worth per share rose to Rs 112.27.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 8.74 |
| Net worth per share | Rs 112.27 |
| Market price (Ashwin end) | Rs 484.9 |
| P/E (annualised) | 55.48x |
| P/B | 4.32x |
At the Ashwin-end price of Rs 484.9, the share trades at 55.48 times annualised EPS and 4.32 times net worth per share. That is expensive for an investment company whose income is lumpy; FY 2082/83 EPS was only Rs 2.70.
Conclusion
Positives: back to profit, no debt, low costs, net worth per share rising, possible new investment areas allowed by SEBON.
Watch: lumpy and unexplained revenue, dependence on a few unlisted investments, hydropower projects still under construction, and a high P/E and P/B.
A good quarter, but ENL's value depends on its investments starting to pay regular income. Watch whether revenue continues in the next quarters.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

