













GreenLife Hydropower Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
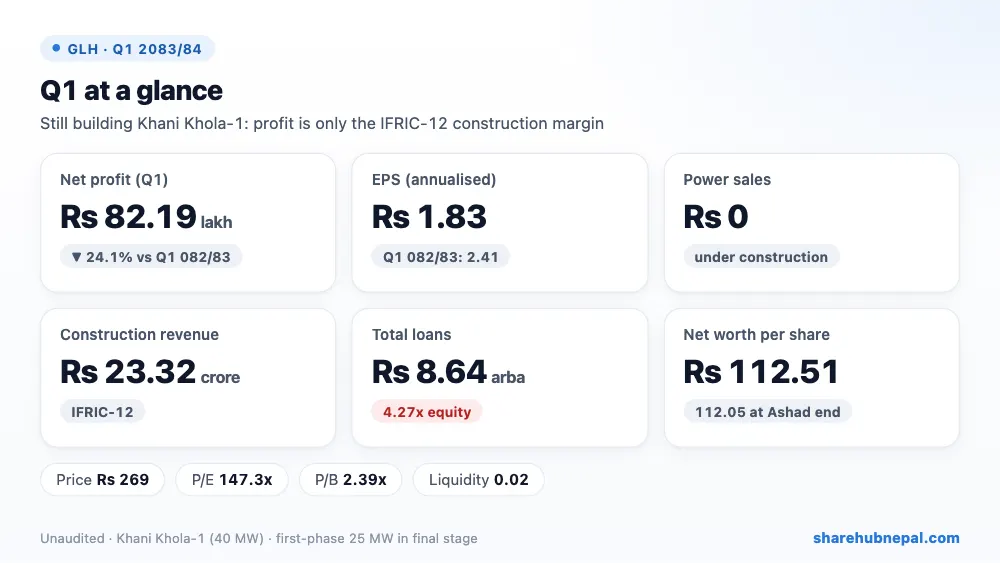
GreenLife Hydropower earned a net profit of Rs 82.19 lakh in the first quarter of 2083/84, down 24.07% from Rs 1.08 crore a year ago. Annualised EPS is Rs 1.83 and net worth per share is Rs 112.51.
GreenLife has no electricity sales yet. It is building the 40 MW Khani Khola-1 project in Dolakha, and the company says construction of the first 25 MW phase is in its final stage. The 'profit' is an accounting figure under IFRIC-12: the company books construction revenue of Rs 23.32 crore against construction cost of Rs 22.00 crore, leaving a margin of Rs 1.32 crore, from which admin cost of Rs 49.70 lakh is taken.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
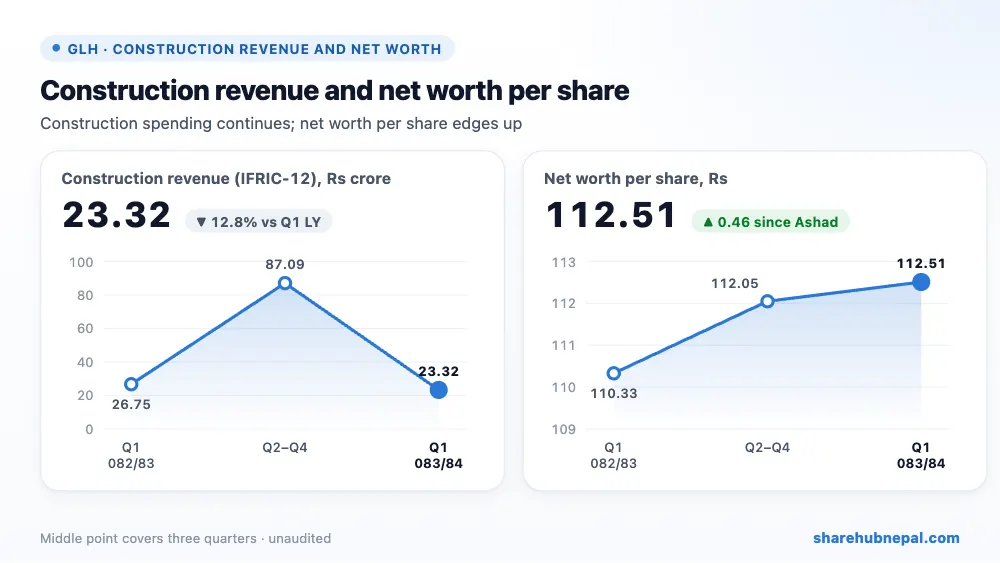
| Construction revenue (IFRIC-12) | Rs 233,224,751 | Rs 267,529,105 | −12.82% |
| Construction cost (IFRIC-12) | Rs 220,023,350 | Rs 252,385,949 | −12.82% |
| Gross profit (construction margin) | Rs 13,201,401 | Rs 15,143,156 | −12.82% |
| Administrative expenses | Rs 4,969,572 | Rs 4,273,607 | +16.29% |
| Profit from operations | Rs 8,231,829 | Rs 10,869,550 | −24.27% |
| Net profit | Rs 8,218,515 | Rs 10,823,369 | −24.07% |
1. Where the profit came from
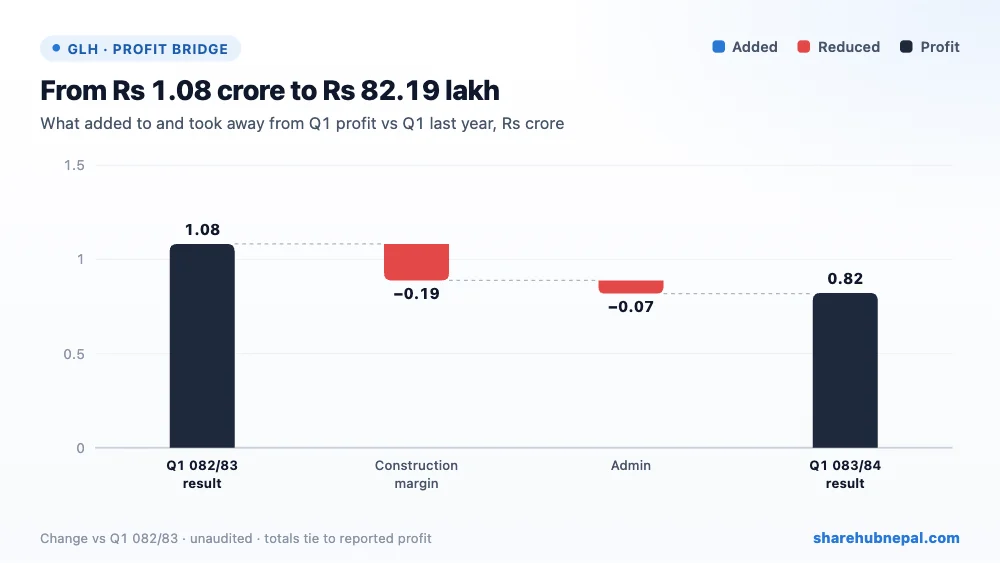
Against Q1 last year, a smaller construction margin took away Rs 19.42 lakh (less construction work was booked) and higher admin cost Rs 6.96 lakh. Net: profit down Rs 26.05 lakh. None of this is cash from selling power.
2. Profit through the year
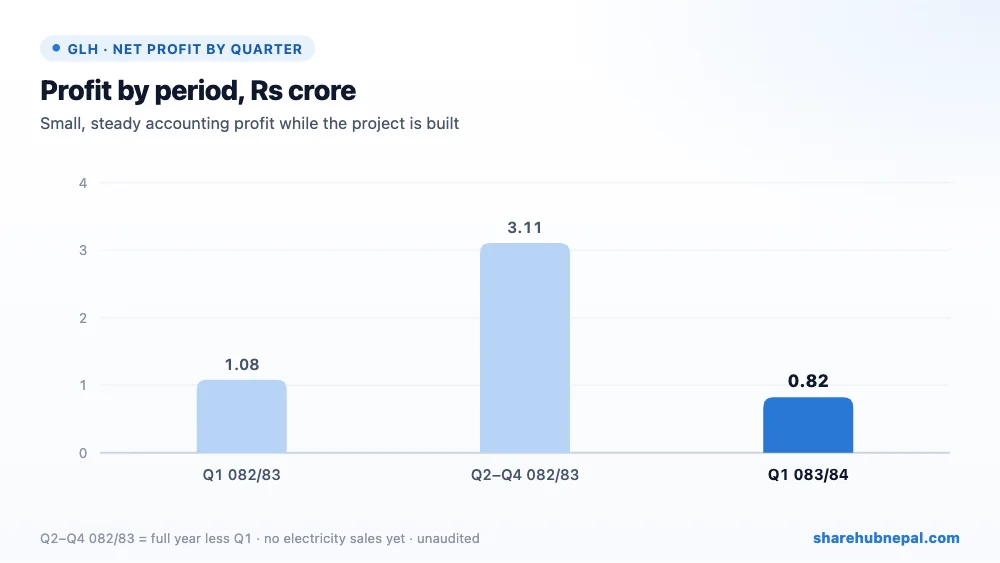
GLH reports a small profit every quarter while it builds: Rs 1.08 crore in Q1 2082/83, Rs 3.11 crore in the other three quarters together, Rs 4.19 crore for the year (EPS 2.33). These numbers will change completely once the plant starts selling power; until then, the EPS says little about the company's real earning power.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| SCA assets under development (project) | Rs 11,518,692,013 | Rs 11,285,467,262 | +2.07% |
| Cash and cash equivalents | Rs 12,664,872 | Rs 18,554,849 | −31.74% |
| Long-term loans | Rs 8,327,307,140 | Rs 8,150,684,838 | +2.17% |
| Short-term loans | Rs 312,092,392 | Rs 246,735,510 | +26.49% |
| Other current financial liabilities | Rs 756,720,692 | Rs 762,923,994 | −0.81% |
| Total equity | Rs 2,025,169,227 | Rs 2,016,950,712 | +0.41% |
The project (SCA assets) has reached Rs 11.52 arba, funded mostly by loans: Rs 8.33 arba long-term and Rs 31.21 crore short-term, about 4.27 times equity, plus Rs 75.67 crore of other current financial liabilities. Cash is only Rs 1.27 crore, and the liquidity ratio is 0.02. Current liabilities more than doubled from a year ago. This is normal for a project in its last construction stage, but it leaves little room for delays.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised, report) | Rs 1.83 |
| Net worth per share | Rs 112.51 |
| Total assets per share | Rs 664.54 |
| Market price (Q1 close) | Rs 269 |
| P/E (report) | 147.29x |
| P/B | 2.39x |
| Liquidity ratio | 0.02 |
| Debt to equity | 4.27x |
The Q1 closing price was Rs 269 (range Rs 238.10 to Rs 287.70). The P/E of 147 is not meaningful for a company still under construction. The price is 2.39 times net worth per share — investors are paying for the expected start of generation.
Conclusion
Positives: the first 25 MW phase is in its final construction stage, there are no legal cases, and equity is growing slowly.
Watch: the commercial operation date, very high debt and almost no cash, current liabilities more than double a year ago, and the fact that today's profit is only an accounting construction margin.
GLH is a construction-stage company. Judge it by progress on Khani Khola-1 and the start of power sales, not by the small IFRIC-12 profit.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

