













Himal Dolakha Hydropower Company Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (from Share Hub's Q1 2082/83 record, because the report shows only the year-end column) and with Ashad end 2083.
Summary
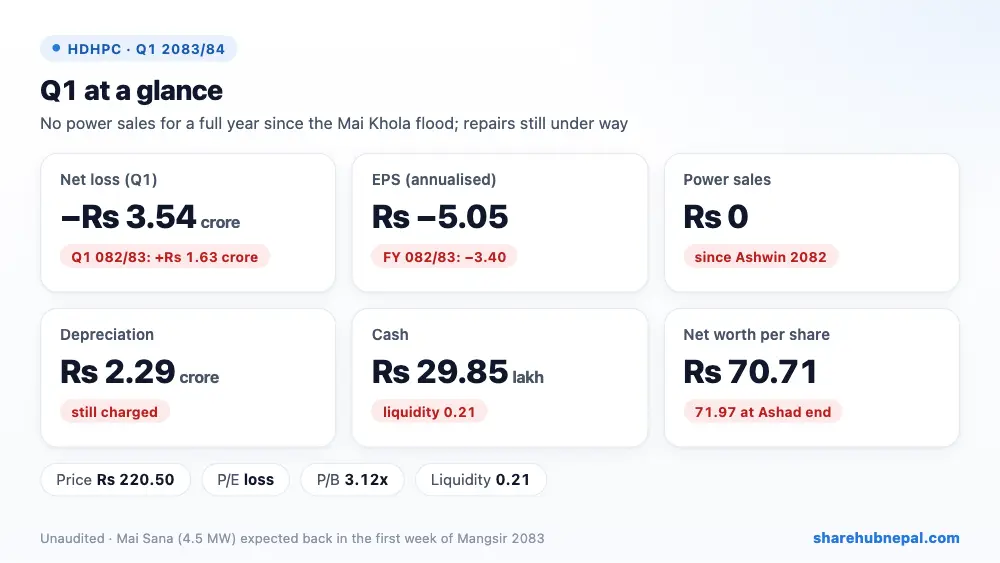
Himal Dolakha Hydropower made a net loss of Rs 3.54 crore in the first quarter of 2083/84, against a profit of Rs 1.63 crore in the same quarter last year (Share Hub record). Annualised EPS is Rs −5.05 and net worth per share fell to Rs 70.71.
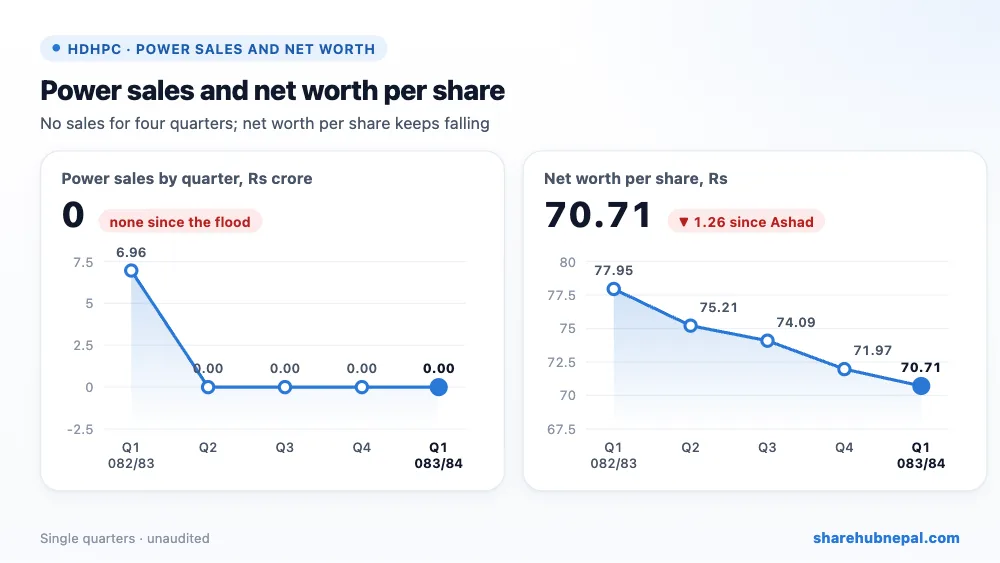
The company sold no electricity at all in the quarter. Its plants on the Mai Khola in Ilam were damaged by the severe flood of 18 Ashwin 2082, and repair and rebuilding work is still going on. In fact last year's first quarter brought in all of the Rs 6.96 crore sales for 2082/83 — nothing has been sold since the flood. The company says the 4.5 MW Mai Sana project should restart in the first week of Mangsir 2083.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Income from power sales | Rs 0 | Rs 69,604,770 | −100.00% |
| Project expenses | Rs 2,885,751 | Rs 15,791,790 | −81.73% |
| Royalty | Rs 312,500 | Rs 1,704,600 | −81.67% |
| Administrative expenses | Rs 4,833,386 | Rs 9,436,750 | −48.78% |
| Financial cost | Rs 4,437,403 | Rs 4,402,990 | +0.78% |
| Depreciation | Rs 22,904,924 | Rs 21,982,320 | +4.20% |
| Net profit (loss) | −Rs 35,373,964 | Rs 16,286,320 | Turned to loss |
1. Where the profit came from
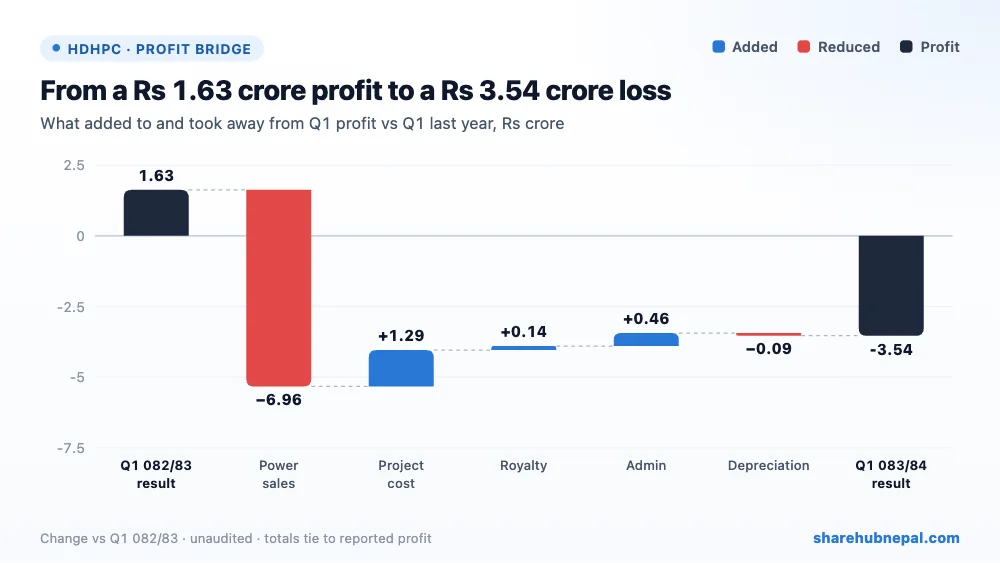
Against Q1 last year, lost power sales took away Rs 6.96 crore. Lower project cost (Rs 1.29 crore), admin cost (Rs 46.03 lakh) and royalty (Rs 13.92 lakh) gave a little back, but depreciation (Rs 2.29 crore) and interest (Rs 44.37 lakh) carry on whether the plant runs or not. Net: profit fell Rs 5.17 crore.
2. Profit through the year
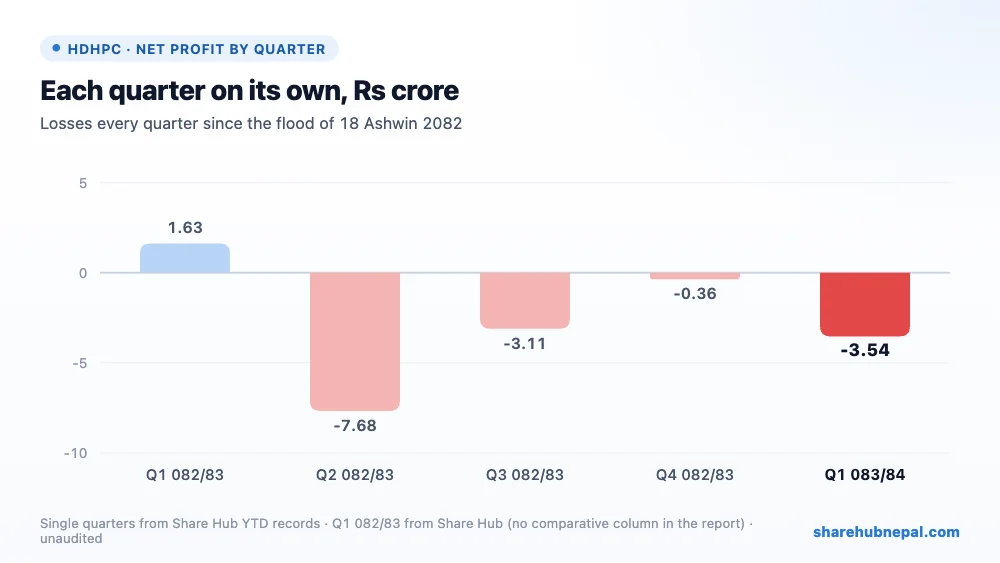
After a profit of Rs 1.63 crore in Q1 2082/83, HDHPC lost Rs 7.68 crore in Q2, Rs 3.11 crore in Q3 and Rs 36.23 lakh in Q4, ending 2082/83 with a loss of Rs 9.52 crore (EPS −3.40). Losses will continue until at least one plant is back in service; Mai Sana's restart in Mangsir is the first step.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Net fixed assets | Rs 1,809,489,014 | Rs 1,832,393,938 | −1.25% |
| Investments | Rs 570,000,000 | Rs 570,000,000 | +0.00% |
| Advances, loans and deposits | Rs 52,554,544 | Rs 42,054,544 | +24.97% |
| Cash and bank | Rs 2,985,015 | Rs 10,492,515 | −71.55% |
| Long-term loan | Rs 192,572,016 | Rs 192,572,016 | +0.00% |
| Trade and other payables | Rs 85,858,100 | Rs 108,796,560 | −21.08% |
| Total equity | Rs 1,979,894,556 | Rs 2,015,268,520 | −1.76% |
Cash is almost gone (Rs 29.85 lakh), current liabilities (Rs 26.26 crore) are nearly five times current assets (Rs 5.55 crore), and the liquidity ratio is just 0.21. The company took a new Rs 3 crore short-term loan, and other financial liabilities rose to Rs 14.67 crore. Equity fell by exactly the Q1 loss; accumulated losses are now Rs 82.01 crore. The company also holds Rs 57 crore of investments. The report does not mention an insurance claim for the flood damage.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised, report) | Rs −5.05 |
| EPS (quarter, derived) | Rs −1.26 |
| Net worth per share | Rs 70.71 |
| Total assets per share | Rs 86.97 |
| Market price (Q1 close) | Rs 220.50 |
| P/E | loss (report −43.63) |
| P/B | 3.12x |
| Liquidity ratio | 0.21 |
The Q1 closing price was Rs 220.50 (range Rs 187.20 to Rs 239). With no sales and a loss, there is no meaningful P/E; the price is 3.12 times net worth per share. The market is pricing a recovery that has not started yet.
Conclusion
Positives: Mai Sana (4.5 MW) is expected back in Mangsir, project and admin costs have been cut, and long-term debt is small.
Watch: no revenue for a full year, very low cash and liquidity, rising short-term liabilities, no word on insurance, the timing of the other plants' repair, and flood and landslide risk at the powerhouse and intake.
HDHPC is in a difficult spot: no sales, thin cash and steady losses. The restart of Mai Sana in Mangsir is the key event to watch; until then, losses of around Rs 3.5 crore a quarter are likely.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

