













Himalayan Hydropower Ltd – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
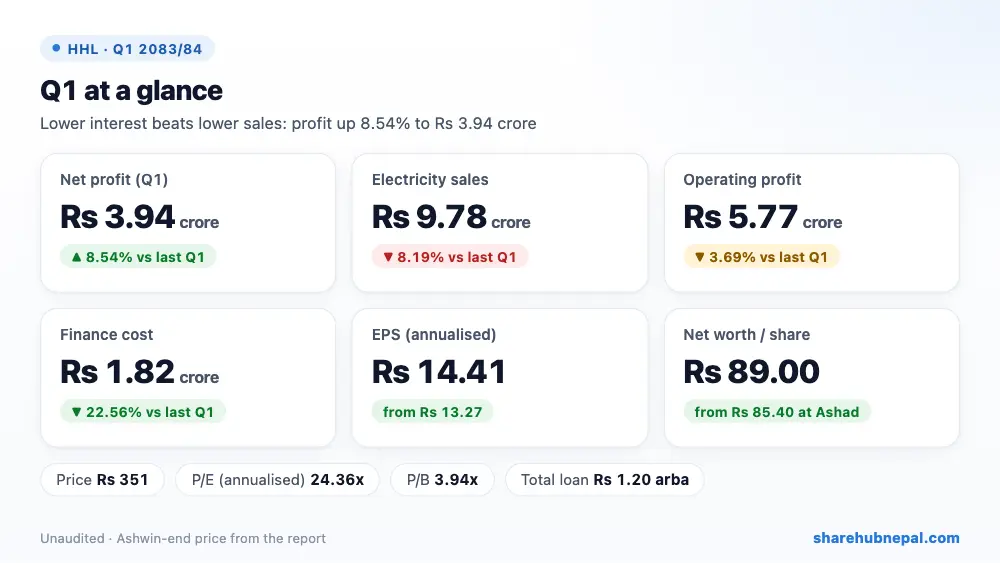
Himalayan Hydropower earned a net profit of Rs 3.94 crore in the first quarter of FY 2083/84, up 8.54% from Rs 3.63 crore a year ago. Electricity sales actually fell 8.19% to Rs 9.78 crore, but finance cost dropped 22.56% to Rs 1.82 crore thanks to lower interest rates and loan repayment, and other direct costs fell 44.86%. Quarter EPS is Rs 3.60 (Rs 14.41 annualised) and net worth per share is Rs 89.00, still below Rs 100 because of past losses. A 1:1 right share issue is awaiting SEBON approval; the money will go to repaying loans.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sales | Rs 97,843,457 | Rs 106,577,205 | −8.19% |
| Cost of sales | Rs 8,459,267 | Rs 15,340,789 | −44.86% |
| Other income | Rs 0 | Rs 0 | – |
| Operating profit | Rs 57,675,403 | Rs 59,885,153 | −3.69% |
| Finance cost | Rs 18,237,382 | Rs 23,551,397 | −22.56% |
| Income tax | Rs 0 | Rs 0 | – |
| Net profit | Rs 39,438,021 | Rs 36,333,755 | +8.54% |
| EPS (annualised) | 14.41 | 13.27 | – |
| Net worth per share | 89 | 81.28 | – |
1. Where the profit came from
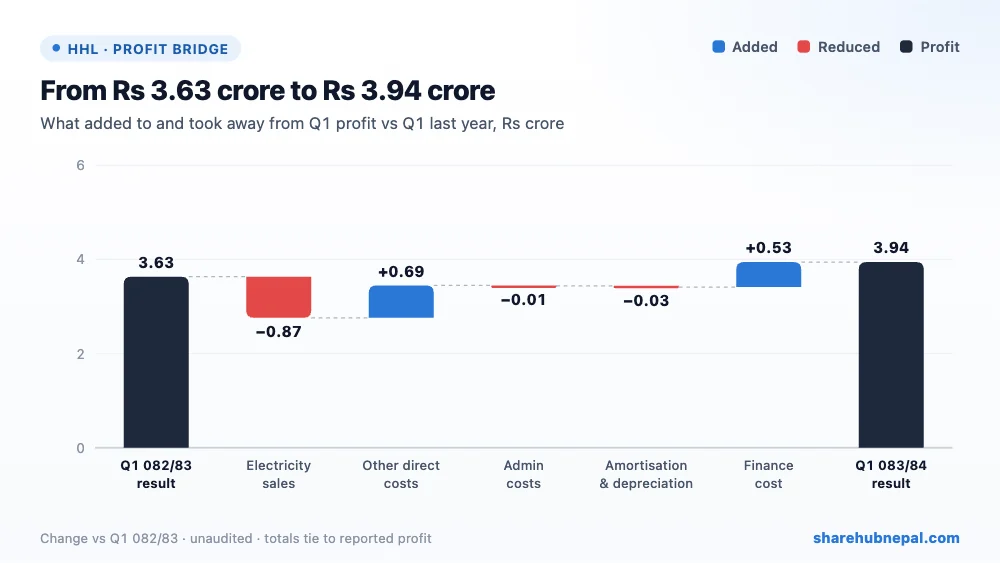
Sales fell to Rs 9.78 crore from Rs 10.66 crore. Other direct costs were Rs 84.59 lakh (Rs 1.53 crore) and project amortisation and depreciation Rs 2.47 crore. Admin costs were Rs 70.45 lakh, so operating profit was Rs 5.77 crore, 3.69% lower. Finance cost fell by Rs 53.14 lakh to Rs 1.82 crore, which more than made up the gap. No tax, bonus or CSR was charged this quarter, so net profit was Rs 3.94 crore.
2. Profit through the year
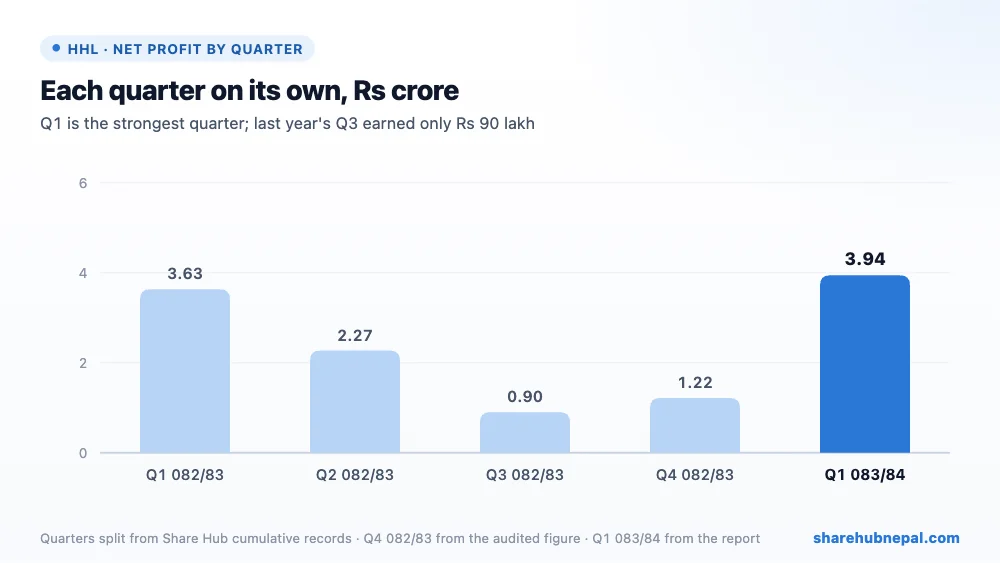
Profit by quarter (Share Hub cumulative records, split into quarters; Q4 from the audited figure in this report): Q1 082/83: Rs 3.63 crore, Q2 082/83: Rs 2.27 crore, Q3 082/83: Rs 90.10 lakh, Q4 082/83: Rs 1.22 crore, Q1 083/84: Rs 3.94 crore. Profit falls sharply in the dry season: last year Q3 earned only Rs 90.10 lakh and the full year Rs 8.02 crore (EPS Rs 7.33). So annualised EPS of Rs 14.41 is about double a normal year.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 2,179,947,540 | Rs 2,252,937,264 | −3.24% |
| Total equity | Rs 974,563,079 | Rs 935,125,058 | +4.22% |
| Long-term loans | Rs 1,095,084,294 | Rs 1,204,989,644 | −9.12% |
| Current loans | Rs 102,743,485 | Rs 101,899,864 | +0.83% |
| Trade and other receivables | Rs 62,346,612 | Rs 56,592,332 | +10.17% |
| Cash and equivalents | Rs 19,537,693 | Rs 71,429,000 | −72.65% |
| Current assets | Rs 107,423,040 | Rs 155,749,409 | −31.03% |
| Current liabilities | Rs 109,705,859 | Rs 111,962,584 | −2.02% |
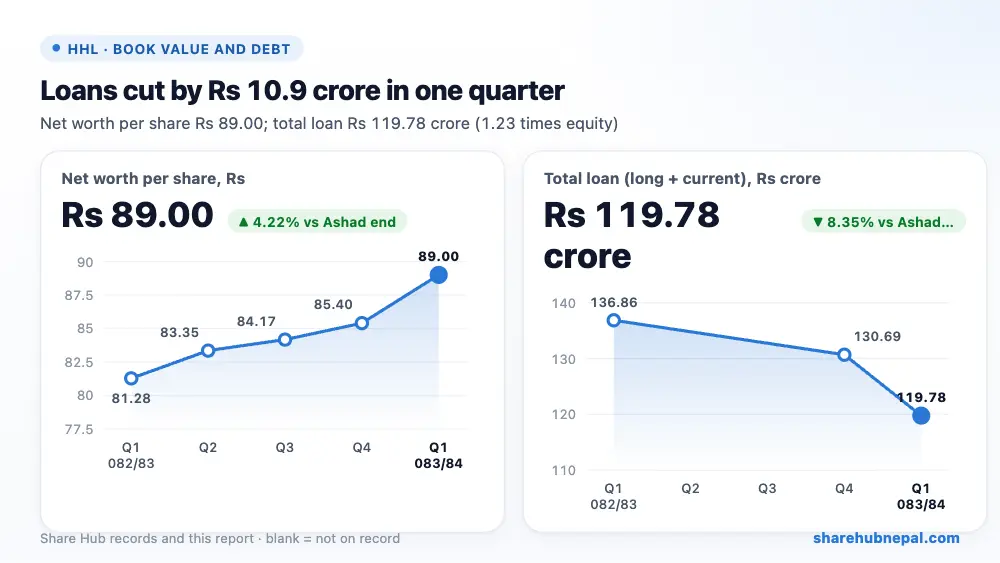
The company used cash to pay down debt: long-term loans fell by Rs 10.99 crore to Rs 1.10 arba and cash fell to Rs 1.95 crore from Rs 7.14 crore. Total loan is Rs 1.20 arba, 1.23 times equity. The liquidity ratio is just under 1 (0.98), so it has little spare cash. Equity rose 4.22% to Rs 97.46 crore, but retained earnings are still a negative Rs 12.04 crore. The planned 1:1 right issue would roughly double paid-up capital and cut debt further, but it would also double the number of shares.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 14.41 |
| Net worth per share | Rs 89.00 |
| Market price (Ashwin end) | Rs 351 |
| P/E (annualised) | 24.36x |
| P/B | 3.94x |
At the Ashwin-end price of Rs 351, the share trades at 24.36 times annualised EPS and 3.94 times net worth per share. The report prints a P/E of 97.48 on the quarter EPS; on last year's full-year EPS of Rs 7.33 it is about 48 times. The share also trades at about 3.9 times a net worth below Rs 100.
Conclusion
Positives: profit up 8.54%, finance cost down 22.56%, Rs 10.99 crore of loans repaid in the quarter, net worth rising, and no legal cases.
Watch: electricity sales fell 8.19%, the report mislabels quarter EPS as annual, liquidity is below 1, accumulated losses remain, profit is seasonal, and the right issue will double the share count.
Watch why sales fell, the right issue approval and timing, and dry-season profit.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

