













Kalanga Hydro Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
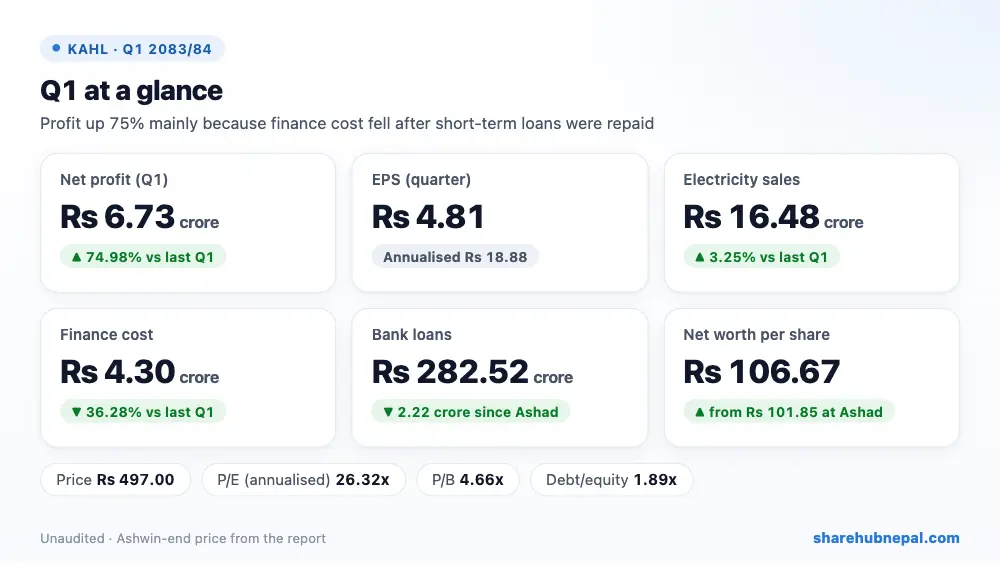
Kalanga Hydro earned a net profit of Rs 6.73 crore in the first quarter, up 74.98% from Rs 3.85 crore in the same quarter last year. EPS for the quarter is Rs 4.81 (annualised Rs 18.88).
Electricity sales grew only 3.25% to Rs 16.48 crore. The big gain came from finance cost, which fell 36.28% to Rs 4.30 crore: a year ago the company had Rs 95.95 crore of short-term secured loans; share capital has since risen from Rs 91 crore to Rs 140 crore and short-term loans are down to Rs 4.80 crore.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Electricity sales | Rs 164,785,745 | Rs 159,601,874 | +3.25% |
| Gross profit | Rs 116,908,517 | Rs 112,680,844 | +3.75% |
| Finance cost | Rs 43,047,855 | Rs 67,553,096 | −36.28% |
| Net profit | Rs 67,349,485 | Rs 38,489,048 | +74.98% |
| EPS (quarter) | 4.81 | 4.23 | – |
| EPS (annualised) | 18.88 | 16.60 | – |
1. Where the profit came from
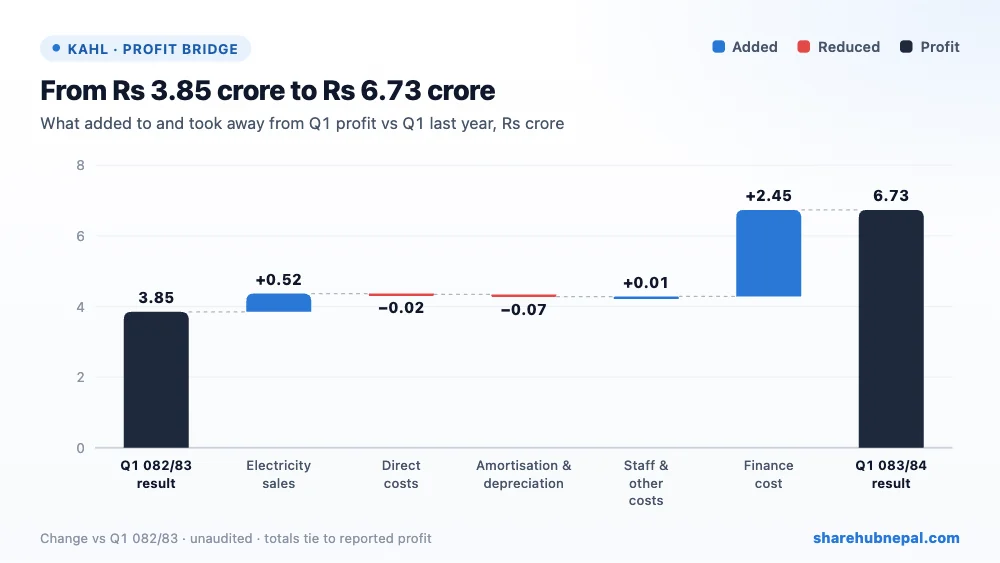
Compared with last year’s Q1, lower finance cost added Rs 2.45 crore and higher sales Rs 51.84 lakh. Amortisation, depreciation and direct costs rose slightly (together about Rs 9.05 lakh), while staff and other costs were a little lower. The report shows no income tax charge.
2. Profit through the year
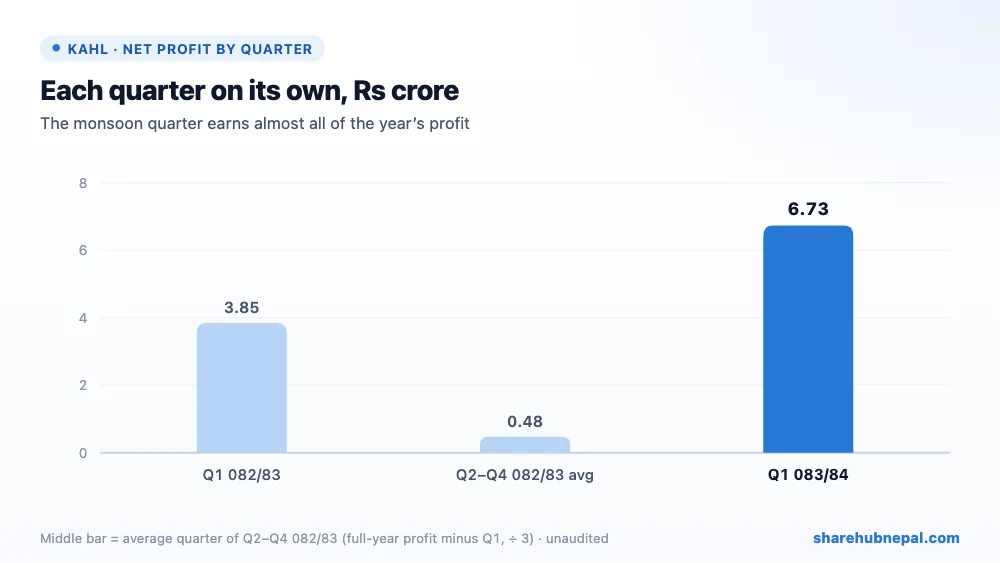
Share Hub’s Q1 2082/83 record for Kalanga was added in this update from this report’s comparison column. The full-year 2082/83 profit was Rs 5.28 crore, so after Rs 3.85 crore in Q1 the other three quarters earned only Rs 1.43 crore together (about Rs 47.54 lakh a quarter). Q1 is the monsoon peak, so annualising it overstates the year: last year’s annualised Q1 EPS was Rs 16.60 against a full-year EPS of Rs 3.77.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Bank loan, long term | Rs 2,777,213,726 | Rs 2,777,213,726 | +0.00% |
| Bank loan, due within a year | Rs 48,005,966 | Rs 70,223,546 | −31.64% |
| Property, plant and equipment | Rs 4,026,806,005 | Rs 4,064,028,888 | −0.92% |
| Cash and bank balance | Rs 135,163,309 | Rs 81,158,284 | +66.54% |
| Total assets | Rs 4,326,102,389 | Rs 4,282,993,224 | +1.01% |
| Total equity | Rs 1,493,311,259 | Rs 1,425,961,773 | +4.72% |
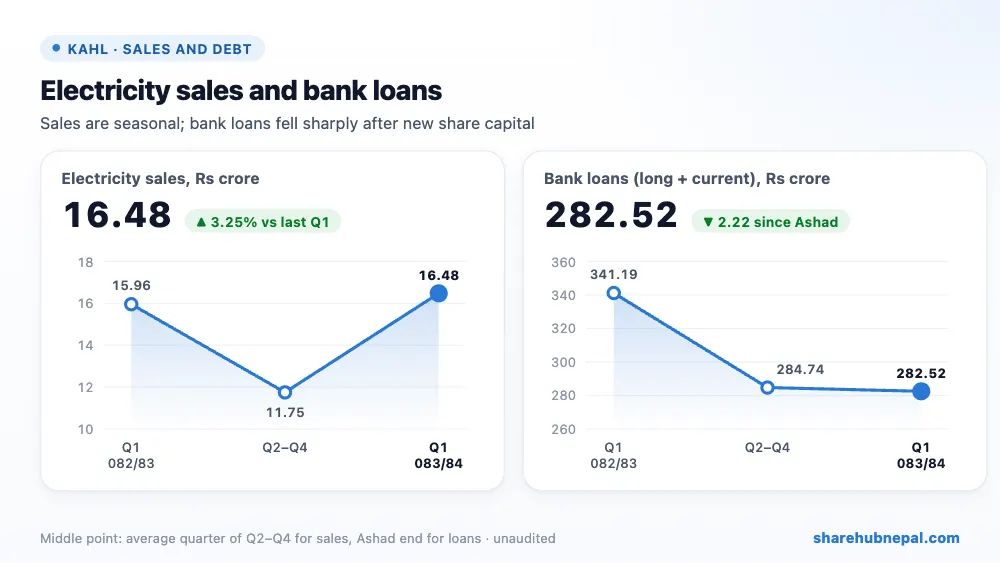
In the quarter the company cut its short-term secured loan from Rs 7.02 crore to Rs 4.80 crore; the long-term loan stayed at Rs 277.72 crore. Total bank loans of Rs 282.52 crore are 1.89 times equity (2.00 at Ashad end, 3.65 a year ago). Cash rose to Rs 13.52 crore and current assets are 5.39 times current liabilities, so short-term liquidity is comfortable.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 18.88 |
| Net worth per share | Rs 106.67 |
| Closing price, Ashwin end | Rs 497.00 |
| P/E on annualised EPS | 26.32x |
| P/E on FY 2082/83 EPS (3.77) | 131.83x |
| P/B | 4.66x |
| Liquidity ratio | 5.39 |
At Rs 497 the share trades at 26.32 times annualised EPS and 4.66 times net worth per share (Rs 106.67). The report’s own P/E of 103.31 uses the quarter’s EPS, and on last year’s full-year EPS (Rs 3.77) the P/E is about 132 times. The price assumes much stronger full-year earnings than last year’s.
Conclusion
Positives: profit up 74.98%, finance cost down 36.28%, short-term loans almost cleared, a strong cash position and liquidity ratio of 5.39, and a stronger equity base after new shares.
Watch: flat electricity sales (+3.25%), strong seasonality, a very high price compared with full-year earnings, and Rs 277.72 crore of long-term debt.
Kalanga Hydro’s lower interest bill lifted its monsoon-quarter profit, and its balance sheet is healthier than a year ago. Whether the full year improves on last year’s Rs 3.77 EPS depends on dry-season output.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

