













Kutheli Bukhari Small Hydropower Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
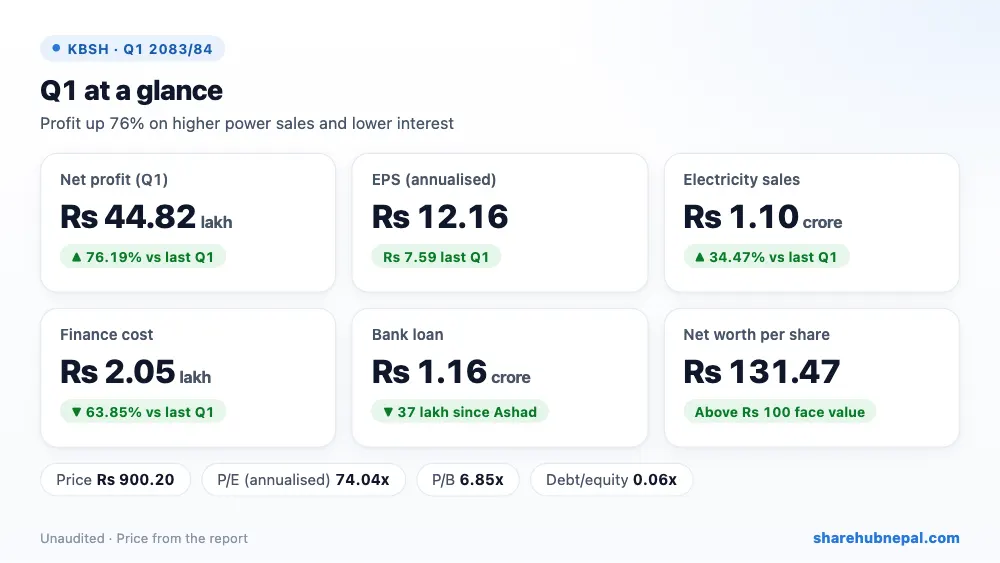
Summary
Kutheli Bukhari Small Hydropower earned a net profit of Rs 44.82 lakh in the first quarter, up 76.19% from Rs 25.44 lakh a year ago. Annualised EPS is Rs 12.16.
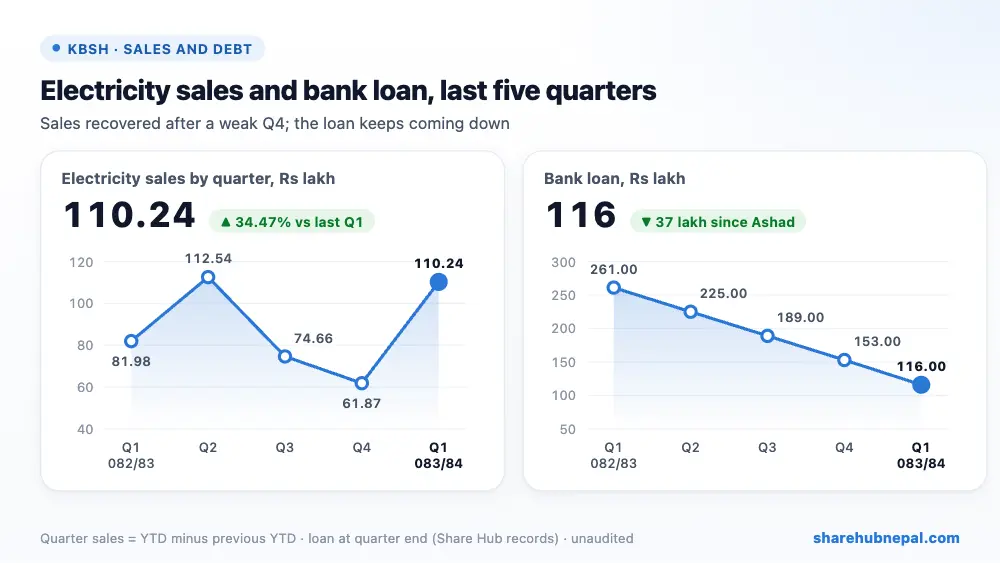
Electricity sales rose 34.47% to Rs 1.10 crore and finance cost fell 63.85% to Rs 2.05 lakh as the bank loan was paid down. Administrative expenses rose 34.42%, and tax rose to Rs 6.10 lakh: the project's 10-year income-tax holiday ended in Asoj 2082, and it now pays tax at half the normal rate.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Electricity sales | Rs 11,023,675 | Rs 8,198,052 | +34.47% |
| Administrative expenses | Rs 2,339,638 | Rs 1,740,487 | +34.42% |
| Finance cost | Rs 205,204 | Rs 567,579 | −63.85% |
| Profit before bonus and tax | Rs 5,196,488 | Rs 2,752,279 | +88.81% |
| Net profit | Rs 4,482,286 | Rs 2,544,043 | +76.19% |
| EPS (annualised) | 12.16 | 7.59 | – |
1. Where the profit came from
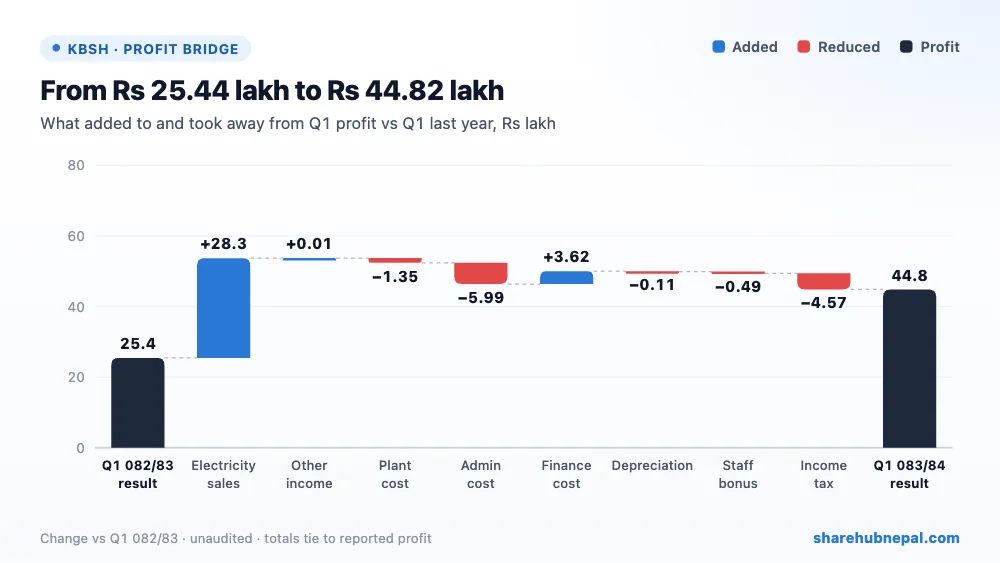
Compared with last year's Q1, higher electricity sales added Rs 28.26 lakh and lower finance cost Rs 3.62 lakh. Higher tax took away Rs 4.57 lakh, higher administrative expenses Rs 5.99 lakh, higher plant costs Rs 1.35 lakh and a larger staff bonus Rs 48,884.
2. Profit through the year
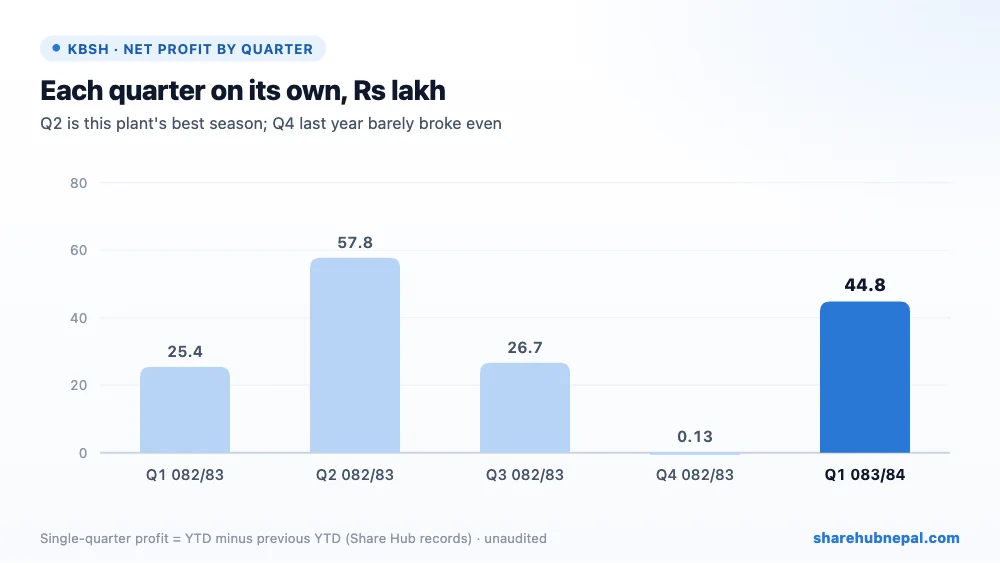
Based on Share Hub's records, single-quarter profits in 2082/83 were Rs 25.44 lakh in Q1, Rs 57.76 lakh in Q2, Rs 26.67 lakh in Q3 and only Rs 12,555 in Q4. This Q1 is well ahead of last year's Q1 but below the Q2 peak.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Long-term borrowings | Rs 0 | Rs 15,300,000 | −100.00% |
| Short-term borrowings | Rs 11,600,000 | Rs 0 | – |
| Intangible (project) assets | Rs 182,928,207 | Rs 186,497,391 | −1.91% |
| Cash and cash equivalents | Rs 3,631,467 | Rs 2,807,641 | +29.34% |
| Total assets | Rs 206,302,088 | Rs 208,824,289 | −1.21% |
| Total equity | Rs 193,861,223 | Rs 192,007,050 | +0.97% |
The Rs 1.53 crore long-term loan at Ashad end is gone; the company now has a Rs 1.16 crore short-term loan, so total bank debt fell Rs 37 lakh in the quarter. Debt is only 0.06 times equity. Because the loan is now short-term, the current ratio is just 1.08. Equity rose to Rs 19.39 crore and net worth per share is Rs 131.47.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 12.16 |
| Net worth per share | Rs 131.47 |
| Total assets per share | Rs 139.90 |
| Market price (report) | Rs 900.20 |
| P/E (as reported) | 74.04x |
| P/B | 6.85x |
| Current ratio | 1.08 |
At Rs 900.20 the share trades at 74.04 times annualised EPS and 6.85 times net worth per share. That is expensive for a small plant: last year's full-year EPS was Rs 7.46, a P/E of about 120.67 at today's price.
Conclusion
Positives: profit up 76.19%, sales up 34.47%, finance cost down 63.85%, very low debt, and net worth above face value.
Watch: the end of the full tax holiday (tax now at half rate), higher administrative costs, a weak Q4 last year, a short-term loan that lowers the current ratio, and a very high P/E.
Kutheli Bukhari had a good start to the year with more sales and almost no interest burden. Higher tax from now on and a high share price relative to earnings are the main things to keep in mind.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

