













Liberty Energy Company Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
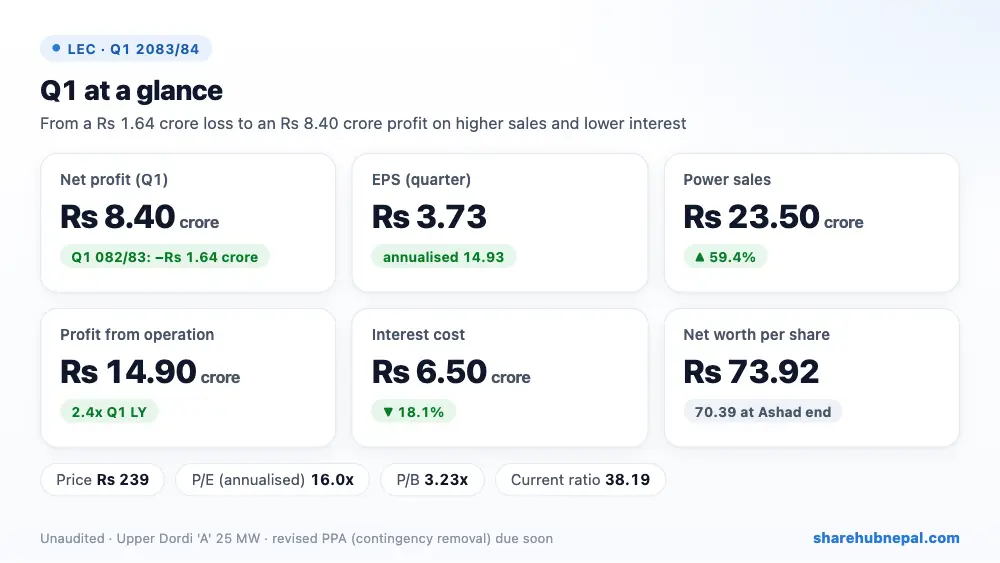
Summary
Liberty Energy earned a net profit of Rs 8.40 crore in the first quarter of 2083/84, against a loss of Rs 1.64 crore in the same quarter last year. Quarter EPS is Rs 3.73 (about Rs 14.93 annualised) and net worth per share rose to Rs 73.92.
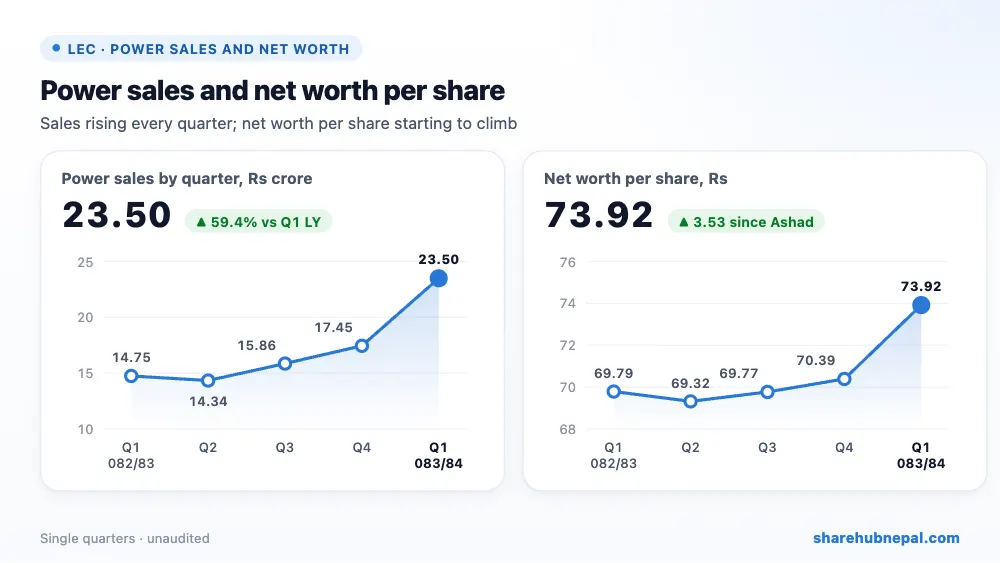
Revenue from its 25 MW Upper Dordi 'A' plant in Lamjung rose 59.39% to Rs 23.50 crore; the plant ran continuously through the quarter. Profit from operation more than doubled to Rs 14.90 crore, and finance cost fell 18.09% to Rs 6.50 crore. The Electricity Regulatory Commission has approved the PPA change that removes the 'contingency' clause, and a revised PPA with NEA is due to be signed within days.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from electricity generation | Rs 235,047,017 | Rs 147,468,266 | +59.39% |
| Generation and distribution expenses | Rs 21,517,824 | Rs 17,029,569 | +26.36% |
| Depreciation and amortisation | Rs 58,418,834 | Rs 60,445,942 | −3.35% |
| Administrative and other expenses | Rs 6,139,906 | Rs 7,115,042 | −13.71% |
| Profit from operation | Rs 149,000,024 | Rs 62,961,041 | +136.65% |
| Finance costs | Rs 64,997,370 | Rs 79,350,660 | −18.09% |
| Net profit (loss) | Rs 84,002,654 | −Rs 16,389,620 | Turned to profit |
1. Where the profit came from
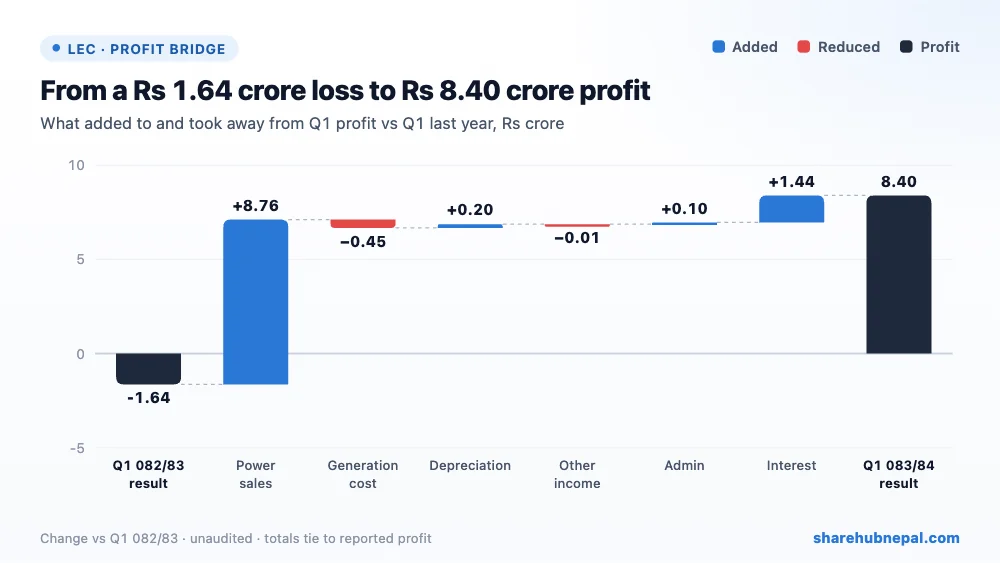
Against Q1 last year, higher power sales added Rs 8.76 crore, lower interest Rs 1.44 crore, lower depreciation Rs 20.27 lakh and lower admin cost Rs 9.75 lakh. Higher generation cost took away Rs 44.88 lakh. Net: a swing of Rs 10.04 crore.
2. Profit through the year
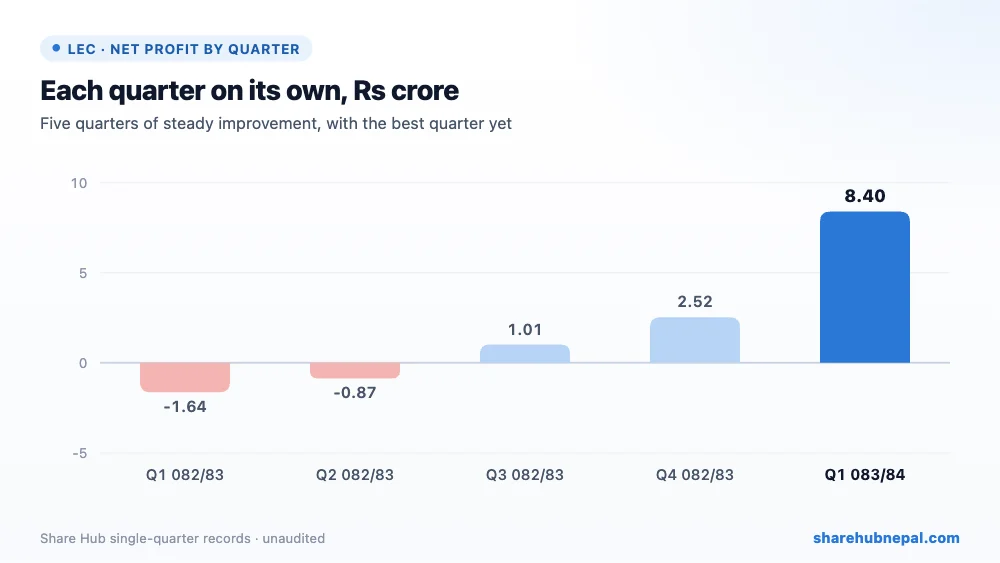
LEC's results have improved every quarter: a loss of Rs 1.64 crore in Q1 2082/83, a smaller loss of Rs 87.37 lakh in Q2, then profits of Rs 1.01 crore in Q3 and Rs 2.52 crore in Q4, and now Rs 8.40 crore. The whole of 2082/83 made only about Rs 1.02 crore. Q1 is the high-flow season, so the annualised EPS of 14.93 overstates the year, but the trend is clearly upward.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Intangible (project) assets | Rs 5,430,886,266 | Rs 5,491,589,481 | −1.11% |
| Other investments | Rs 175,529,000 | Rs 170,409,000 | +3.00% |
| Trade and other receivables | Rs 164,252,925 | Rs 128,421,560 | +27.90% |
| Cash and cash equivalents | Rs 128,615,645 | Rs 61,651,946 | +108.62% |
| Long-term borrowing | Rs 4,328,934,171 | Rs 4,363,508,413 | −0.79% |
| Total equity | Rs 1,663,277,551 | Rs 1,583,874,197 | +5.01% |
Debt is heavy: long-term borrowing of Rs 4.33 arba is 2.60 times equity, against project assets of Rs 5.43 arba. A year ago the company also had an Rs 87 crore short-term loan; there is no short-term loan now, and liquidity is very strong (cash Rs 12.86 crore, current ratio 38.19). Accumulated losses (Rs 66.05 crore) keep net worth per share below Rs 100. Through subsidiaries the company holds licences for Badigad Khola (24.60 MW, Baglung) and Lodo Khola (1.60 MW, Lamjung).
4. Per-share figures and valuation
| Indicator | Value |
| EPS (quarter, report) | Rs 3.73 |
| EPS (annualised, derived) | Rs 14.93 |
| Net worth per share | Rs 73.92 |
| Market price (Q1 close) | Rs 239 |
| P/E (report) | 61.87x |
| P/E (annualised EPS) | 16.01x |
| P/B | 3.23x |
| Current ratio | 38.19 |
| Debt to equity | 2.60x |
The Q1 closing price was Rs 239 (range Rs 208 to Rs 260). The report prints a P/E of 61.87 on the quarter EPS; on the annualised EPS it is 16.0 times. The price is 3.23 times net worth per share.
Conclusion
Positives: a turn from loss to a strong profit, sales up 59%, interest down 18%, very strong liquidity, and a revised PPA without the contingency clause about to be signed.
Watch: heavy long-term debt, accumulated losses (net worth below face value), NEA forced outages and the transmission network, flood and low-water risk, and an unexplained Rs 46 lakh gap between profit and the rise in equity.
LEC's recovery is real: sales are up, interest is down and the PPA is about to improve. The next quarters will show whether profits hold in the dry season and start to erase the accumulated losses.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

