













Mabilung Energy Ltd – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
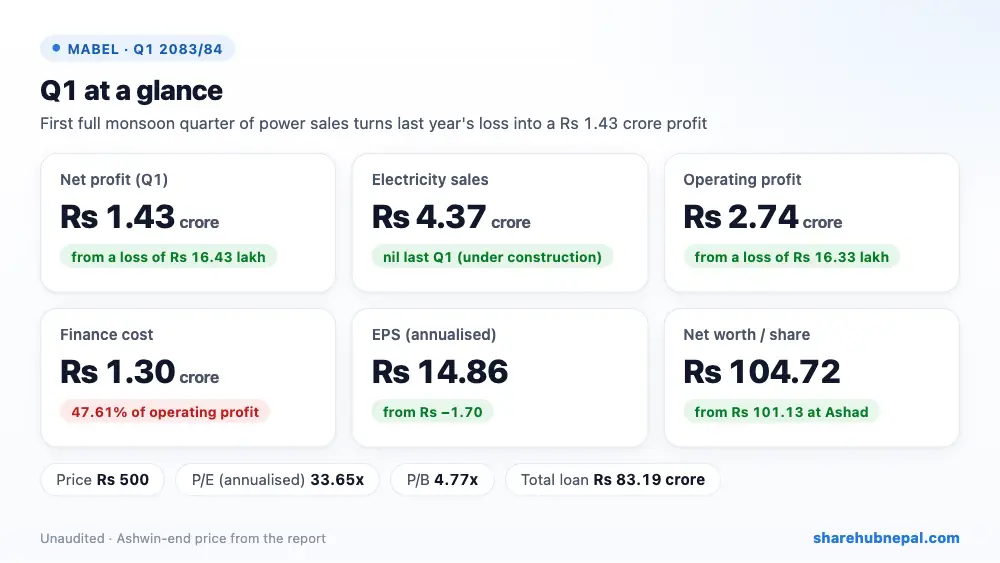
Mabilung Energy earned a net profit of Rs 1.43 crore in the first quarter of FY 2083/84, against a loss of Rs 16.43 lakh a year ago. The change is simple: a year ago the Upper Piluwa Khola 3 project was still under construction, and this is its first full monsoon quarter of selling power (COD was 2082/06/04). Electricity sales were Rs 4.37 crore, already more than half of the whole of last year's sales (Rs 8.45 crore). After direct costs, project amortisation and admin, operating profit was Rs 2.74 crore, and finance cost of Rs 1.30 crore took almost half of it. Annualised EPS is Rs 14.86 and net worth per share is Rs 104.72.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Electricity sales | Rs 43,672,172 | Rs 0 | – |
| Direct expenses | Rs 2,349,987 | Rs 0 | – |
| Construction margin + other income (IFRIC-12) | Rs 0 | Rs 448,141 | −100.00% |
| Administrative expenses | Rs 3,731,881 | Rs 2,081,043 | +79.33% |
| Amortisation + depreciation | Rs 10,232,952 | Rs 0 | – |
| Operating profit | Rs 27,357,352 | −Rs 1,632,902 | Turned to profit |
| Finance cost | Rs 13,026,084 | Rs 10,288 | Interest now expensed (was capitalised) |
| Income tax | Rs 0 | Rs 0 | – |
| Net profit | Rs 14,331,268 | −Rs 1,643,190 | Turned to profit |
| EPS (annualised) | 14.86 | -1.7 | – |
| Net worth per share | 104.72 | 103.05 | – |
1. Where the profit came from
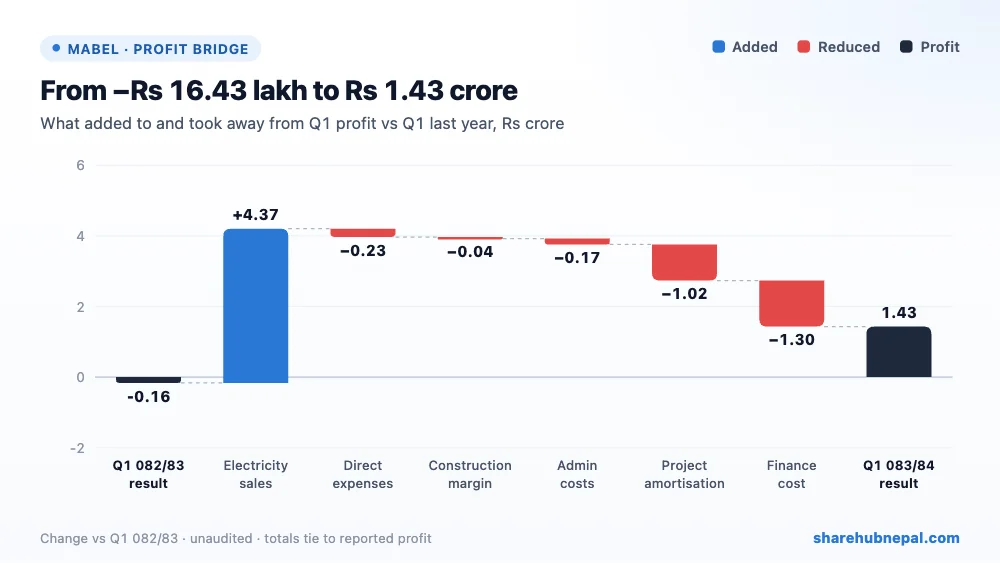
Electricity sales of Rs 4.37 crore came in against nil a year ago. Direct plant expenses were Rs 23.50 lakh and amortisation of the project cost Rs 1.02 crore, so gross profit was Rs 3.11 crore. Administrative expenses rose to Rs 37.32 lakh (Rs 20.81 lakh), and operating profit reached Rs 2.74 crore against an operating loss of Rs 16.33 lakh. Finance cost jumped to Rs 1.30 crore from Rs 10,288, because interest that was capitalised during construction now goes through profit. Last year's Rs 4.48 lakh IFRIC-12 construction margin is gone. No tax is charged. Net profit improved by Rs 1.60 crore.
2. Profit through the year
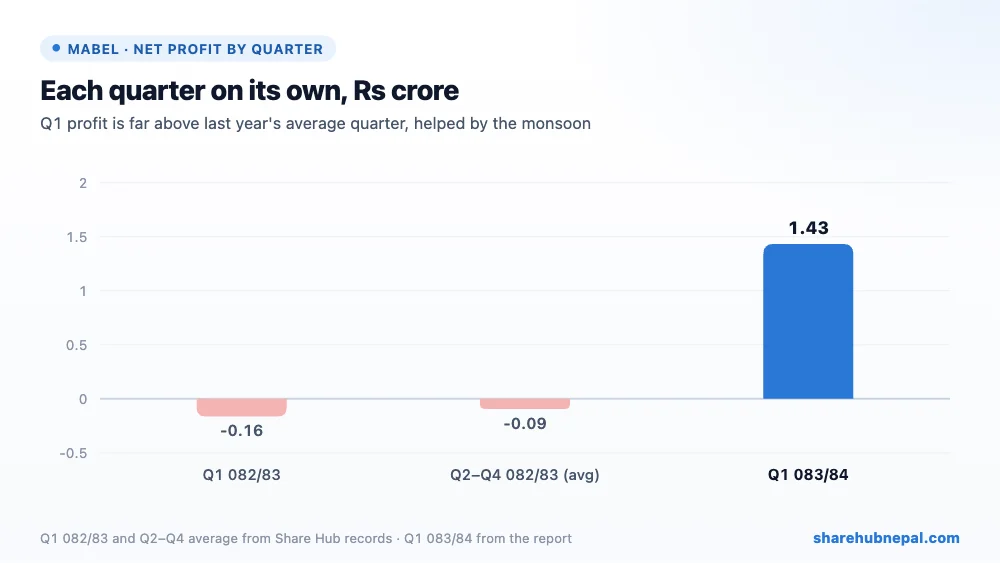
Profit by quarter (Share Hub records): Q1 082/83: −Rs 16.43 lakh, Q2–Q4 082/83 (avg): −Rs 9.47 lakh, Q1 083/84: Rs 1.43 crore. Last year the company was in its first months of operation and ended FY 2082/83 with a loss (EPS Rs −1.16). Q1 is the peak monsoon quarter for a run-of-river plant, so the dry-season quarters (Poush to Chaitra) will earn much less; do not expect four quarters like this one.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 1,246,096,318 | Rs 1,244,480,586 | +0.13% |
| Total equity | Rs 404,019,534 | Rs 390,178,343 | +3.55% |
| Long-term borrowings | Rs 782,130,000 | Rs 768,570,000 | +1.76% |
| Short-term borrowings | Rs 49,772,704 | Rs 73,398,565 | −32.19% |
| Trade receivables | Rs 30,557,792 | Rs 20,999,576 | +45.52% |
| Cash and equivalents | Rs 509,724 | Rs 488,554 | +4.33% |
| Current assets | Rs 92,868,330 | Rs 81,019,646 | +14.62% |
| Current liabilities | Rs 59,946,784 | Rs 85,732,243 | −30.08% |
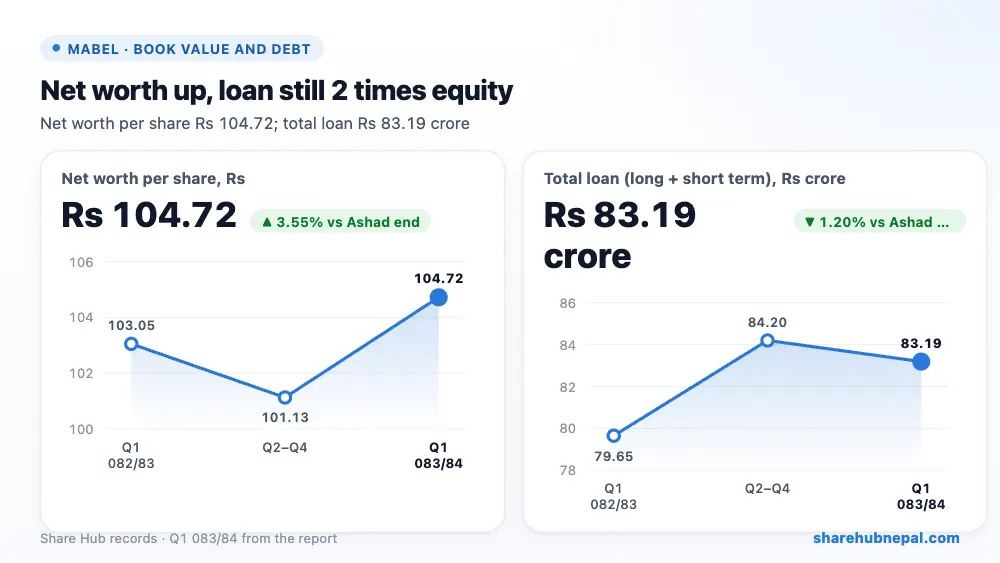
Debt is the main thing to watch. Long-term borrowings rose to Rs 78.21 crore (Rs 76.86 crore at Ashad end) while short-term borrowings fell to Rs 4.98 crore (Rs 7.34 crore), so the total loan is Rs 83.19 crore, about 2.06 times equity. Cash is only Rs 5.10 lakh, but trade receivables (Rs 3.06 crore) and other financial assets (Rs 5.86 crore) lift the current ratio to 1.55. Equity rose 3.55% to Rs 40.40 crore. The project asset (Rs 1.15 arba) is being amortised by about Rs 1.02 crore a quarter.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 14.86 |
| Net worth per share | Rs 104.72 |
| Market price (Ashwin end) | Rs 500 |
| P/E (annualised) | 33.65x |
| P/B | 4.77x |
At the Ashwin-end price of Rs 500, the share trades at 33.65 times annualised EPS and 4.77 times net worth per share. This P/E is based on the best (monsoon) quarter. Last year's full-year EPS was negative, so the market price already assumes the plant will keep earning well through the dry season too.
Conclusion
Positives: the plant is now running and selling power, Q1 profit of Rs 1.43 crore against a loss, operating profit of Rs 2.74 crore, short-term loans cut by Rs 2.36 crore, a current ratio of 1.55, and no legal cases.
Watch: profit is seasonal (monsoon quarter), debt is high at 2.06 times equity and finance cost eats almost half of operating profit, cash is very low, equity rose Rs 4.90 lakh less than the profit with no explanation, the Ashad figures in this report differ from Share Hub's Q4 record, and the company warns of flood and landslide risk because the plant depends on river flow.
Watch the Q2 and Q3 profit in the dry season, whether the company can keep cutting short-term loans, and how much of the profit is left after interest over a full year.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

