













Madhya Bhotekoshi Jalavidyut Company Ltd. – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
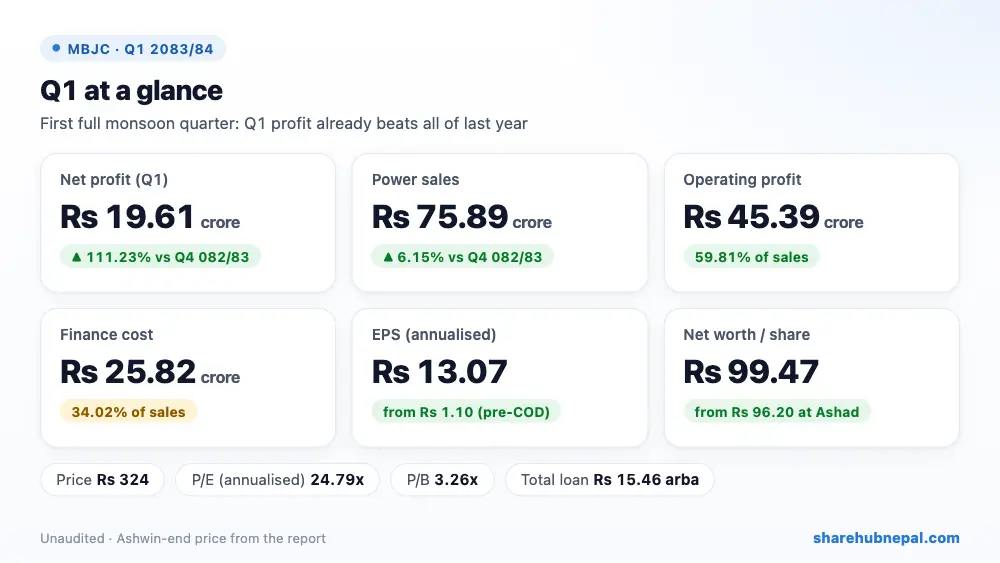
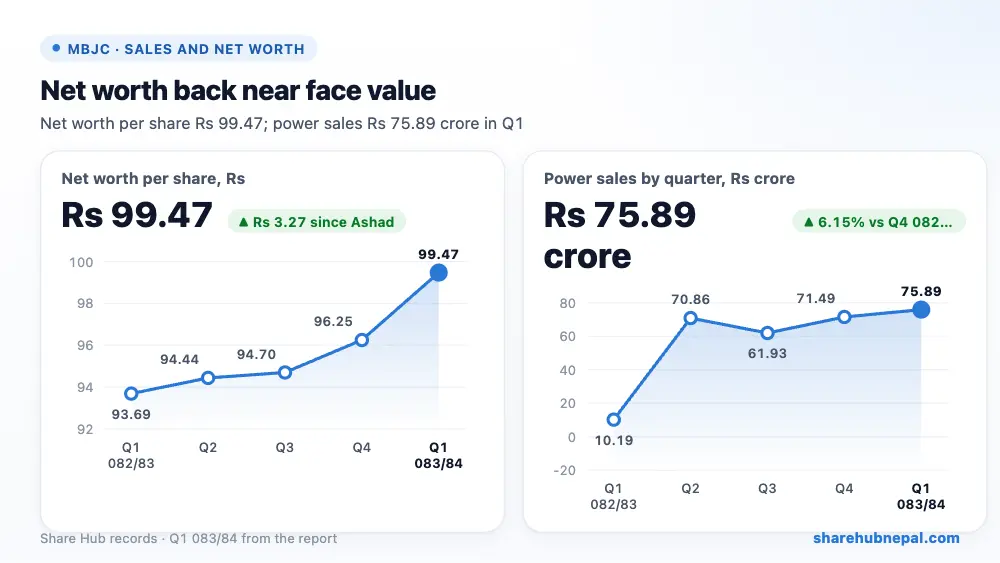
Madhya Bhotekoshi earned a net profit of Rs 19.61 crore in the first quarter of FY 2083/84. That is more than its whole profit for FY 2082/83 (Rs 16.69 crore) and more than double the Rs 9.28 crore of Q4 082/83. A year ago Q1 profit was only Rs 1.82 crore because the 102 MW plant started commercial operation on 20 Asoj 2082, near the end of that quarter, so the year-on-year jump (+977.83%) is not a fair comparison. Power sales were Rs 75.89 crore, 6.15% more than Q4. Depreciation (Rs 24.22 crore) and interest (Rs 25.82 crore) take two-thirds of sales. Annualised EPS is Rs 13.07 and net worth per share Rs 99.47.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sales | Rs 758,901,910 | Rs 101,850,910 | +645.11% |
| Cost of sales | Rs 52,443,840 | Rs 4,387,100 | +1095.41% |
| Other income | Rs 365,280 | Rs 360,610 | +1.30% |
| Operating profit | Rs 453,901,110 | Rs 60,339,610 | +652.24% |
| Finance cost | Rs 258,159,740 | Rs 42,505,570 | +507.36% |
| Income tax | Rs 0 | Rs 0 | – |
| Net profit | Rs 196,106,660 | Rs 18,194,650 | +977.83% |
| EPS (annualised) | 13.07 | 1.1 | – |
| Net worth per share | 99.47 | 93.69 | – |
1. Where the profit came from
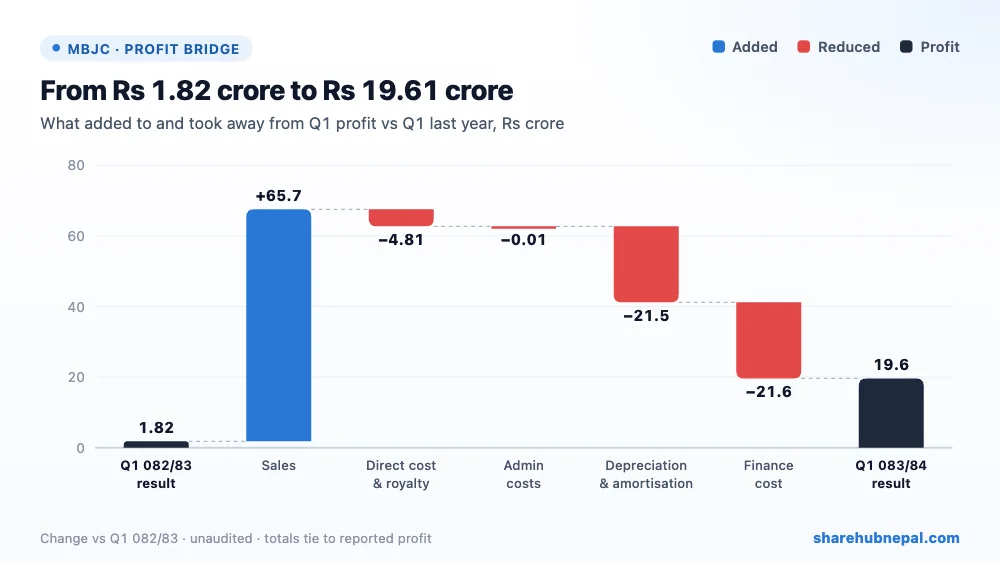
Compared with last year's Q1 (before full operation), power sales added Rs 65.71 crore. Most of that went into costs that start once a plant runs: depreciation rose Rs 21.53 crore, finance cost Rs 21.57 crore (interest is no longer capitalised) and direct cost and royalty Rs 4.81 crore. Staff and admin costs hardly changed. No tax was charged (the company is in its tax holiday).
2. Profit through the year
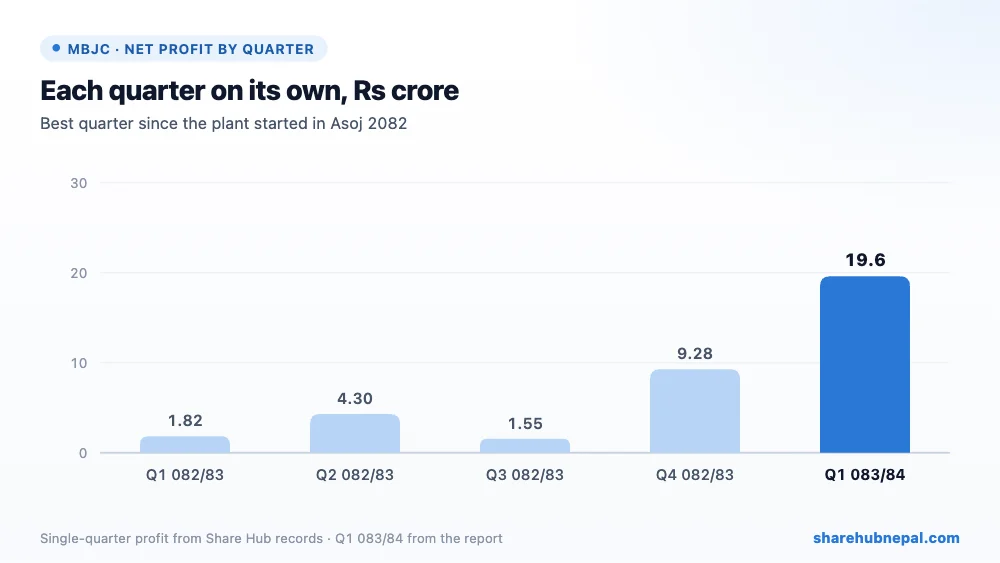
Profit by quarter (Share Hub records): Q1 082/83: Rs 1.82 crore, Q2 082/83: Rs 4.30 crore, Q3 082/83: Rs 1.55 crore, Q4 082/83: Rs 9.28 crore, Q1 083/84: Rs 19.61 crore. Share Hub quarter figures are worked out from year-to-date records (Q1 082/83 uses the report's Rs 1.82 crore). Q1 is the monsoon peak, so later quarters should be lower; the plant's power is now sent through the new Barhabise substation (from 17 Kartik 2083), which removes the earlier evacuation limits on the New Khimti route.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 21,996,204,570 | Rs 22,221,943,760 | −1.02% |
| Total equity | Rs 5,968,154,290 | Rs 5,772,047,640 | +3.40% |
| Long-term borrowings | Rs 15,157,005,170 | Rs 15,429,602,670 | −1.77% |
| Current borrowings | Rs 300,000,000 | Rs 440,000,000 | −31.82% |
| Cash and equivalents | Rs 26,193,130 | Rs 11,100,870 | +135.96% |
Total assets are Rs 22.00 arba, almost all the plant (Rs 21.35 arba). Equity rose by exactly the quarter's profit to Rs 5.97 arba (Rs 99.47 per share); the accumulated loss shrank from Rs 22.80 crore to Rs 3.18 crore, so net worth is close to the Rs 100 face value again. The loan from the employees provident fund is Rs 15.16 arba (Rs 15.43 arba at Ashad end); four instalments totalling Rs 2.17 arba have been repaid and the rate is now 6.35% (from 7.50%). Short-term borrowing fell to Rs 30 crore. Cash is only Rs 2.62 crore and the liquidity ratio is 0.73, so day-to-day cash is tight.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 13.07 |
| Net worth per share | Rs 99.47 |
| Market price (Ashwin end) | Rs 324 |
| P/E (annualised) | 24.79x |
| P/B | 3.26x |
At the Ashwin-end price of Rs 324, the share trades at 24.79 times annualised EPS and 3.26 times net worth per share. Q1 is the best quarter of the year, so the annualised P/E looks cheaper than it is; on FY 2082/83 EPS of Rs 2.78 the P/E would be over 100 times, but last year was only a part year of operation.
Conclusion
Positives: first full monsoon quarter with Rs 19.61 crore profit (more than all of last year), sales up 6.15% on Q4, accumulated loss nearly wiped out, loan rate cut to 6.35%, loan being repaid, Barhabise substation now in use, tax holiday.
Watch: Rs 15.46 arba of debt, depreciation and interest take two-thirds of sales, cash only Rs 2.62 crore and liquidity ratio 0.73, dry-season flow drops, new-plant technical faults, Take-or-Pay arrangement with NEA not yet in place.
A strong first full monsoon quarter that already beats last year's profit; the dry-season quarters and steady loan repayment will decide the full-year result.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

