













Manakamana Engineering Hydropower Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
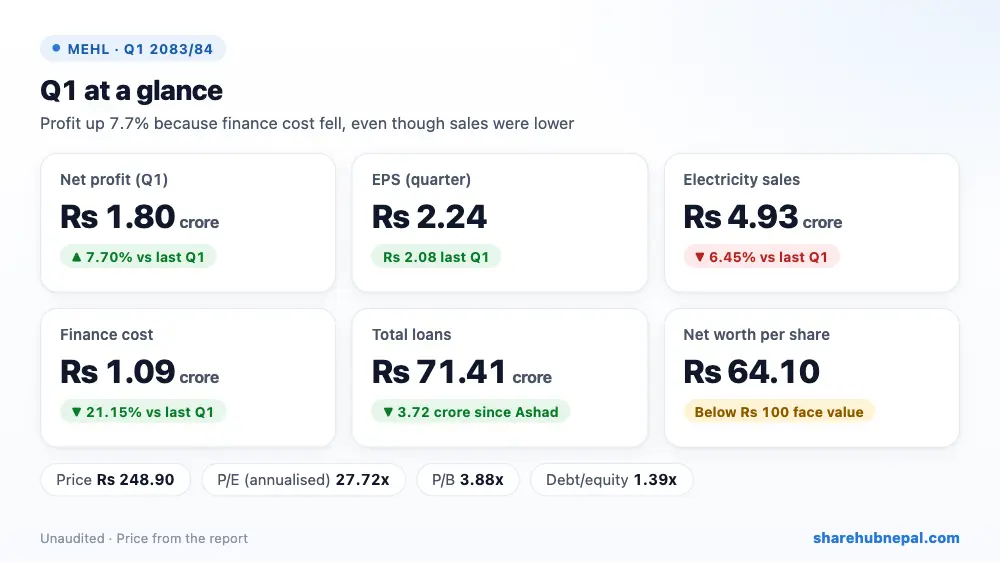
Manakamana Engineering Hydropower (Ghatte Khola project) earned a net profit of Rs 1.80 crore in the first quarter, up 7.70% from Rs 1.67 crore a year ago. EPS for the quarter is Rs 2.24.
Electricity sales actually fell 6.45% to Rs 4.93 crore. Profit still rose because finance cost fell 21.15% to Rs 1.09 crore and cost of sales fell 29.41%. Note: the report restates last year’s Q1 profit as Rs 1.67 crore (Share Hub had Rs 1.95 crore); Share Hub’s record has been updated to match.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Electricity sales | Rs 49,267,325 | Rs 52,665,412 | −6.45% |
| Gross profit | Rs 44,336,318 | Rs 45,680,110 | −2.94% |
| Profit before interest and tax | Rs 28,842,914 | Rs 30,480,895 | −5.37% |
| Finance cost | Rs 10,888,471 | Rs 13,809,703 | −21.15% |
| Net profit | Rs 17,954,443 | Rs 16,671,192 | +7.70% |
| EPS (quarter) | 2.24 | 2.08 | – |
1. Where the profit came from
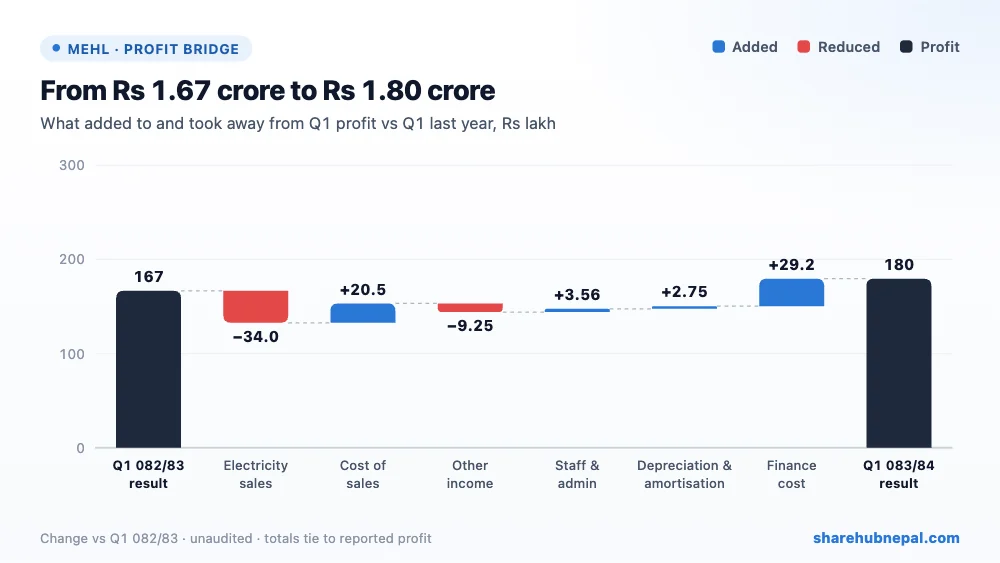
Compared with last year’s Q1, lower finance cost added Rs 29.21 lakh, lower cost of sales Rs 20.54 lakh, lower staff and admin costs Rs 3.56 lakh and lower depreciation Rs 2.75 lakh. Lower sales took away Rs 33.98 lakh and lower other income Rs 9.25 lakh.
2. Profit through the year
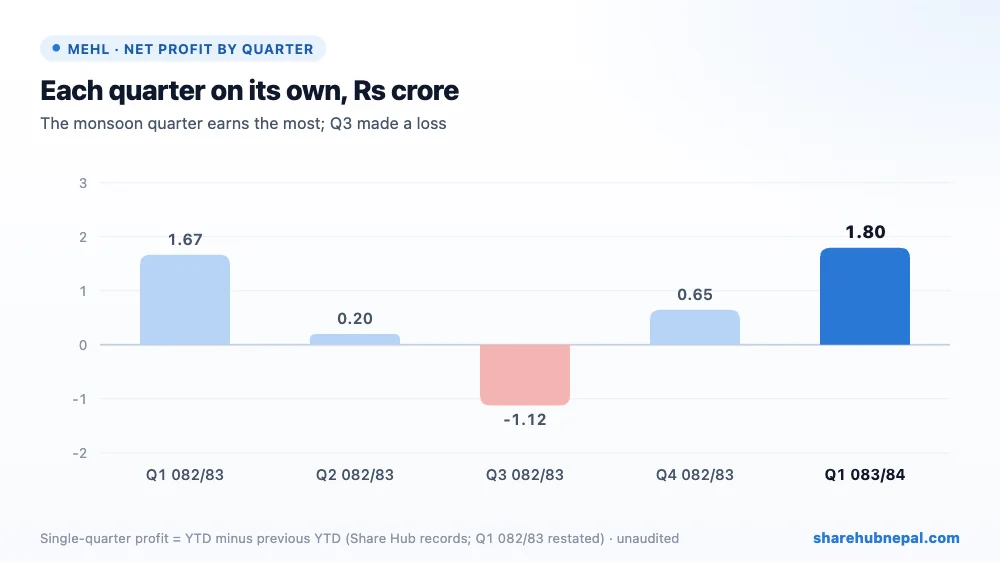
Based on Share Hub’s records (Q1 082/83 restated in this update), single-quarter profits in 2082/83 were Rs 1.67 crore in Q1, Rs 19.76 lakh in Q2, a loss of Rs 1.12 crore in Q3 and a profit of Rs 64.73 lakh in Q4. This report shows the full-year 2082/83 profit as Rs 1.08 crore, lower than the Rs 1.39 crore in the earlier Q4 report.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Long-term financial liabilities | Rs 714,111,819 | Rs 692,859,845 | +3.07% |
| Short-term financial liabilities | Rs 0 | Rs 58,443,850 | −100.00% |
| Intangible (project) assets | Rs 1,204,535,124 | Rs 1,216,921,709 | −1.02% |
| Cash and cash equivalents | Rs 11,454,162 | Rs 986,882 | +1060.64% |
| Total assets | Rs 1,265,465,529 | Rs 1,266,900,856 | −0.11% |
| Total equity | Rs 512,793,270 | Rs 494,838,826 | +3.63% |
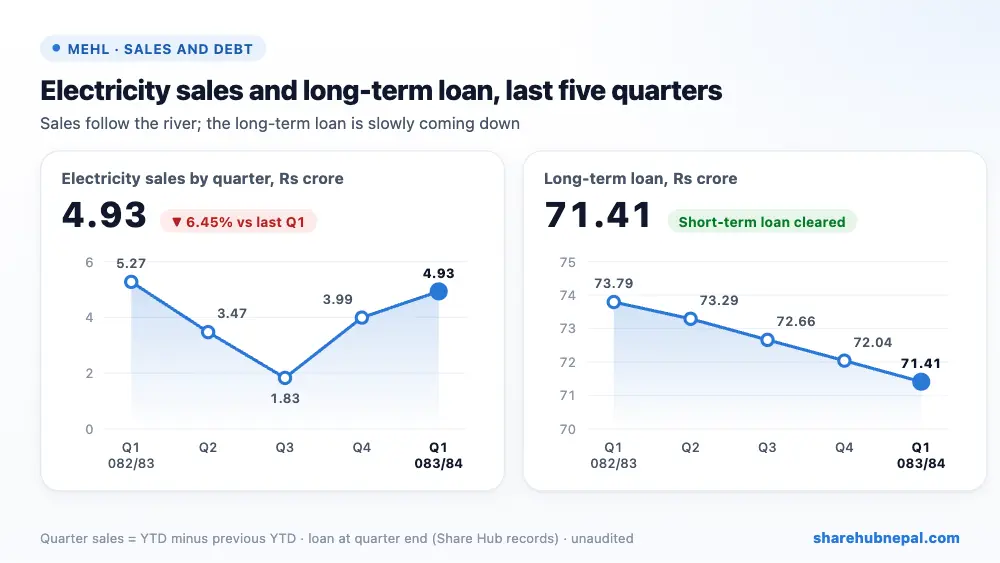
The Rs 5.84 crore short-term loan at Ashad end has been cleared, partly by moving it to long-term borrowing (up from Rs 69.29 crore to Rs 71.41 crore), so total loans fell Rs 3.72 crore. Debt is 1.39 times equity. Cash rose to Rs 1.15 crore and the current ratio improved to 1.56 from 0.62. Retained earnings still show an accumulated loss of Rs 28.72 crore, so net worth per share (Rs 64.10) is below the Rs 100 face value.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (quarter) | Rs 2.24 |
| EPS (annualised) | Rs 8.98 |
| Net worth per share | Rs 64.10 |
| Market price (report) | Rs 248.90 |
| P/E on annualised EPS | 27.72x |
| P/B | 3.88x |
| Current ratio | 1.56 |
At Rs 248.90 the share trades at 27.72 times annualised Q1 EPS and 3.88 times net worth per share. The report’s own P/E of 110.90 uses the quarter’s EPS. Last year’s full-year EPS was only Rs 1.34, so the price is high compared with what the company earns over a whole year.
Conclusion
Positives: profit up 7.70%, finance cost down 21.15%, short-term loan cleared, better liquidity (current ratio 1.56), and lower cost of sales.
Watch: electricity sales down 6.45%, a loss-making Q3 last year, an accumulated loss of Rs 28.72 crore, a revised (lower) 2082/83 profit, and a high price compared with full-year earnings.
Manakamana Engineering grew profit through lower interest costs rather than more power sales. Sales recovery and dry-season results will decide whether the full year improves on last year.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

