













Mountain Energy Nepal Ltd – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
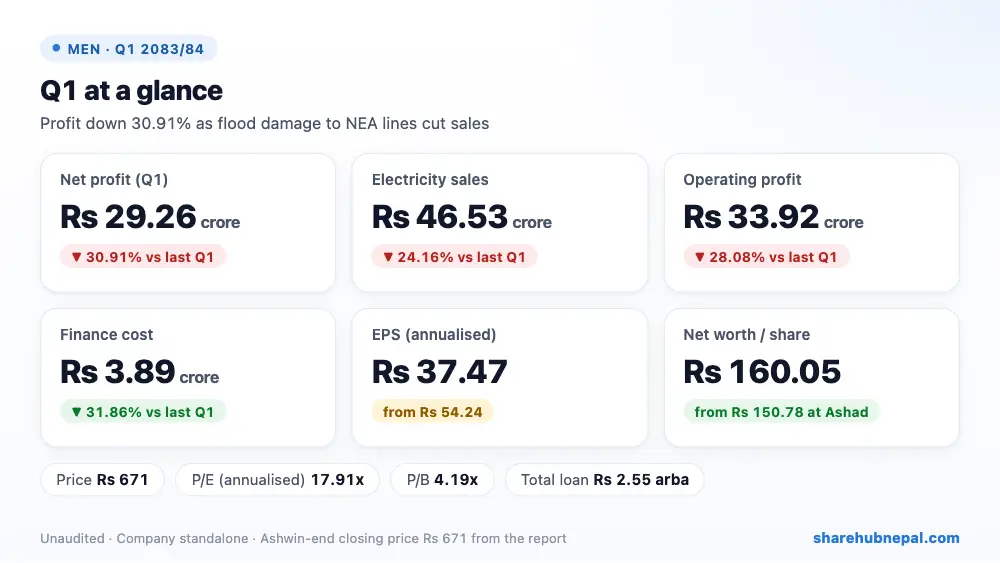
Mountain Energy Nepal earned a net profit of Rs 29.26 crore in the first quarter of FY 2083/84 (company figures), down 30.91% from Rs 42.35 crore a year ago. Electricity sales fell 24.16% to Rs 46.53 crore because floods damaged NEA transmission lines: Tadi Khola could sell only part of its power from Bhadra 10, and Mistri Khola sold nothing from Ashwin 11 to 31. Lower interest, tax and bonus costs softened the fall. Quarter EPS is Rs 9.37 (Rs 37.47 annualised) and net worth per share rose to Rs 160.05. The company also owns 67% of Dudh Khola Hydro Power, which is still at an early stage.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
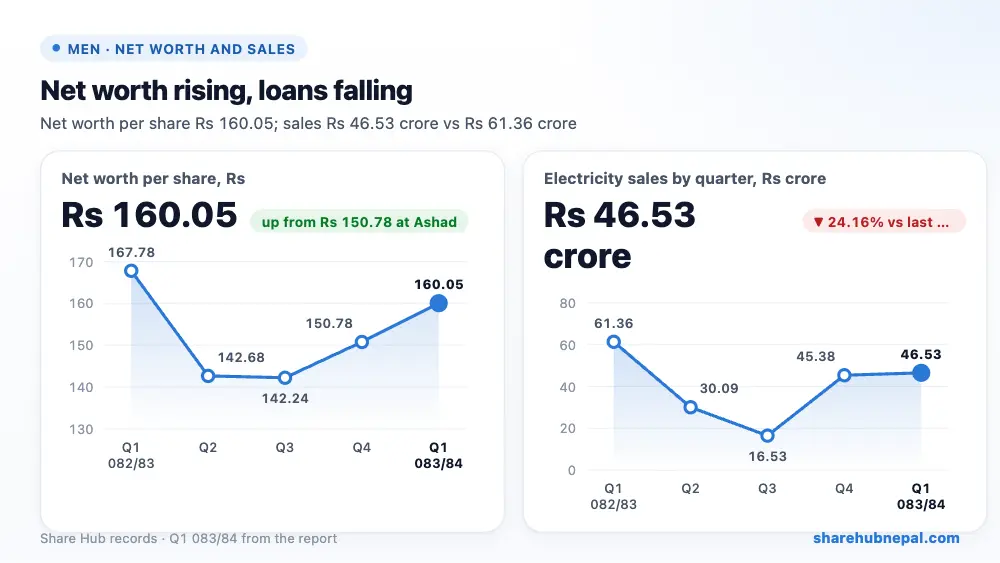
| Revenue from sales | Rs 465,319,622 | Rs 613,559,246 | −24.16% |
| Cost of sales | Rs 113,338,401 | Rs 130,247,712 | −12.98% |
| Other income | Rs 379 | Rs 29,916,173 | −100.00% |
| Operating profit | Rs 339,228,324 | Rs 471,648,142 | −28.08% |
| Finance cost | Rs 38,862,676 | Rs 57,036,109 | −31.86% |
| Income tax | Rs 1,754,431 | Rs 11,258,949 | −84.42% |
| Net profit | Rs 292,604,275 | Rs 423,496,693 | −30.91% |
| EPS (annualised) | 37.47 | 54.24 | – |
| Net worth per share | 160.05 | 167.78 | – |
1. Where the profit came from
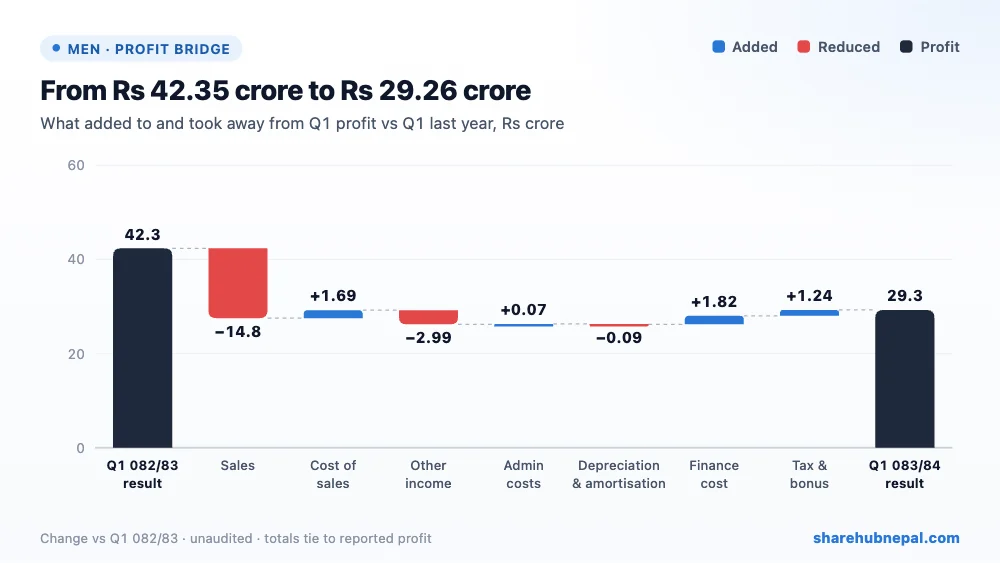
Sales fell by Rs 14.82 crore. Cost of sales fell by Rs 1.69 crore to Rs 11.33 crore, so gross profit came down to Rs 35.20 crore from Rs 48.42 crore. Operating profit fell 28.08% to Rs 33.92 crore. Another big drop came from finance income: Rs 2.99 crore last year (with an insurance claim of Rs 9 lakh), only Rs 379 this year. On the good side, interest cost fell 31.86% to Rs 3.89 crore as loans were repaid, and tax and staff bonus together fell to Rs 77.62 lakh from Rs 2.01 crore. Mistri Khola is tax-free till 2088, so tax stays small.
2. Profit through the year
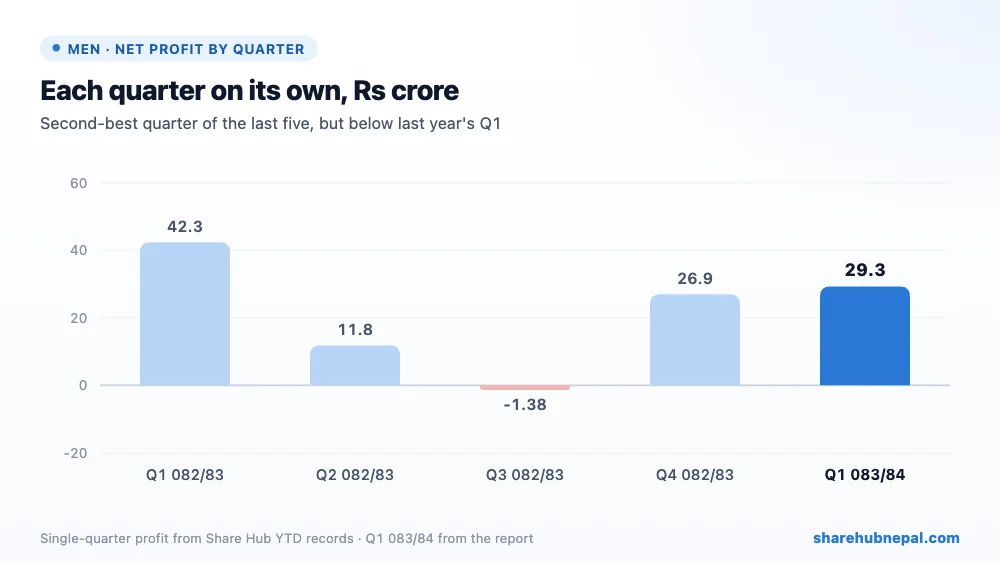
Profit by quarter (Share Hub records): Q1 082/83: Rs 42.35 crore, Q2 082/83: Rs 11.80 crore, Q3 082/83: −Rs 1.38 crore, Q4 082/83: Rs 26.94 crore, Q1 083/84: Rs 29.26 crore. Q1 is the monsoon peak, and this Q1 is still the second-best quarter of the last five. Last year the dry-season Q3 even showed a small loss. If the NEA lines are repaired soon, Q2 should recover some sales, but the lost days in Bhadra and Ashwin cannot be made up.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 7,680,270,736 | Rs 7,596,504,984 | +1.10% |
| Total equity | Rs 4,998,877,272 | Rs 4,709,199,040 | +6.15% |
| Long-term borrowings | Rs 1,998,171,119 | Rs 2,236,799,217 | −10.67% |
| Current borrowings | Rs 548,073,000 | Rs 521,511,000 | +5.09% |
| Cash and equivalents | Rs 372,149,079 | Rs 292,618,437 | +27.18% |
Total loans came down by Rs 21.21 crore in the quarter to Rs 2.55 arba (non-current Rs 2.00 arba, short-term Rs 54.81 crore), only 0.51 times equity. Equity rose to Rs 5.00 arba, almost equal to the Q1 profit. Cash rose to Rs 37.21 crore from Rs 29.26 crore, and current assets cover 2.97 times current liabilities. Receivables are large at Rs 1.29 arba: the company is still claiming about Rs 1.00 arba (without interest) from NEA under a court-backed arbitration award, and has gone to Lalitpur District Court to have it paid.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 37.47 |
| Net worth per share | Rs 160.05 |
| Market price (Ashwin end) | Rs 671 |
| P/E (annualised) | 17.91x |
| P/B | 4.19x |
At the Ashwin-end price of Rs 671, the share trades at 17.91 times annualised EPS and 4.19 times net worth per share. Q1 is the strongest season, so the annualised figure flatters the year: on FY 2082/83 EPS of Rs 25.52 the P/E is 26.29. The 20% bonus shares approved at the AGM will also spread profit over more shares.
Conclusion
Positives: loans fell by Rs 21.21 crore, interest cost dropped 31.86%, cash rose, the current ratio is 2.97, Mistri Khola enjoys a tax holiday, and net worth per share rose to Rs 160.05.
Watch: sales and profit fell sharply because of NEA line damage outside the company's control, finance income has dried up, about Rs 1.00 arba is still due from NEA through the courts, and the price of Rs 671 is 4.19 times net worth per share.
Watch how fast NEA restores the transmission lines, Q2 sales from both plants, recovery of the NEA claim, and progress on the Dudh Khola project.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

