













Mandakini Hydropower Ltd – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
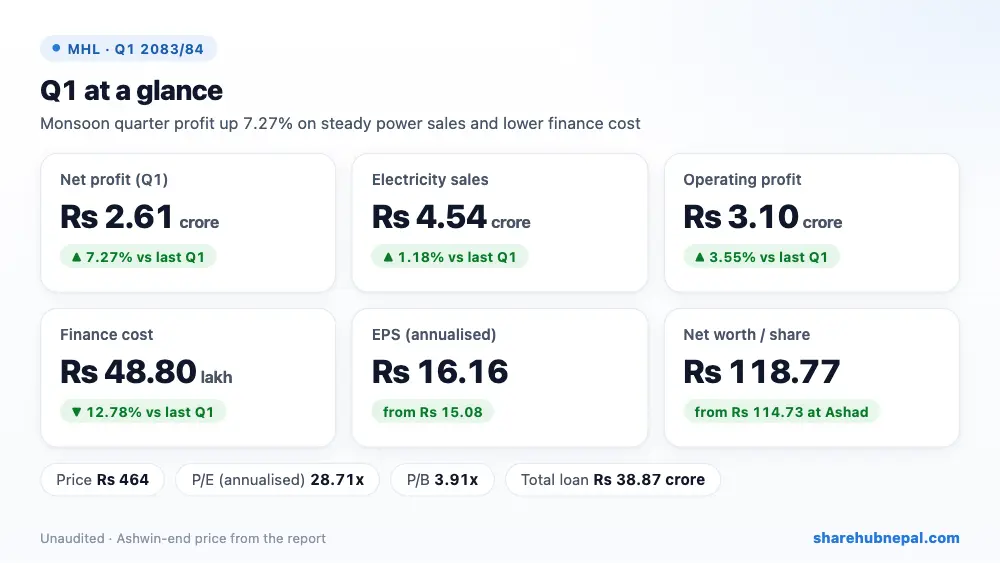
Mandakini Hydropower earned a net profit of Rs 2.61 crore in the first quarter of FY 2083/84, up 7.27% from Rs 2.44 crore a year ago. Electricity sales were almost flat at Rs 4.54 crore (+1.18%), so the gain came from lower costs: finance cost fell 12.78% and staff and admin costs fell 25.84%. Annualised EPS is Rs 16.16 (Rs 15.08 a year ago) and net worth per share is Rs 118.77. The company is also building a new project: assets under development rose to Rs 35.91 crore, funded mostly with loans.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sales | Rs 45,414,086 | Rs 44,884,748 | +1.18% |
| Cost of sales | Rs 5,062,006 | Rs 5,180,047 | −2.28% |
| Other income | Rs 25,578 | Rs 4,505 | +467.77% |
| Operating profit | Rs 31,023,407 | Rs 29,960,976 | +3.55% |
| Finance cost | Rs 4,879,883 | Rs 5,594,982 | −12.78% |
| Income tax | Rs 6,394 | Rs 0 | – |
| Net profit | Rs 26,137,130 | Rs 24,365,995 | +7.27% |
| EPS (annualised) | 16.16 | 15.08 | – |
| Net worth per share | 118.77 | 111.42 | – |
1. Where the profit came from
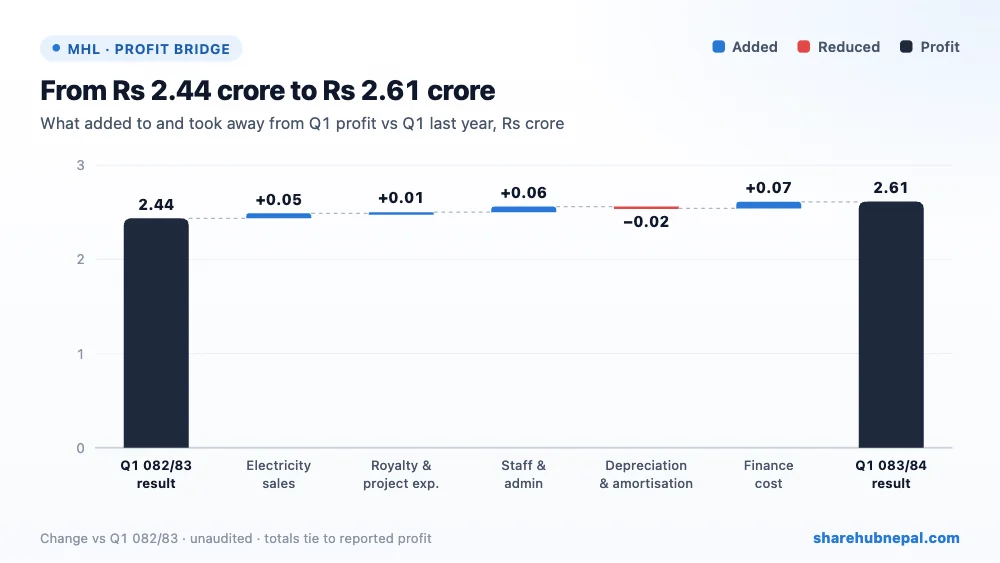
Sales rose by just Rs 5.29 lakh to Rs 4.54 crore. Royalty and project expenses were Rs 50.62 lakh, slightly lower, so gross profit was Rs 4.04 crore. Staff and admin costs fell to Rs 17.23 lakh from Rs 23.24 lakh, while depreciation and amortisation were Rs 76.31 lakh. Operating profit (our calculation; the report has no such line) was Rs 3.10 crore, up 3.55%. Finance cost fell to Rs 48.80 lakh from Rs 55.95 lakh. After a small tax of Rs 6,394, net profit was Rs 2.61 crore. The IFRIC-12 construction revenue and cost of Rs 5.11 crore for the new project cancel out and add nothing to profit.
2. Profit through the year
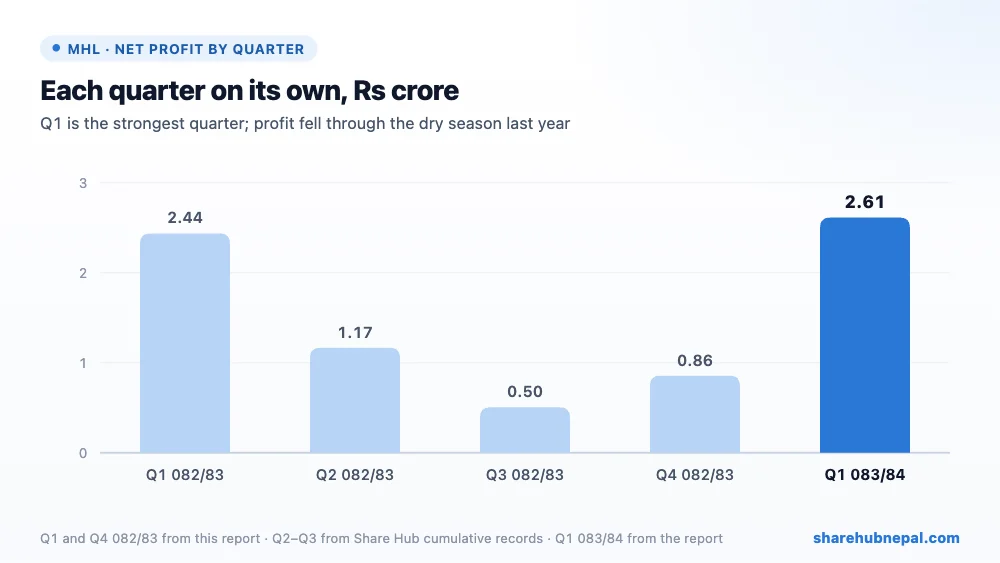
Profit by quarter (from this report and Share Hub records): Q1 082/83: Rs 2.44 crore, Q2 082/83: Rs 1.17 crore, Q3 082/83: Rs 50.50 lakh, Q4 082/83: Rs 85.64 lakh, Q1 083/84: Rs 2.61 crore. This shows how seasonal a run-of-river plant is: last year Q1 earned Rs 2.44 crore but Q3 only Rs 50.50 lakh. FY 2082/83 profit was Rs 4.97 crore (EPS Rs 7.68) per this report, while Share Hub's Q4 record shows Rs 5.67 crore. So annualised EPS of Rs 16.16 overstates the full year.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 1,167,328,209 | Rs 1,132,636,645 | +3.06% |
| Total equity | Rs 768,144,654 | Rs 742,007,525 | +3.52% |
| Long-term borrowings | Rs 386,609,061 | Rs 368,804,481 | +4.83% |
| Current borrowings | Rs 2,079,549 | Rs 12,751,838 | −83.69% |
| Intangible assets under development (new project) | Rs 359,104,138 | Rs 307,967,735 | +16.60% |
| Cash and equivalents | Rs 26,135,806 | Rs 34,078,424 | −23.31% |
| Current assets | Rs 116,448,972 | Rs 125,384,900 | −7.13% |
| Current liabilities | Rs 10,074,892 | Rs 19,165,002 | −47.43% |
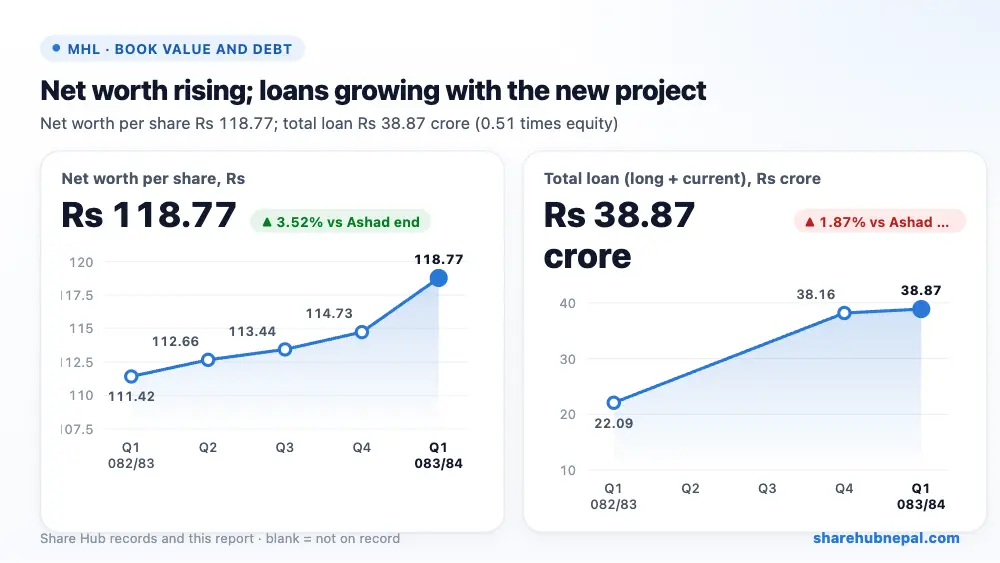
Borrowings rose to Rs 38.66 crore (long-term) plus Rs 20.80 lakh current, from Rs 22.09 crore a year ago, as the company spends on a new project (assets under development up 16.60% this quarter to Rs 35.91 crore). Total loan is still only 0.51 times equity, which is comfortable. Cash fell to Rs 2.61 crore from Rs 3.41 crore, but current liabilities are small at Rs 1.01 crore and the liquidity ratio is 11.55. Equity rose exactly by the Q1 profit to Rs 76.81 crore.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 16.16 |
| Net worth per share | Rs 118.77 |
| Market price (Ashwin end) | Rs 464 |
| P/E (annualised) | 28.71x |
| P/B | 3.91x |
At the Ashwin-end price of Rs 464, the share trades at 28.71 times annualised EPS and 3.91 times net worth per share. Because this is the best quarter, a P/E on full-year earnings would be much higher: on last year's EPS of Rs 7.68 it is about 60 times.
Conclusion
Positives: profit up 7.27%, lower finance and admin costs, low debt at 0.51 times equity, a liquidity ratio of 11.55, and no legal cases.
Watch: sales did not grow, profit is highly seasonal (last year's Q3 was only Rs 50.50 lakh), borrowing is rising for the new project, the report's FY 2082/83 profit (Rs 4.97 crore) differs from Share Hub's Q4 record (Rs 5.67 crore), and the company notes natural disaster risk such as floods, landslides and earthquakes at the project site.
Watch dry-season profit in Q2 and Q3, progress and cost of the new project, and how much more the company borrows.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

