













Mountain Hydro Nepal Ltd – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
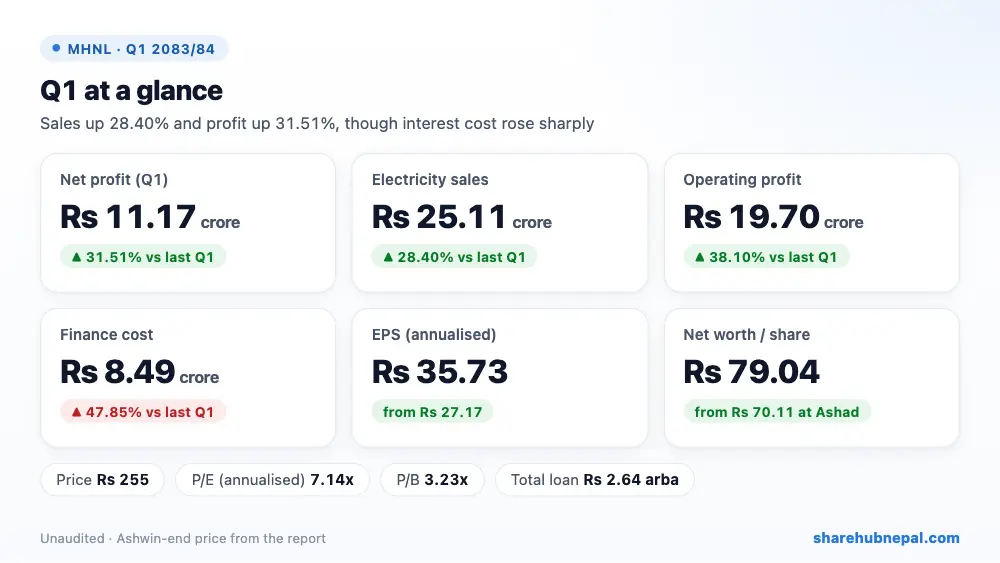
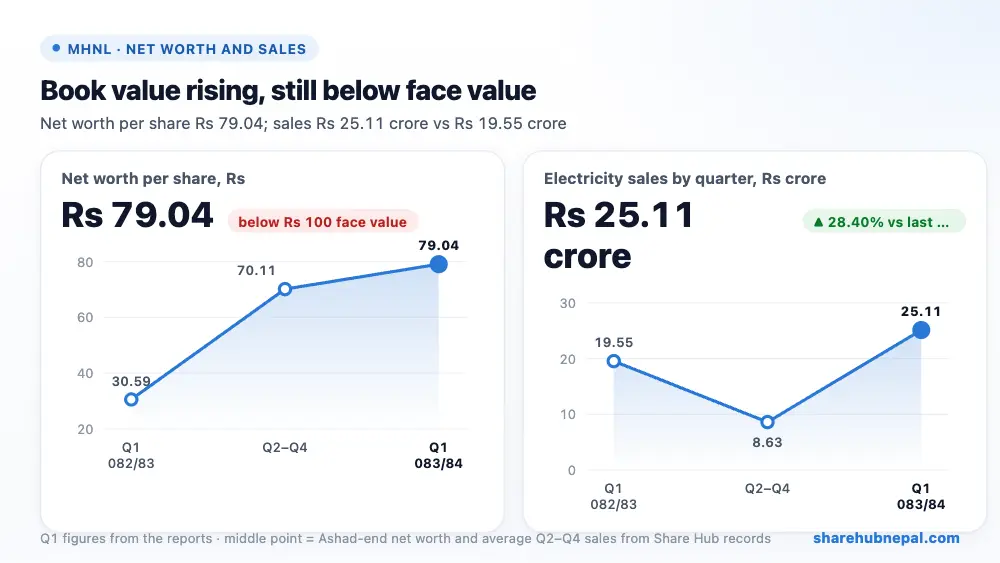
Mountain Hydro Nepal earned a net profit of Rs 11.17 crore in the first quarter of FY 2083/84, up 31.51% from Rs 8.49 crore a year ago. Electricity sales rose 28.40% to Rs 25.11 crore. The company says the repair of the earlier flood damage is complete and the plant is generating at full capacity, except when Nepal Electricity Authority (NEA) asks it to run at lower capacity. Finance cost rose 47.85% to Rs 8.49 crore and took away part of the gain. Quarter EPS is Rs 8.93 (Rs 35.73 annualised) and net worth per share is Rs 79.04.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sales | Rs 251,084,169 | Rs 195,542,312 | +28.40% |
| Cost of sales | Rs 47,619,988 | Rs 48,692,162 | −2.20% |
| Other income | Rs 0 | Rs 10,110 | −100.00% |
| Operating profit | Rs 197,020,227 | Rs 142,661,949 | +38.10% |
| Finance cost | Rs 84,941,493 | Rs 57,452,816 | +47.85% |
| Income tax | Rs 0 | Rs 0 | – |
| Net profit | Rs 111,659,050 | Rs 84,906,005 | +31.51% |
| EPS (annualised) | 35.73 | 27.17 | – |
| Net worth per share | 79.04 | 30.59 | – |
1. Where the profit came from
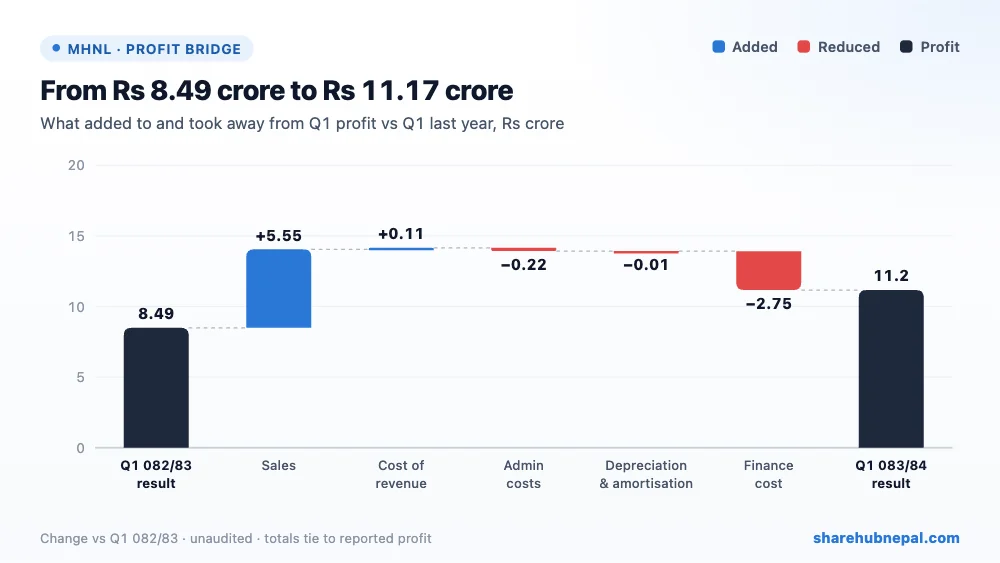
Higher sales added Rs 5.55 crore and cost of revenue fell slightly (down 2.20% to Rs 4.76 crore), so gross profit rose 38.55% to Rs 20.35 crore and the gross margin improved to 81.03% from 75.10%. Finance cost rose by Rs 2.75 crore to Rs 8.49 crore even though total loans fell, and the report does not explain why. Admin cost rose 53.49% to Rs 64.44 lakh, but it is small. Depreciation was only Rs 4.20 lakh. There was no other income (Rs 10,110 a year ago) and no income tax. Operating profit before depreciation and interest rose 38.10% to Rs 19.70 crore.
2. Profit through the year
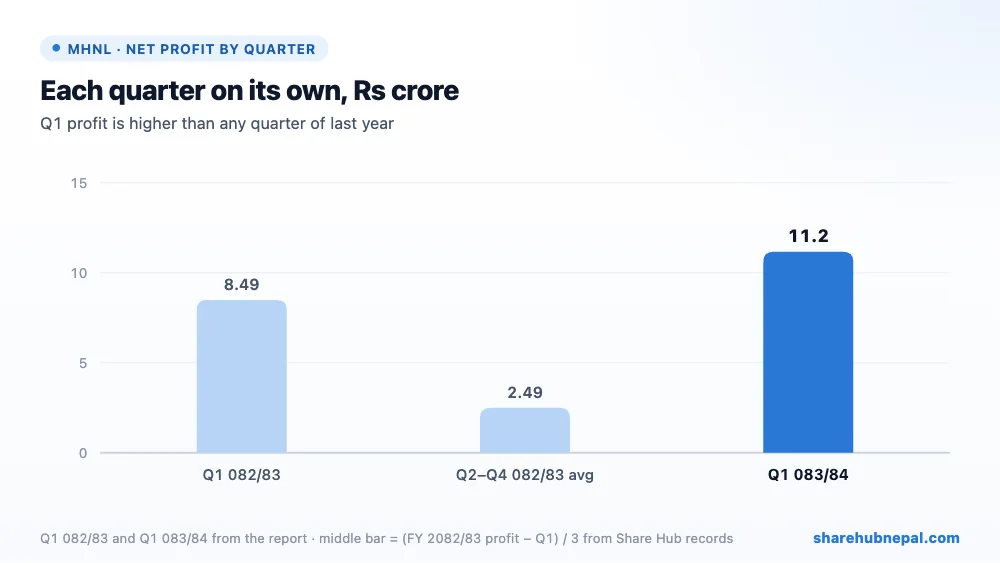
Profit by quarter (Share Hub records): Q1 082/83: Rs 8.49 crore, Q2–Q4 082/83 avg: Rs 2.49 crore, Q1 083/84: Rs 11.17 crore. FY 2082/83 ended with a profit of Rs 15.97 crore, but that included Rs 10.29 crore of other income booked during the year; Q2 to Q4 together earned only Rs 7.48 crore after Q1. Q1 is the monsoon peak, so the coming dry-season quarters are likely to be weaker than this one.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 3,916,092,145 | Rs 3,952,949,617 | −0.93% |
| Total equity | Rs 988,040,789 | Rs 876,381,738 | +12.74% |
| Long-term borrowings | Rs 2,402,723,587 | Rs 2,480,992,207 | −3.15% |
| Current borrowings | Rs 234,840,466 | Rs 234,845,052 | −0.00% |
| Cash and equivalents | Rs 711,225 | Rs 1,440,392 | −50.62% |
Total loans fell from Rs 2.87 arba a year ago and Rs 2.72 arba at Ashad end to Rs 2.64 arba (Rs 2.40 arba long-term and Rs 23.48 crore short-term), but they are still 2.67 times equity. Equity rose to Rs 98.80 crore, exactly by the Q1 profit, and the accumulated loss is now Rs 26.20 crore. Intangible project assets fell by Rs 11.63 crore in the quarter to Rs 3.62 arba, more than the whole cost of revenue, and the report gives no breakdown. Receivables rose to Rs 17.38 crore while cash is only Rs 7.11 lakh, so current assets cover just 0.45 times current liabilities. The company is also in re-arbitration with its civil contractor, Himal Hydro and General Construction, over a payment dispute.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 35.73 |
| Net worth per share | Rs 79.04 |
| Market price (Ashwin end) | Rs 255 |
| P/E (annualised) | 7.14x |
| P/B | 3.23x |
At the Ashwin-end price of Rs 255, the share trades at 7.14 times annualised EPS and 3.23 times net worth per share. At Rs 255 the share trades at 3.23 times book value. The report prints P/E 28.55 on the quarter EPS; on annualised EPS it is 7.14, but Q1 is the strongest season, so the full-year EPS will likely be much lower (FY 2082/83 EPS was Rs 12.78, a P/E of 19.95 at today's price).
Conclusion
Positives: sales up 28.40%, gross margin 81.03%, profit up 31.51%, flood repair finished and the plant running, loans coming down.
Watch: finance cost up 47.85% with no explanation, very little cash and a liquidity ratio of 0.45, an unexplained Rs 11.63 crore drop in intangible assets, NEA instructions to run at lower capacity, an open dispute with the civil contractor, and net worth per share still below Rs 100.
The next quarters will show whether MHNL stays profitable in the dry season, whether interest cost falls as loans are repaid, and how much NEA limits generation. The result of the contractor dispute is also worth watching.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

