













Maya Khola Hydropower Company Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
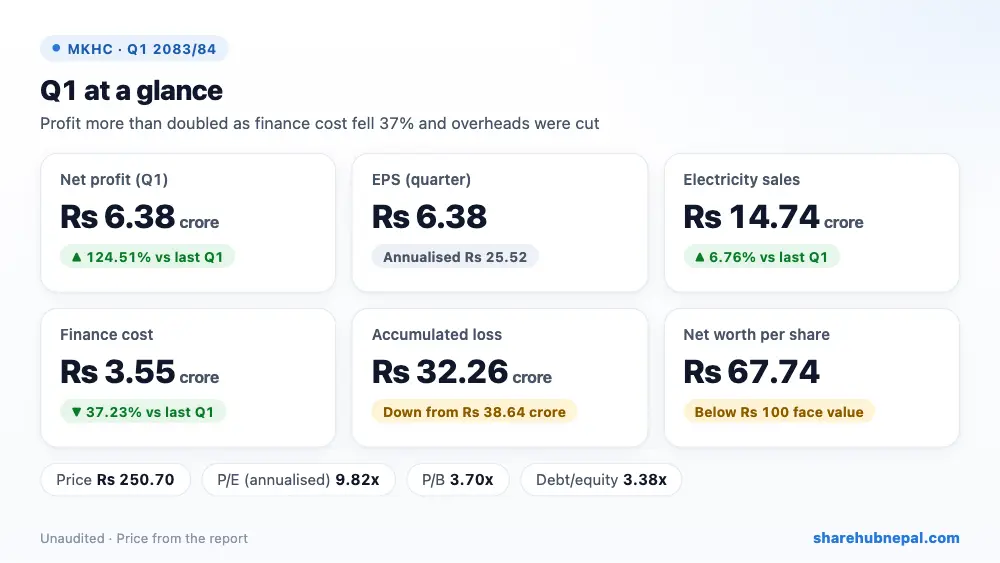
Maya Khola Hydropower earned a net profit of Rs 6.38 crore in the first quarter, up 124.51% from Rs 2.84 crore a year ago. EPS for the quarter is Rs 6.38 (about Rs 25.52 annualised).
Electricity sales rose 6.76% to Rs 14.74 crore, and costs fell sharply: finance cost dropped 37.23% to Rs 3.55 crore, and direct plus operating and admin expenses fell 25.38% to Rs 1.41 crore. Note that the report is in NPR thousand.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Electricity sales | Rs 147,362,000 | Rs 138,026,000 | +6.76% |
| Operating profit | Rs 133,602,000 | Rs 120,371,000 | +10.99% |
| Finance cost | Rs 35,512,000 | Rs 56,579,000 | −37.23% |
| Depreciation | Rs 32,985,000 | Rs 34,488,000 | −4.36% |
| Net profit | Rs 63,804,000 | Rs 28,419,000 | +124.51% |
| EPS (quarter) | 6.38 | 2.84 | – |
1. Where the profit came from
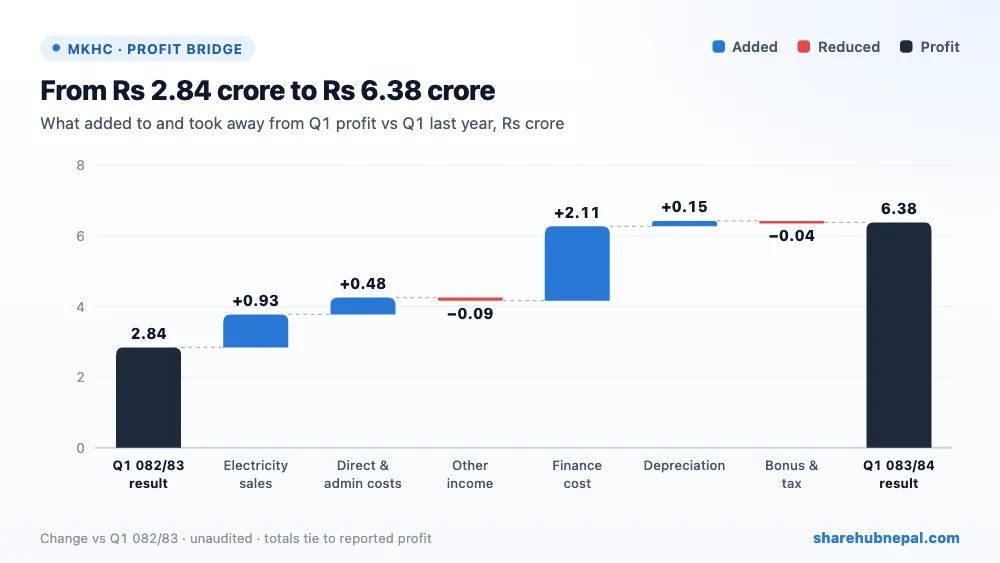
Compared with last year’s Q1, lower finance cost added Rs 2.11 crore, higher sales Rs 93.36 lakh, lower direct and admin costs Rs 47.84 lakh and lower depreciation Rs 15.03 lakh. Other income fell Rs 8.88 lakh and the staff bonus provision rose with profit.
2. Profit through the year
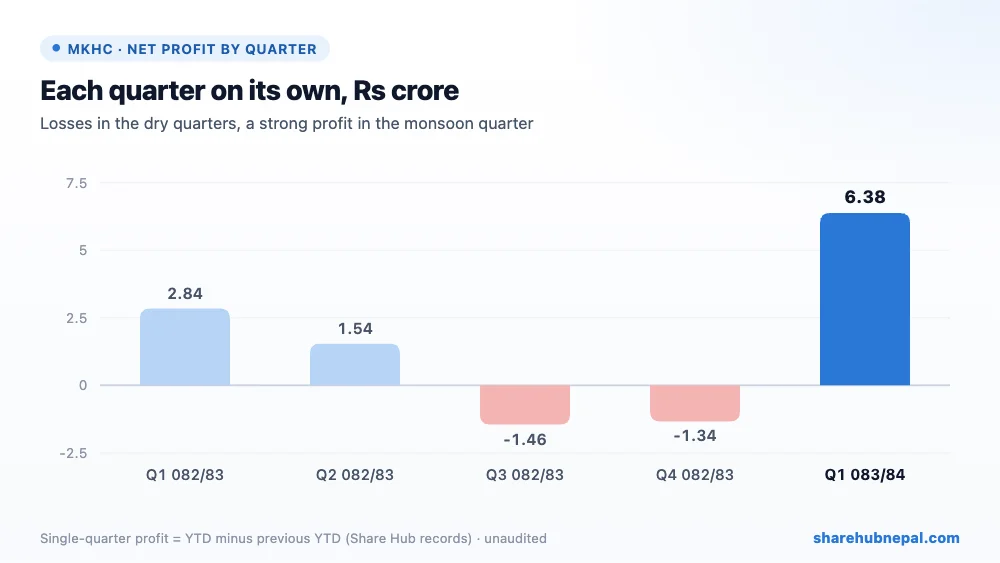
Based on Share Hub’s records, single-quarter results in 2082/83 were a profit of Rs 2.84 crore in Q1 and Rs 1.54 crore in Q2, then losses of Rs 1.46 crore in Q3 and Rs 1.34 crore in Q4. In the dry season output falls while interest and depreciation stay the same, so the plant loses money. Note: this report’s Ashad-end column shows a revised full-year profit of Rs 1.13 crore, lower than the Rs 1.59 crore in the earlier Q4 report.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Long-term loan | Rs 2,242,085,000 | Rs 2,281,068,000 | −1.71% |
| Short-term loan | Rs 45,000,000 | Rs 38,000,000 | +18.42% |
| Property, plant and equipment | Rs 2,969,706,000 | Rs 3,002,691,000 | −1.10% |
| Sundry debtors | Rs 99,954,000 | Rs 65,933,000 | +51.60% |
| Total assets | Rs 3,119,861,000 | Rs 3,105,576,000 | +0.46% |
| Total equity | Rs 677,383,000 | Rs 613,579,000 | +10.40% |
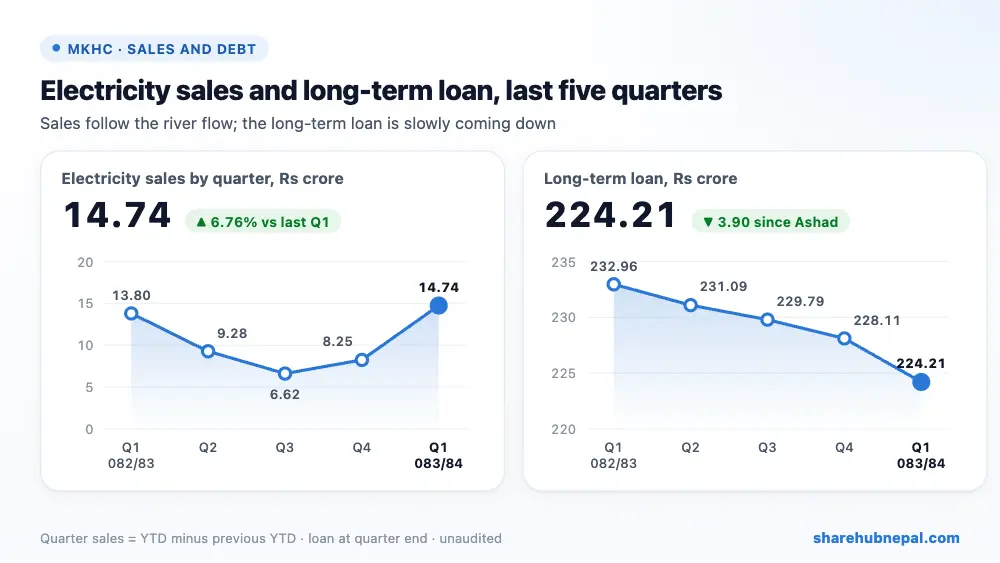
The long-term loan fell Rs 3.90 crore to Rs 224.21 crore, while the short-term loan rose to Rs 4.50 crore. Debt is 3.38 times equity, still high. Reserves show an accumulated loss of Rs 32.26 crore, so net worth per share (Rs 67.74) is below the Rs 100 face value. Sundry debtors rose to Rs 10.00 crore, and current liabilities are larger than current assets (liquidity ratio 0.75).
4. Per-share figures and valuation
| Indicator | Value |
| EPS (quarter) | Rs 6.38 |
| EPS (annualised) | Rs 25.52 |
| Net worth per share | Rs 67.74 |
| Market price (report) | Rs 250.70 |
| P/E on annualised EPS | 9.82x |
| P/B | 3.70x |
| Liquidity ratio | 0.75 |
At Rs 250.70 the share trades at 9.82 times annualised Q1 EPS and 3.70 times net worth per share. The annualised P/E looks low, but it is misleading: the dry quarters usually make losses, and full-year EPS last year was only about Rs 1.13 to 1.58.
Conclusion
Positives: profit up 124.51%, finance cost down 37.23%, overheads cut, sales up 6.76%, and the long-term loan coming down.
Watch: losses in the dry quarters, debt at 3.38 times equity, an accumulated loss of Rs 32.26 crore, a liquidity ratio below 1, and a revised (lower) full-year 2082/83 profit.
Maya Khola had a very good monsoon quarter thanks to lower interest costs. It still carries heavy debt and past losses, so the dry-season quarters will decide whether the full year is meaningfully profitable.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

