













Mahila Lagubitta Bittiya Sanstha Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with the year end (Ashad end 2083).
Summary
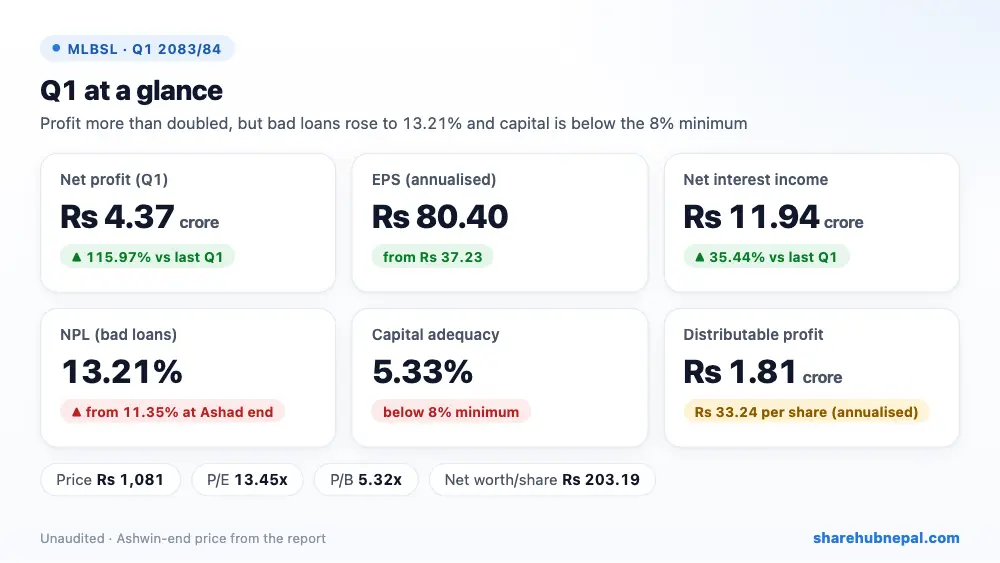
Mahila Laghubitta earned a net profit of Rs 4.37 crore in the first quarter, up 115.97% from Rs 2.02 crore in the same quarter last year. EPS is Rs 80.40 against Rs 37.23.
Compared with last year, the biggest help came from net interest income (+Rs 3.12 crore) and impairment (+Rs 68.90 lakh), while the biggest drag was income tax (−Rs 1.01 crore).
Mahila Laghubitta more than doubled its Q1 profit to Rs 4.37 crore up 115.97% from Rs 2.02 crore. Net interest income rose 35.44% because interest income rose 12.37% while interest expense fell 10.50% as costly bulk borrowing from banks was cut. A small impairment write-back of Rs 2.51 lakh (against a Rs 66.39 lakh charge a year ago) also helped. But the balance sheet is weak: bad loans (NPL) rose to 13.21% from 11.35% at Ashad end and 2.24% a year ago, and capital adequacy is only 5.33%, far BELOW the 8% minimum. The company has signed a preliminary merger agreement with First Microfinance Laghubitta.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Net profit | Rs 43,729,804 | Rs 20,248,526 | +115.97% |
| Net interest income | Rs 119,383,976 | Rs 88,146,036 | +35.44% |
| Net fee and commission income | Rs 14,957,831 | Rs 16,098,647 | −7.09% |
| Impairment charge/(reversal) | −Rs 251,239 | Rs 6,639,144 | – |
| Operating profit | Rs 62,471,149 | Rs 28,926,466 | +115.97% |
| EPS | Rs 80.40 | Rs 37.23 | – |
| Net worth per share | Rs 203.19 | Rs 148.70 | +36.64% |
| NPL | 13.21% | 2.24% | +10.97 pts |
| Capital adequacy | 5.33% | 9.28% | −3.95 pts |
1. Where the profit came from
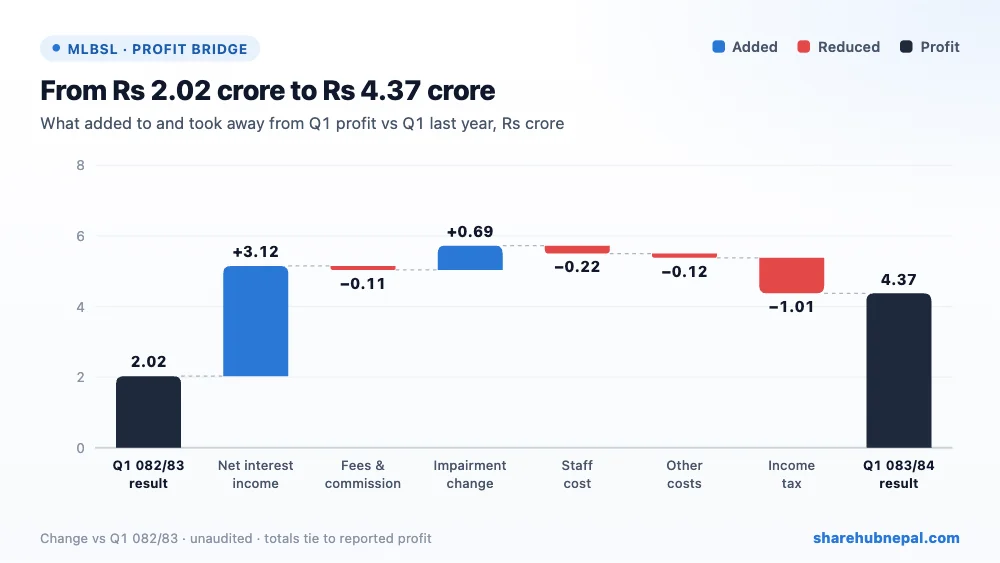
The bridge chart shows how Q1 profit moved from last year's Rs 2.02 crore to this year's Rs 4.37 crore:
- Net interest income (+Rs 3.12 crore): interest income rose 12.37% while interest expense fell 10.50%.
- Income tax (−Rs 1.01 crore): tax was Rs 1.87 crore against Rs 86.78 lakh last year.
- Impairment (+Rs 68.90 lakh): the bank wrote back (reversed) Rs 2.51 lakh of earlier loan-loss provisions, against a charge of Rs 66.39 lakh last year.
- Staff cost (−Rs 22.47 lakh): personnel expenses rose 3.72% to Rs 6.27 crore.
- Other costs (−Rs 11.95 lakh): other operating expenses, depreciation and non-operating items combined.
- Fees & commission (−Rs 11.41 lakh): net fee income was Rs 1.50 crore against Rs 1.61 crore.
In plain terms: operating costs took 53.7% of operating income, against 65.9% a year ago.
2. Profit through the year
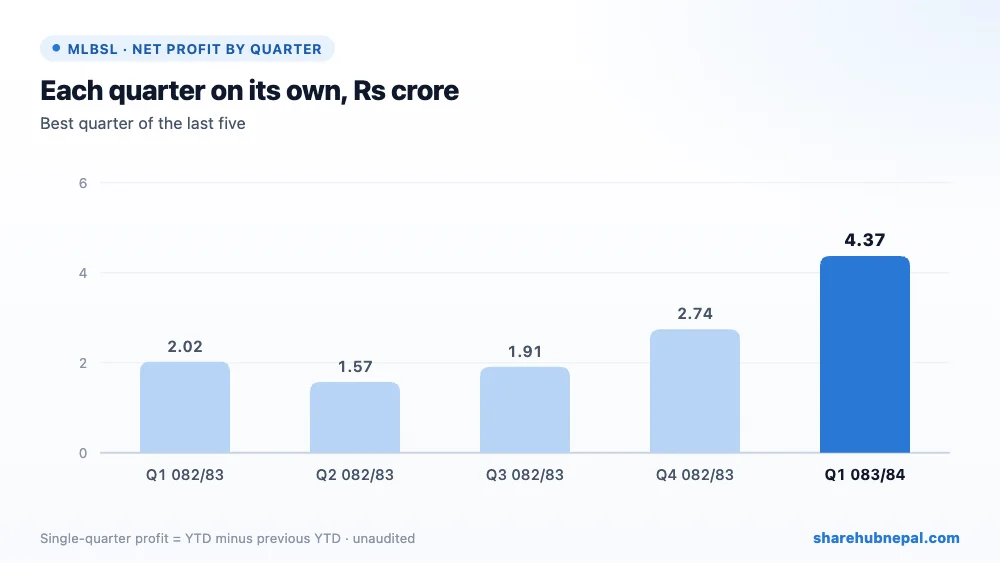
Looking at each quarter on its own (year-to-date profit minus the previous quarter's): Q1 082/83: Rs 2.02 crore; Q2 082/83: Rs 1.57 crore; Q3 082/83: Rs 1.91 crore; Q4 082/83: Rs 2.74 crore; Q1 083/84: Rs 4.37 crore.
Based on Share Hub's records, single-quarter profit in 2082/83 was Rs 2.02 crore in Q1, Rs 1.57 crore in Q2, Rs 1.91 crore in Q3 and Rs 2.74 crore in Q4. This Q1 is the best of the last five quarters.
3. Deposits, loans and liquidity
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Deposits from customers | Rs 2,452,202,383 | Rs 2,357,225,728 | +4.03% |
| Loans and advances to customers | Rs 5,210,802,672 | Rs 5,230,135,755 | −0.37% |
| Cash and cash equivalent | Rs 43,443,682 | Rs 84,932,282 | −48.85% |
| Balance with Nepal Rastra Bank | Rs 25,819,611 | Rs 25,819,611 | +0.00% |
| Investment securities | Rs 0 | Rs 0 | n/a |
| Total assets | Rs 5,529,773,140 | Rs 5,499,813,355 | +0.54% |
| Total equity | Rs 442,056,345 | Rs 323,519,075 | +36.64% |
In the quarter, deposits grew 4.03% and customer loans fell 0.37%. The credit-to-deposit ratio is 105.83% (109.94% a year ago).
Pricing: cost of funds 7.06% (from 7.10%), base rate 12.56% (from 12.44%), interest spread 7.37% (from 7.90%).
Loans to customers were almost flat at Rs 5.21 arba (down 0.37% since Ashad end). Deposits grew 4.03% to Rs 2.45 arba and borrowings fell 8.37% to Rs 2.47 arba which cut interest cost. Cash fell 48.85% to Rs 4.34 crore and the liquidity ratio is 4.60%; management says this is because bulk borrowing from banks was reduced. Equity rose by Rs 11.85 crore to Rs 44.21 crore which is Rs 7.48 crore more than the Q1 profit, while deferred tax assets jumped by Rs 8.49 crore to Rs 10.55 crore. The report does not explain these moves.
4. Bad loans and capital
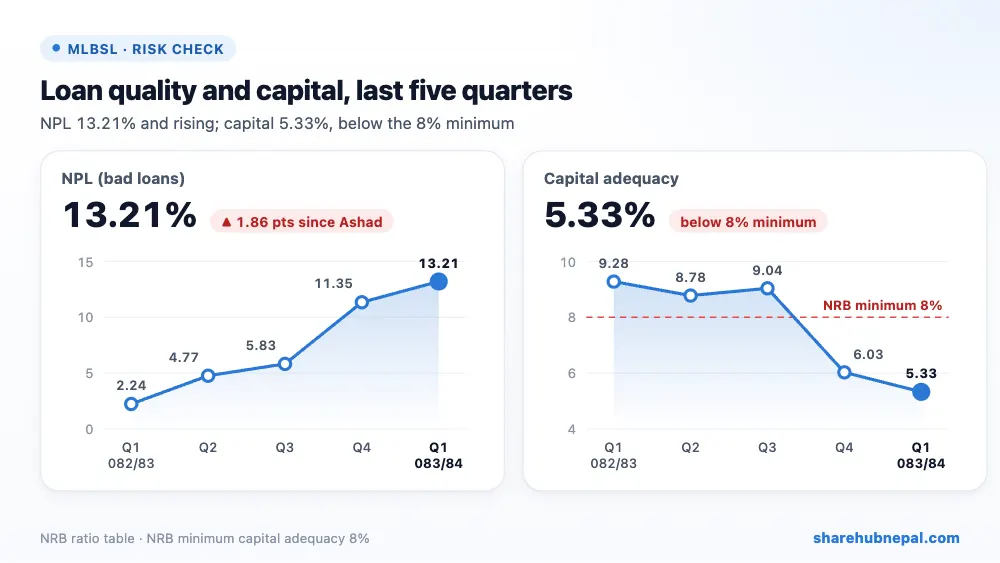
- NPL is 13.21%, against 11.35% at Ashad end and 2.24% a year ago. Loan-loss provisions cover 97.90% of bad loans (200.92% a year ago).
- Capital adequacy is 5.33%, against 6.03% at Ashad end and 9.28% a year ago. NRB's minimum is 8%, so the buffer is -2.67 points.
- Risk is HIGH. NPL is 13.21% (11.35% at Ashad end, 2.24% a year ago) and provisions cover 97.90% of bad loans (200.92% a year ago). Even so, the quarter shows a small provision write-back, which is unusual when bad loans are rising. Capital adequacy is 5.33%, far below the 8% NRB minimum (6.03% at Ashad end, 9.28% a year ago); fresh capital or the planned merger will be needed to fix this.
5. Distributable profit
| Particulars (Rs) | Amount |
| Net profit for the quarter | 43,729,804 |
| Less: general reserve | (8,745,961) |
| Less: client protection fund | (1,311,894) |
| Less: CSR and other funds | (874,596) |
| Less: regulatory reserve | (14,718,089) |
| Q1 distributable profit | 18,079,264 |
Of the Rs 4.37 crore profit, Rs 1.09 crore went to the general reserve, client protection fund, CSR fund and other funds, and Rs 1.47 crore was moved to the regulatory reserve, leaving Rs 1.81 crore distributable for the quarter (Rs 33.24 per share annualised). Retained earnings are still negative (Rs -74,522,574), so dividend capacity is weak.
6. Per-share figures and valuation
| Indicator | Value |
| EPS (as reported) | Rs 80.40 |
| Net worth per share | Rs 203.19 |
| Distributable EPS | Rs 33.24 |
| Closing price, Ashwin end 2083 | Rs 1081.00 |
| Price range during the quarter | Rs 1026.00 – Rs 1780.00 |
| P/E (annualised EPS) | 13.4x |
| Price to book | 5.32x |
At Rs 1,081 the share trades at 13.45 times annualised EPS (as printed) and 5.32 times net worth per share. The P/E looks low, but the P/B is high for a microfinance with NPL above 13% and capital below the minimum; the price likely reflects merger expectations.
Conclusion
Positives: profit up 115.97%, net interest income up 35.44%, lower interest expense, growing deposits, and a merger agreement in progress.
Watch points: NPL at 13.21% and rising, capital adequacy of 5.33% below the 8% minimum, cash down by half, unexplained jumps in equity (Rs 7.48 crore beyond profit) and deferred tax assets, negative retained earnings and a high P/B.
The profit jump is real at the interest-margin level, but the risk picture has worsened. Watch NPL, how and when capital is brought back above 8%, and the progress of the merger with First Microfinance Laghubitta.
Based on the company's unaudited first-quarter report. Figures may change after audit or regulator review. This is not investment advice.

