













Mathillo Mailun Khola Jalvidhyut Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
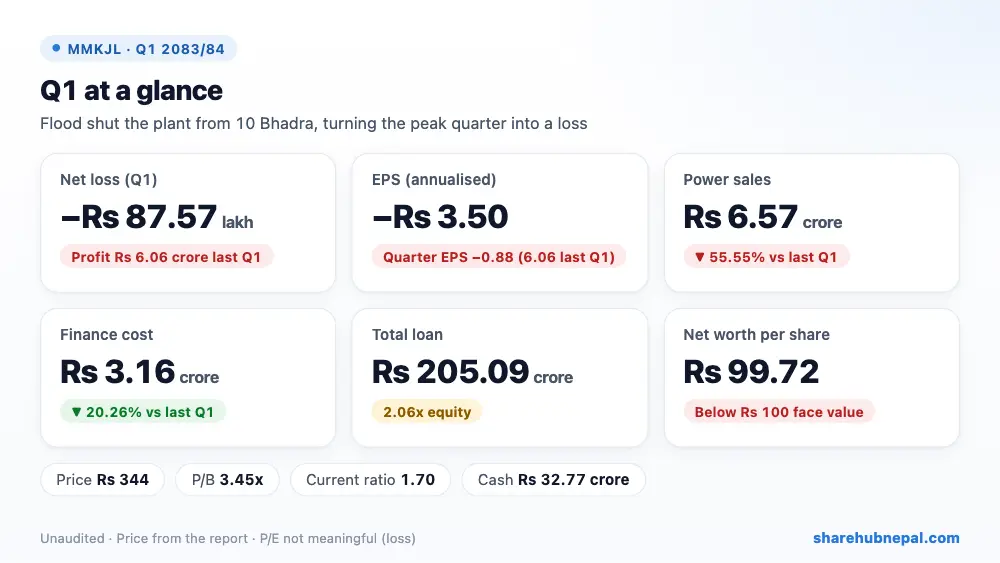
Summary
Mathillo Mailun Khola Jalvidhyut, which runs the 14.3 MW Mathillo Mailung project, made a net loss of Rs 87.57 lakh in the first quarter, against a profit of Rs 6.06 crore a year ago. Quarter EPS is −Rs 0.88 (−Rs 3.50 annualised).
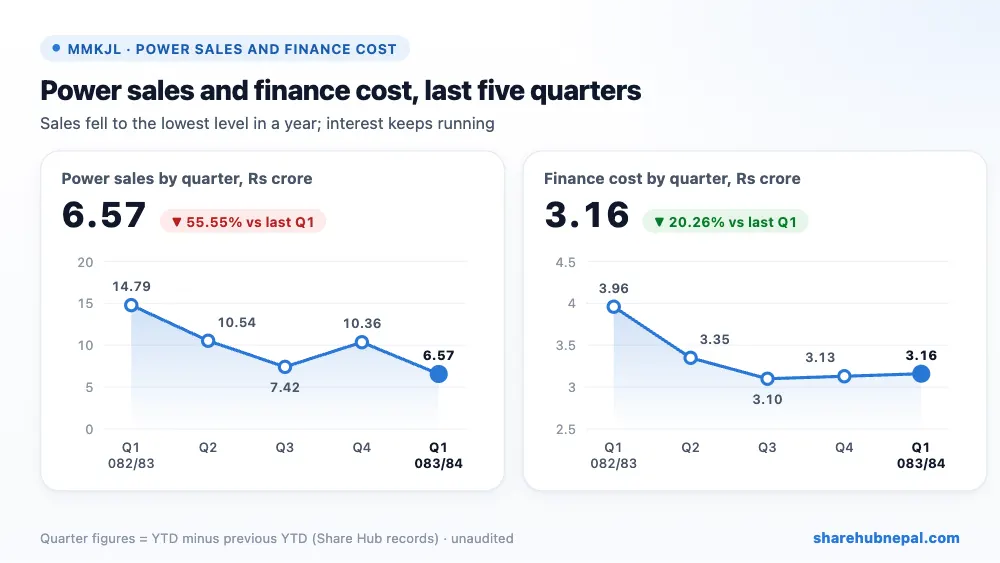
The heavy Trishuli flood of 10 Bhadra 2083 washed away transmission towers and equipment at the Trishuli 3B hub substation, and the plant has been shut since then. So in what is normally the best (monsoon) quarter, power sales fell 55.55% to Rs 6.57 crore. Finance cost (Rs 3.16 crore) and amortisation (Rs 2.70 crore) do not stop when the plant stops, which turned the quarter into a loss. The damage is still being assessed, and property-damage and loss-of-profit insurance claims are in process; none of that is booked yet.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sale of electricity | Rs 65,718,209 | Rs 147,859,456 | −55.55% |
| Power plant operation expenses | Rs 12,116,594 | Rs 14,192,116 | −14.62% |
| Profit from operation | Rs 22,422,741 | Rs 99,695,123 | −77.51% |
| Finance cost | Rs 31,610,656 | Rs 39,640,700 | −20.26% |
| Net profit/(loss) | −Rs 8,756,970 | Rs 60,576,803 | Turned to loss |
| EPS (quarter, not annualised) | -0.88 | 6.06 | – |
1. Where the profit came from
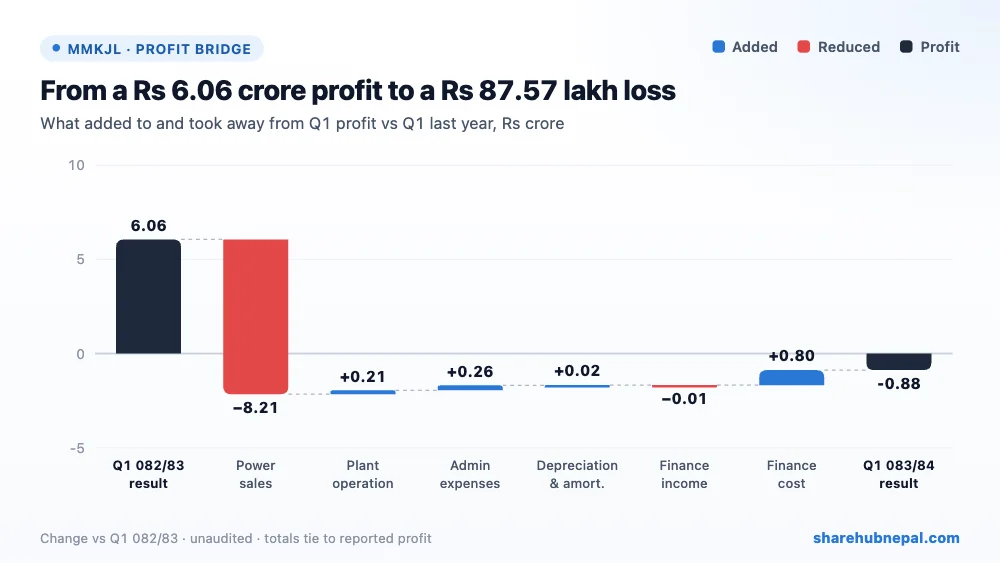
Compared with last year's Q1, lower power sales took away Rs 8.21 crore. Lower finance cost added Rs 80.30 lakh (the bank loan was cut over the year), and lower administrative and plant operation costs added Rs 46.84 lakh together. Depreciation and amortisation were almost unchanged.
2. Profit through the year
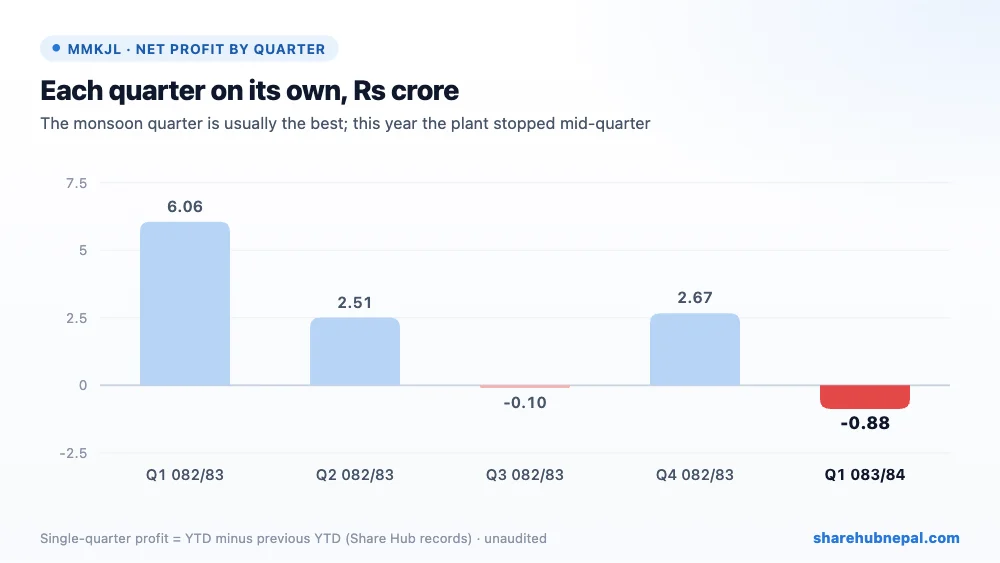
Based on Share Hub's records, single-quarter results in 2082/83 were a profit of Rs 6.06 crore in Q1, Rs 2.51 crore in Q2, a small loss of Rs 10.44 lakh in Q3 (dry season) and a profit of Rs 2.67 crore in Q4. The audited full-year profit was Rs 11.14 crore (EPS 11.14). The first quarter normally carries the year, so the shutdown hurts the full-year result most.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Borrowings (non-current + current) | Rs 2,050,925,145 | Rs 2,050,925,145 | +0.00% |
| Service concession (project) asset | Rs 2,636,255,764 | Rs 2,663,246,125 | −1.01% |
| Projects under development | Rs 115,018,145 | Rs 112,625,550 | +2.12% |
| Cash and cash equivalents | Rs 327,652,699 | Rs 212,338,196 | +54.31% |
| Receivables | Rs 14,907,889 | Rs 85,456,268 | −82.55% |
| Total assets | Rs 3,133,462,994 | Rs 3,116,111,816 | +0.56% |
| Total equity | Rs 997,219,408 | Rs 1,005,976,378 | −0.87% |
Total borrowing is Rs 205.09 crore (Rs 191.35 crore long-term plus Rs 13.75 crore current), unchanged since Ashad end and 2.06 times equity. Cash rose to Rs 32.77 crore from Rs 21.23 crore as Rs 7.05 crore of receivables from NEA were collected. The company is also building two more projects, Madhya Mailung (13 MW) and Mathillo Mailung B (17 MW), with Rs 11.50 crore spent so far. Net worth per share is Rs 99.72, just under the Rs 100 face value.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (quarter) | Rs −0.88 |
| EPS (annualised) | Rs −3.50 |
| Net worth per share | Rs 99.72 |
| Market price (report) | Rs 344.00 |
| P/E | not meaningful (loss) |
| P/B | 3.45x |
| Current ratio | 1.70 |
At Rs 344 the share trades at 3.45 times net worth per share; P/E is not meaningful because the quarter was a loss. On last year's audited EPS of Rs 11.14 the P/E is about 30.88. The price fell from Rs 430 at Ashad end, reflecting the shutdown.
Conclusion
Positives: lower finance cost and overheads, good cash (Rs 32.77 crore) after receivables were collected, insurance cover for both property damage and loss of profit, and two new projects in the pipeline.
Watch: the plant is shut with no restart date, power sales down 55.55%, a net loss, high debt (2.06x equity) with interest still running, the size and timing of insurance recovery, and net worth below face value.
Everything now depends on how fast the interconnection with NEA is restored (the company is looking at alternative arrangements) and on the insurance payout. Until power sales restart, each quarter is likely to show a loss.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

