













Mid Solu Hydropower Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
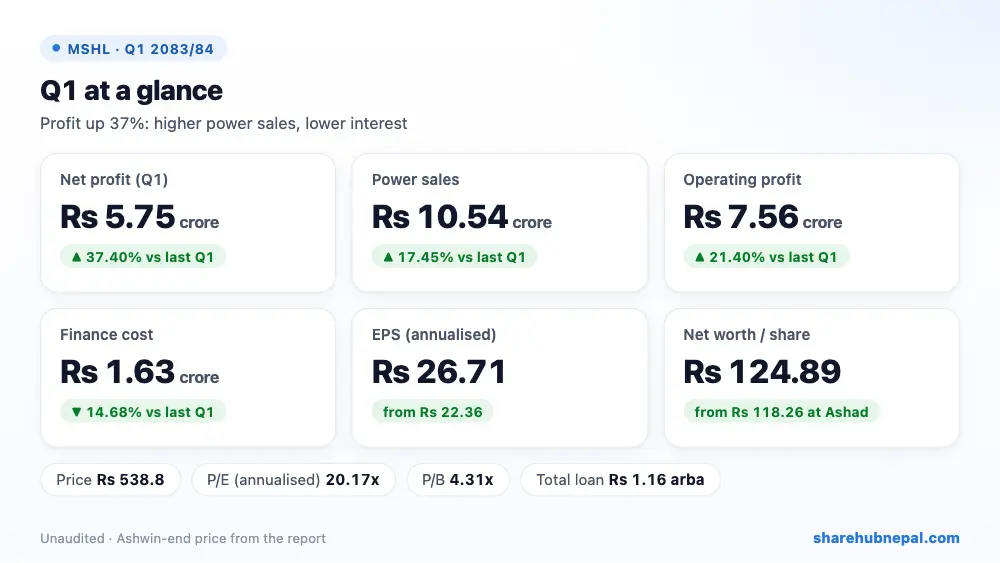
Mid Solu Hydropower earned Rs 5.75 crore in the first quarter of FY 2083/84, up 37.40% from Rs 4.18 crore a year ago. Power sales rose 17.45% to Rs 10.54 crore and interest cost fell 14.69% to Rs 1.63 crore. Annualised EPS is Rs 26.71 against Rs 22.36 a year ago, even on 15% more shares after the bonus issue. Net worth per share is Rs 124.89.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sales | Rs 105,396,429 | Rs 89,738,927 | +17.45% |
| Cost of sales | Rs 7,140,624 | Rs 7,909,787 | −9.72% |
| Other income | Rs 0 | Rs 0 | – |
| Operating profit | Rs 75,564,535 | Rs 62,243,868 | +21.40% |
| Finance cost | Rs 16,311,801 | Rs 19,119,051 | −14.68% |
| Income tax | Rs 0 | Rs 0 | – |
| Net profit | Rs 57,481,137 | Rs 41,835,429 | +37.40% |
| EPS (annualised) | 26.71 | 22.36 | – |
| Net worth per share | 124.89 | 125.36 | – |
1. Where the profit came from
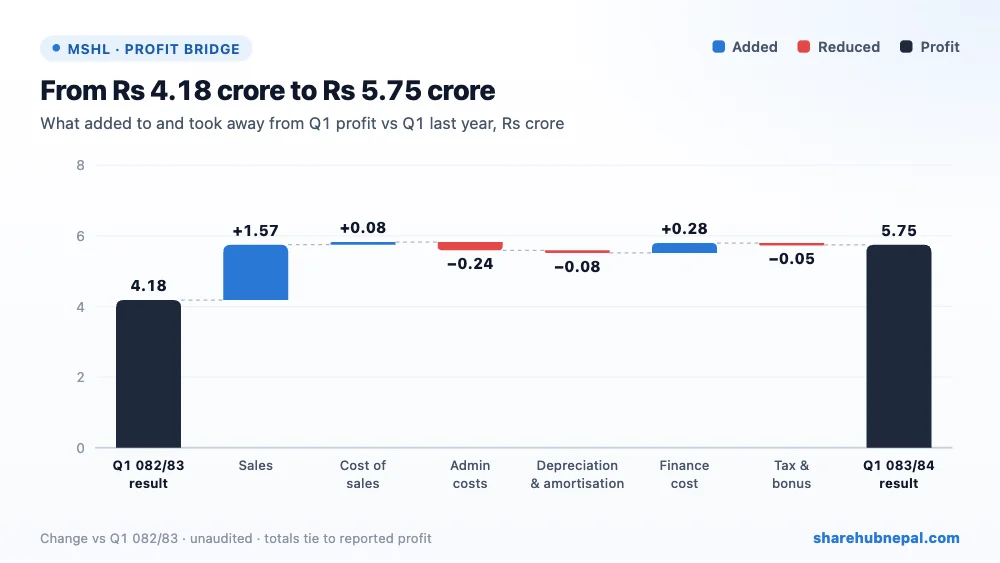
Higher sales added Rs 1.57 crore, lower interest Rs 28.07 lakh and lower cost of sales Rs 7.69 lakh. Staff and admin cost rose Rs 23.54 lakh (employee cost went from Rs 8.43 lakh to Rs 34.74 lakh), depreciation Rs 7.52 lakh, and bonus and CSR Rs 4.82 lakh. No income tax is charged.
2. Profit through the year
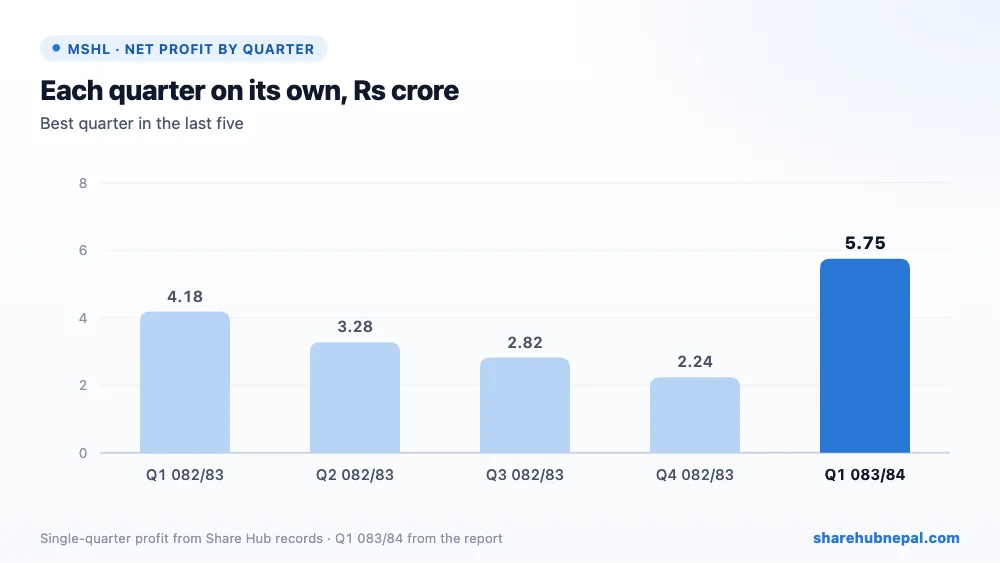
Profit by quarter (Share Hub records): Q1 082/83: Rs 4.18 crore, Q2 082/83: Rs 3.28 crore, Q3 082/83: Rs 2.82 crore, Q4 082/83: Rs 2.24 crore, Q1 083/84: Rs 5.75 crore. All four quarters of last year were profitable; FY 2082/83 EPS was Rs 14.55 after the bonus issue. Q1 is the strongest season.
3. Debt and balance sheet
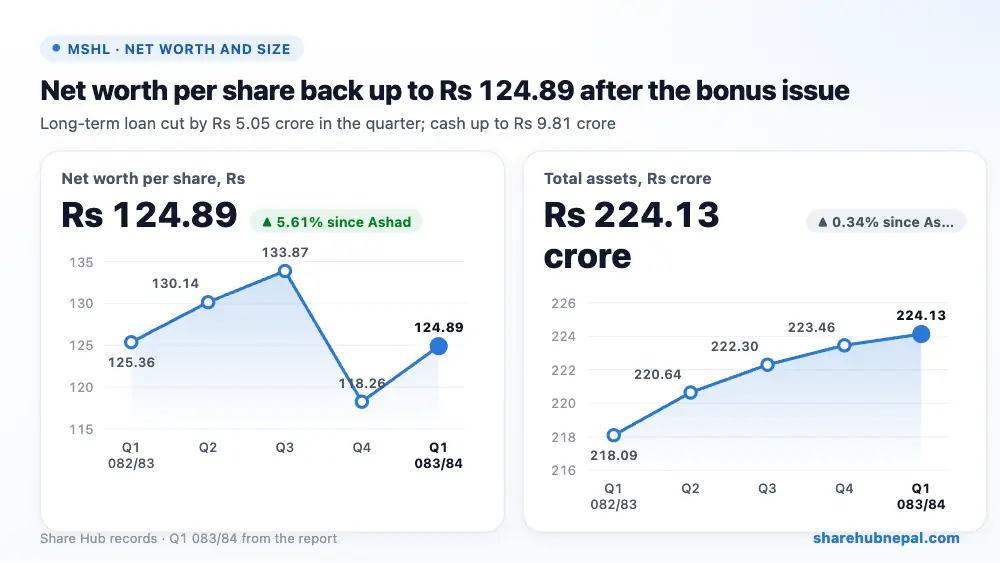
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 2,241,273,746 | Rs 2,233,730,683 | +0.34% |
| Total equity | Rs 1,074,906,575 | Rs 1,017,575,438 | +5.63% |
| Long-term borrowings | Rs 1,115,880,000 | Rs 1,166,380,000 | −4.33% |
| Current borrowings | Rs 40,000,000 | Rs 41,000,000 | −2.44% |
| Cash and equivalents | Rs 98,057,061 | Rs 61,490,599 | +59.47% |
Total assets are Rs 2.24 arba, mostly the Rs 1.93 arba concession asset. Long-term loan fell to Rs 1.12 arba from Rs 1.17 arba at Ashad end, and short-term loan is Rs 4 crore. Cash rose to Rs 9.81 crore and current assets are 5.6 times current liabilities. The Ashad-end profit in this report (Rs 12.49 crore) is slightly below the Share Hub Q4 record (Rs 12.52 crore).
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 26.71 |
| Net worth per share | Rs 124.89 |
| Market price (Ashwin end) | Rs 538.8 |
| P/E (annualised) | 20.17x |
| P/B | 4.31x |
At the Ashwin-end price of Rs 538.8, the share trades at 20.17 times annualised EPS and 4.31 times net worth per share. Q1 is the peak season, so the annualised EPS is higher than a full year will likely be (FY 2082/83 EPS was Rs 14.55).
Conclusion
Positives: profit up 37%, sales up 17%, interest down 15%, loan being repaid, strong cash and current ratio 5.61.
Watch: employee cost four times last year, annualised EPS flattered by the wet season, and a price above four times book value.
A strong quarter with steady debt reduction. Keep an eye on the jump in staff cost.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

