













Nepal Hydro Developer Ltd – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
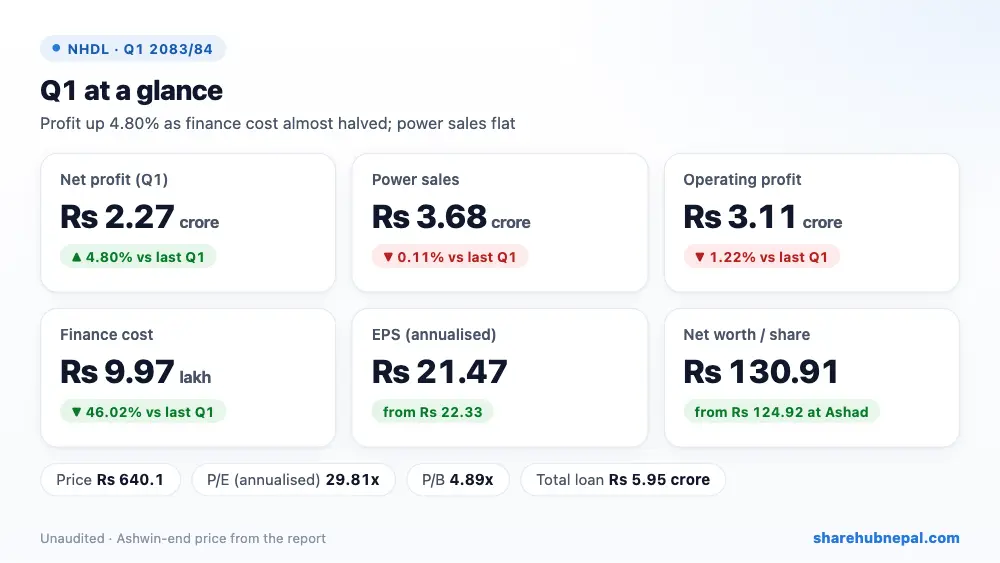
Nepal Hydro Developer earned a net profit of Rs 2.27 crore in the first quarter of FY 2083/84, up 4.80% from Rs 2.17 crore a year ago. Power sales were flat at Rs 3.68 crore (−0.11%) and plant operating expenses rose 6.03%, so operating profit slipped 1.22% to Rs 3.11 crore. The gain came from below the operating line: finance cost almost halved (−46.02%) to Rs 9.97 lakh as the company kept repaying its loans, and tax fell 24.75%. A fair-value gain of Rs 29.38 lakh on listed hydropower shares lifted total comprehensive income to Rs 2.56 crore. Annualised EPS is Rs 21.47 and net worth per share is Rs 130.91.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sales | Rs 36,802,000 | Rs 36,844,000 | −0.11% |
| Cost of sales | Rs 4,922,000 | Rs 4,642,000 | +6.03% |
| Other income | Rs 2,000 | Rs 3,000 | −33.33% |
| Operating profit | Rs 31,059,000 | Rs 31,444,000 | −1.22% |
| Finance cost | Rs 997,000 | Rs 1,847,000 | −46.02% |
| Income tax | Rs 1,812,000 | Rs 2,408,000 | −24.75% |
| Net profit | Rs 22,709,000 | Rs 21,669,000 | +4.80% |
| EPS (annualised) | 21.47 | 22.33 | – |
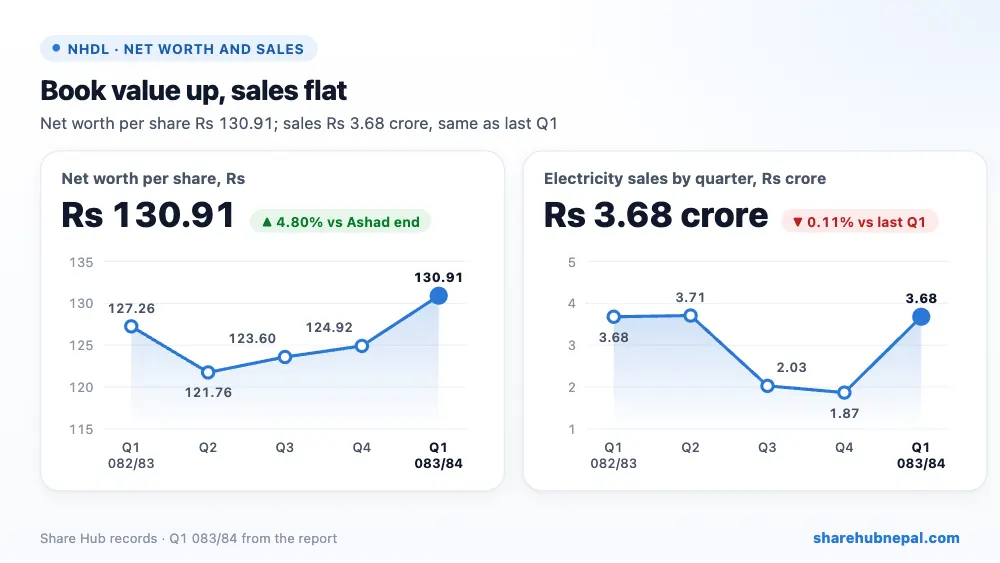
| Net worth per share | 130.91 | 127.26 | – |
1. Where the profit came from
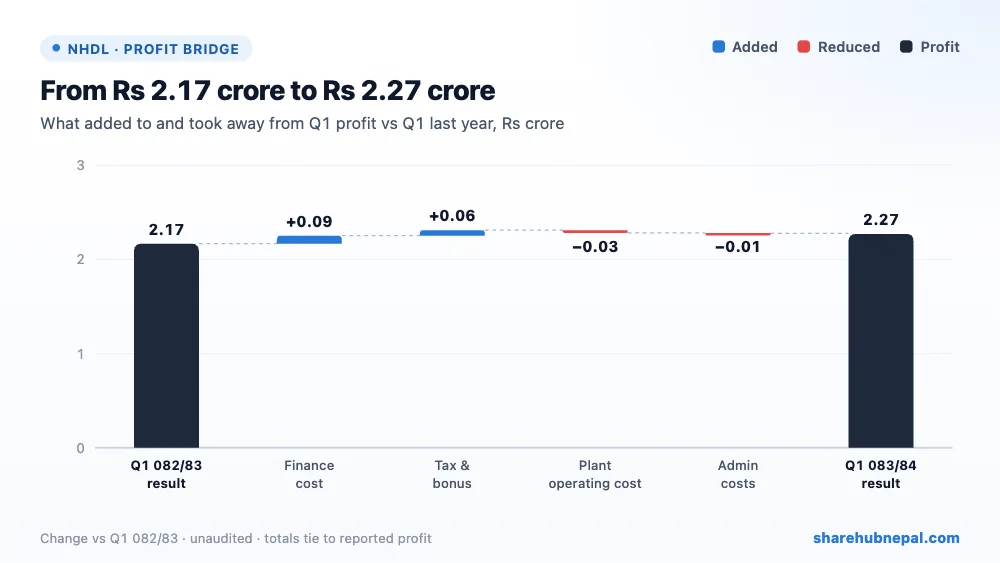
Power sales fell by Rs 42,000 and plant operating expenses rose by Rs 2.80 lakh, so gross profit fell 1.00% to Rs 3.19 crore. Administrative expenses rose by Rs 62,000 to Rs 8.23 lakh, and operating profit ended 1.22% lower at Rs 3.11 crore. Below that line, finance cost fell by Rs 8.50 lakh to Rs 9.97 lakh, depreciation stayed at Rs 48.00 lakh, and tax fell by Rs 5.96 lakh to Rs 18.12 lakh (the company provides tax at 10%). Bonus and CSR provisions were Rs 7.40 lakh. Together these lifted net profit by Rs 10.40 lakh. Note: the management section says profit rose 18.36%, but the statement shows 4.80%.
2. Profit through the year
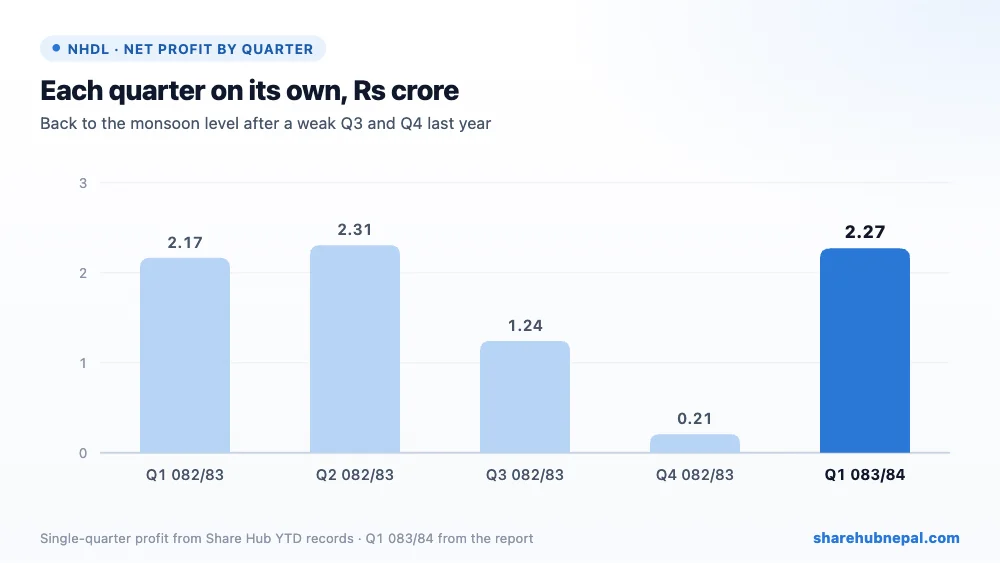
Profit by quarter (Share Hub records): Q1 082/83: Rs 2.17 crore, Q2 082/83: Rs 2.31 crore, Q3 082/83: Rs 1.24 crore, Q4 082/83: Rs 20.52 lakh, Q1 083/84: Rs 2.27 crore. Last year the two monsoon-heavy quarters (Q1 and Q2) earned more than Rs 2 crore each, but Q3 fell to Rs 1.24 crore and Q4 to only Rs 20.52 lakh, so FY 2082/83 EPS ended at Rs 14.00. This Q1 is back at the monsoon level; the dry-season quarters are likely to be weaker again.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 625,223,000 | Rs 610,809,000 | +2.36% |
| Total equity | Rs 553,923,000 | Rs 528,561,000 | +4.80% |
| Long-term loan | Rs 12,500,000 | Rs 24,500,000 | −48.98% |
| Short-term loan | Rs 47,000,000 | Rs 46,500,000 | +1.08% |
| Investments | Rs 161,939,000 | Rs 158,675,000 | +2.06% |
| Current assets | Rs 99,887,000 | Rs 84,610,000 | +18.06% |
The company keeps cutting debt: the long-term loan fell to Rs 1.25 crore from Rs 2.45 crore at Ashad end (Rs 5.95 crore a year ago), and with the Rs 4.70 crore short-term loan the total loan is Rs 5.95 crore, only 0.11 times equity. Current assets rose to Rs 9.99 crore and the current ratio is 1.70. Investments in other hydropower companies are Rs 16.19 crore, mainly Super Khudi (Rs 10 crore) and Solu (Rs 3 crore). Equity rose 4.80% to Rs 55.39 crore. The company says Rs 3.63 crore of additional-rate money for Baisakh 2072 to Chaitra 2078 is still due from Nepal Electricity Authority, which has hurt its cash flow.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 21.47 |
| Net worth per share | Rs 130.91 |
| Market price (Ashwin end) | Rs 640.1 |
| P/E (annualised) | 29.81x |
| P/B | 4.89x |
At the Ashwin-end price of Rs 640.1, the share trades at 29.81 times annualised EPS and 4.89 times net worth per share. The P/E looks moderate because Q1 is the best season. On full-year FY 2082/83 EPS of Rs 14.00 the P/E is about 45.72, and the share trades at almost 4.9 times its book value, so the price already assumes steady earnings.
Conclusion
Positives: profit up 4.80%, finance cost almost halved, very low debt (0.11 times equity), healthy liquidity (current ratio 1.70), a fair-value gain on its hydropower investments, and no legal cases.
Watch: power sales did not grow, plant operating cost rose 6.03%, last year's Q3 and Q4 were weak, Rs 3.63 crore is still due from NEA, the management's 18.36% profit-growth figure does not match the statement, and the company warns of flood risk, transmission-line faults and delays in getting spare parts.
Watch whether sales hold up in the dry season, whether the NEA additional-rate dues are collected, and how the hydropower investments perform.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

