













Nepal Republic Media Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
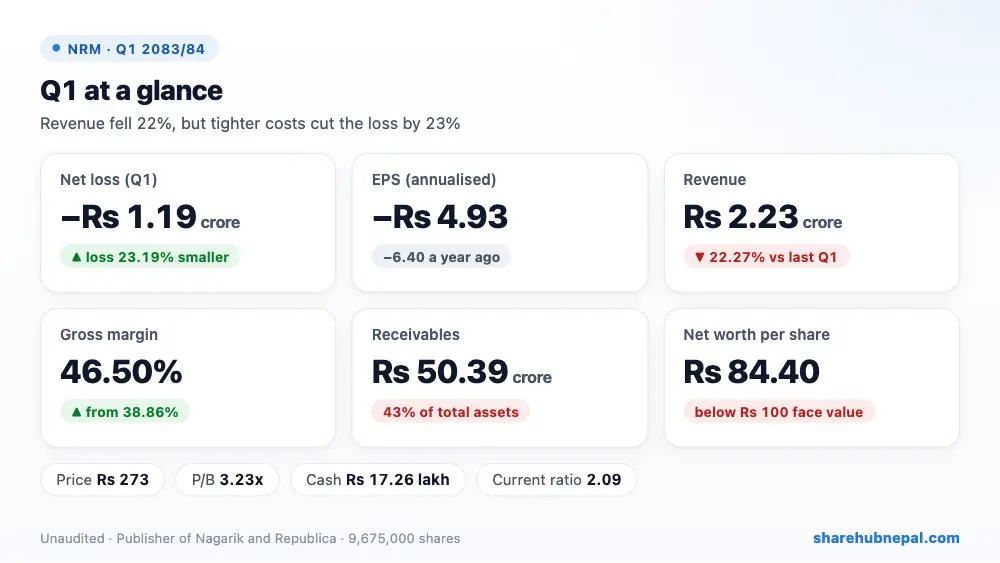
Nepal Republic Media, publisher of the Nagarik and Republica newspapers and their websites, posted a net loss of Rs 1.19 crore in the first quarter, 23.19% smaller than the loss of Rs 1.55 crore a year ago. Annualised EPS is −Rs 4.93.
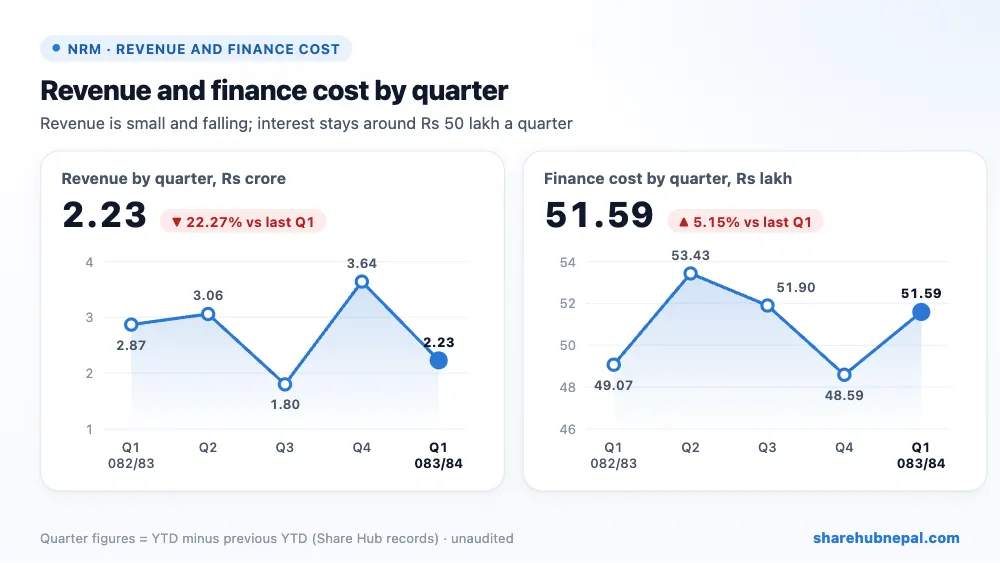
Revenue fell 22.27% to Rs 2.23 crore. The company says government and private advertisers cut spending in the economic slowdown and the government changed its advertising policy. It cut costs harder: cost of sales fell 31.98%, admin cost 15.51% and selling and distribution cost 34.85%, so the gross margin improved to 46.50% from 38.86% and the operating loss shrank to Rs 28.22 lakh. Interest of Rs 51.59 lakh and depreciation of Rs 39.48 lakh made up most of the loss.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue | Rs 22,297,288 | Rs 28,685,010 | −22.27% |
| Cost of sales | Rs 11,929,446 | Rs 17,538,727 | −31.98% |
| Gross income | Rs 10,367,842 | Rs 11,146,283 | −6.98% |
| Other income | Rs 941,899 | Rs 188,147 | +400.62% |
| Administration expenses | Rs 10,885,446 | Rs 12,883,355 | −15.51% |
| Selling and distribution | Rs 3,246,185 | Rs 4,982,552 | −34.85% |
| Operating profit (loss) | −Rs 2,821,890 | −Rs 6,531,477 | +56.80% |
| Finance charge | Rs 5,159,226 | Rs 4,906,609 | +5.15% |
| Depreciation | Rs 3,948,444 | Rs 4,093,990 | −3.56% |
| Net profit (loss) | −Rs 11,929,560 | −Rs 15,532,076 | +23.19% |
| EPS (annualised) | -4.93 | -6.42 | – |
1. Where the profit came from
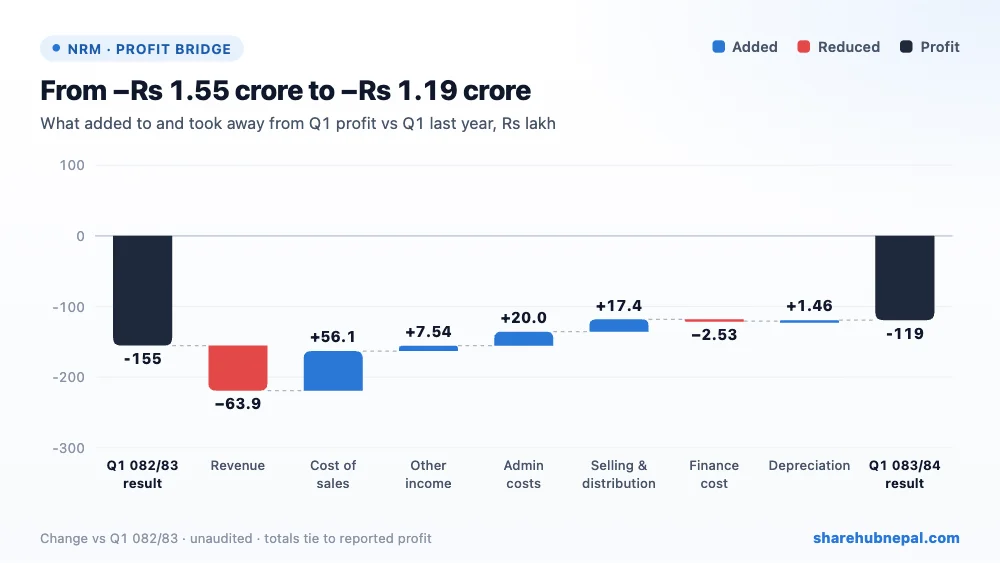
Compared with last year's Q1, lower revenue took away Rs 63.88 lakh and higher interest Rs 2.53 lakh. Lower cost of sales added back Rs 56.09 lakh, lower admin cost Rs 19.98 lakh, lower selling and distribution cost Rs 17.36 lakh, higher other income Rs 7.54 lakh and lower depreciation Rs 1.46 lakh. Net result: loss smaller by Rs 36.03 lakh.
2. Profit through the year
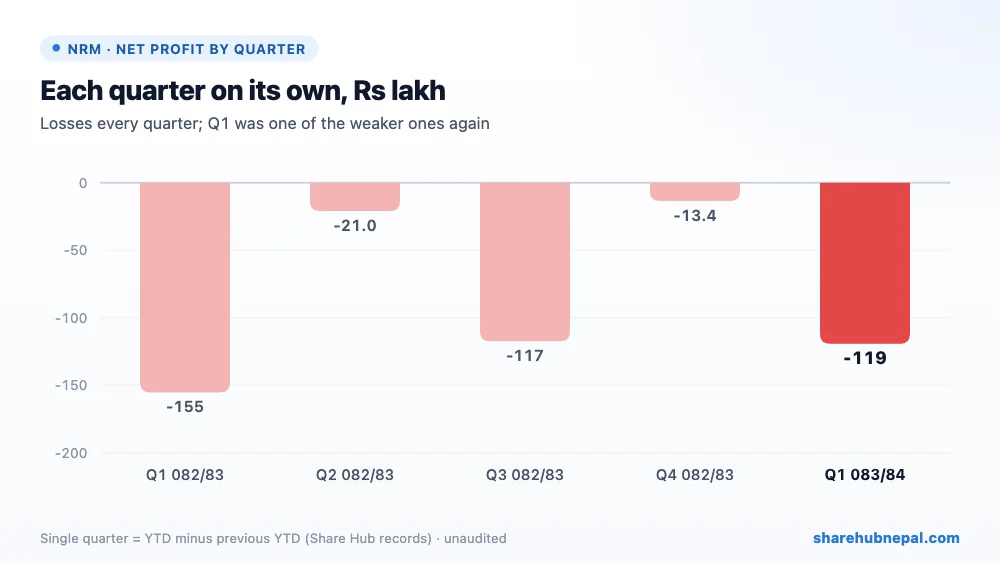
Based on Share Hub's records, NRM lost Rs 1.55 crore in Q1, Rs 20.99 lakh in Q2, Rs 1.17 crore in Q3 and Rs 13.44 lakh in Q4 of 2082/83 (full year Rs 3.07 crore). The company has not made a quarterly profit in the last five quarters.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total borrowings | Rs 242,024,095 | Rs 242,972,590 | −0.39% |
| Trade and other receivables | Rs 503,910,640 | Rs 483,766,495 | +4.16% |
| Cash and cash equivalents | Rs 1,726,270 | Rs 33,727,129 | −94.88% |
| Current assets | Rs 555,384,242 | Rs 567,836,406 | −2.19% |
| Current liabilities | Rs 265,849,604 | Rs 262,289,311 | +1.36% |
| Total equity | Rs 816,560,503 | Rs 828,490,063 | −1.44% |
Borrowings are Rs 24.20 crore (Rs 7.59 crore long-term and Rs 16.61 crore short-term), about the same as at Ashad end. Cash fell sharply to Rs 17.26 lakh from Rs 3.37 crore. The biggest worry is receivables: Rs 50.39 crore is still to be collected, about 43% of total assets and several years of current revenue; the company itself says collecting dues has become hard. Equity is Rs 81.66 crore after an accumulated loss of Rs 54.75 crore, so net worth per share (Rs 84.40) is below the Rs 100 face value.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (quarter, as printed) | Rs -1.23 |
| EPS (annualised) | Rs -4.93 |
| Net worth per share | Rs 84.40 |
| Total assets per share | Rs 122.48 |
| Market price (last trade) | Rs 273 |
| P/B | 3.23x |
| Current ratio | 2.09 |
The last trade in the quarter was Rs 273, which is 3.23 times net worth per share. P/E has no meaning while the company is in loss.
Conclusion
Positives: loss down 23.19%, strong cost cutting, a better gross margin (46.50%), higher other income, and a plan to grow digital media and events.
Watch: revenue down 22.27%, very low cash (Rs 17.26 lakh), large receivables of Rs 50.39 crore, continuing losses, net worth below face value and steady interest cost.
NRM is managing costs well, but its revenue keeps shrinking and money owed to it keeps piling up. Collecting receivables and growing digital income are the keys to a turnaround.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

