













Nyadi Hydropower Ltd – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
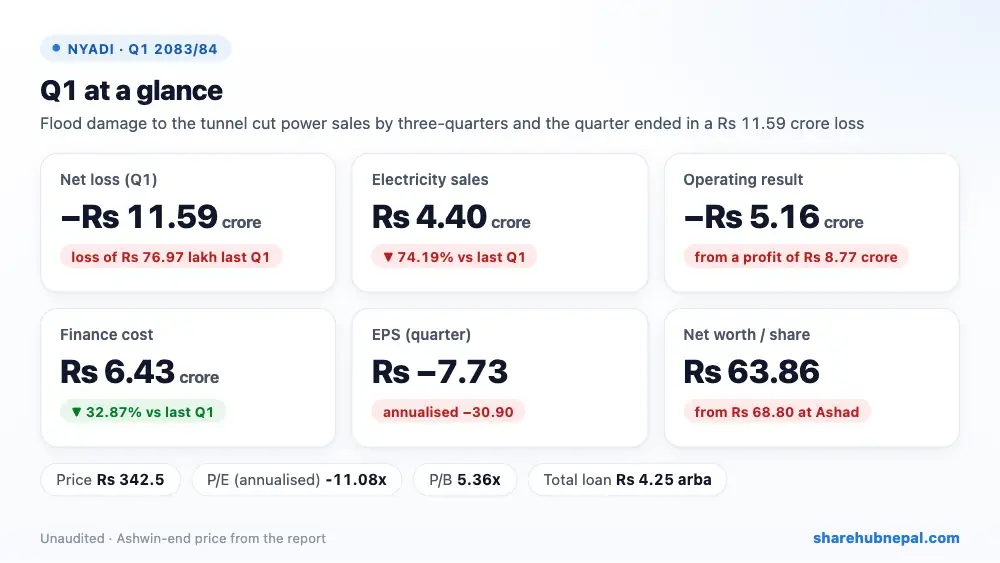
Nyadi Hydropower made a net loss of Rs 11.59 crore in the first quarter of FY 2083/84, against a small loss of Rs 76.97 lakh a year ago. Natural calamities damaged the plant's operating structures and tunnel, so electricity sales fell 74.19% to just Rs 4.40 crore in what should have been the best monsoon quarter. Project costs did not fall, so there was an operating loss of Rs 5.16 crore, and finance cost of Rs 6.43 crore made it worse. The company says the plant restarted in mid-Ashwin 2083 and is now running at normal capacity. EPS is Rs −7.73 for the quarter and net worth per share has fallen to Rs 63.86.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from operations | Rs 43,976,000 | Rs 170,399,000 | −74.19% |
| Project operating expenses | Rs 90,172,000 | Rs 74,779,000 | +20.58% |
| Gross profit / (loss) | −Rs 46,196,000 | Rs 95,620,000 | Turned to loss |
| Other and finance income | Rs 3,610,000 | Rs 329,000 | +997.26% |
| Administrative and other expenses | Rs 9,026,000 | Rs 7,911,000 | +14.09% |
| Net operating profit / (loss) | −Rs 51,612,000 | Rs 87,710,000 | Turned to loss |
| Finance cost | Rs 64,265,000 | Rs 95,736,000 | −32.87% |
| Net profit / (loss) | −Rs 115,877,000 | −Rs 7,697,000 | −1405.48% |
| EPS (quarter) | -7.73 | -0.51 | – |
| Net worth per share | 63.86 | 67.49 | – |
1. Where the profit came from
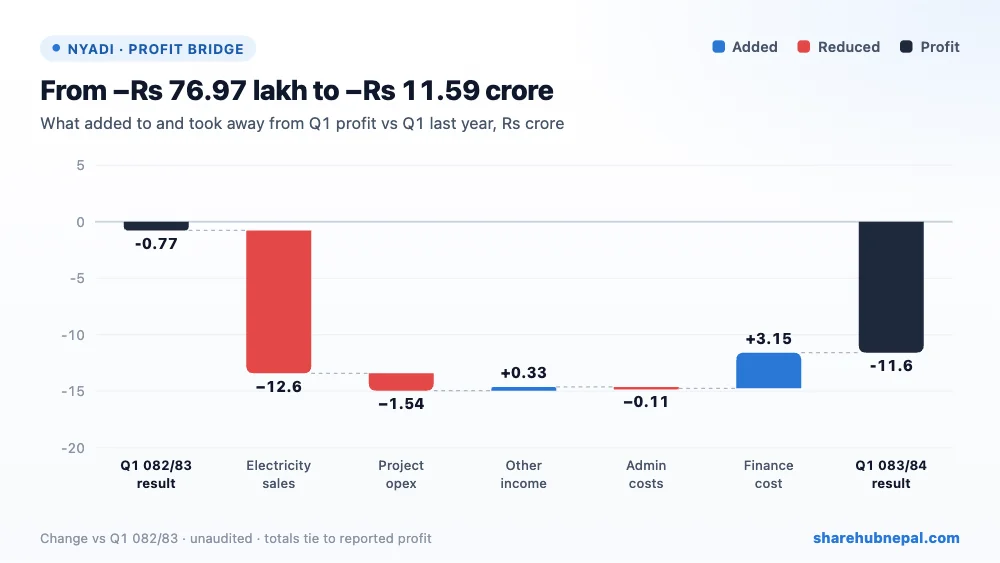
Electricity sales dropped to Rs 4.40 crore from Rs 17.04 crore. Project operating expenses rose to Rs 9.02 crore, so the plant made a gross loss of Rs 4.62 crore. With admin costs of Rs 90.26 lakh and Rs 36.10 lakh of other income, the net operating loss was Rs 5.16 crore, against a profit of Rs 8.77 crore last year. Finance cost fell 32.87% to Rs 6.43 crore, but that was not nearly enough: net loss was Rs 11.59 crore.
2. Profit through the year
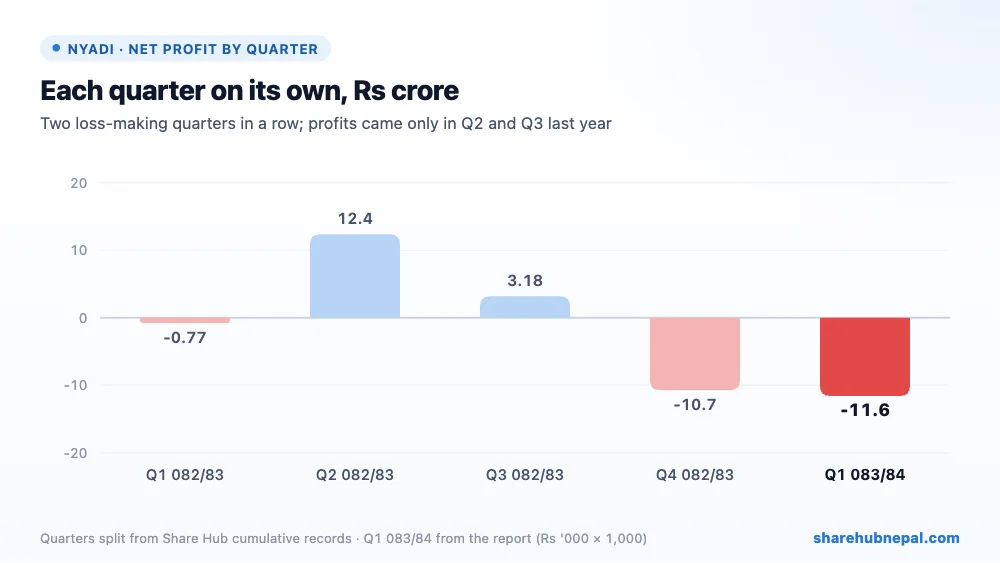
Profit by quarter (Share Hub cumulative records, split into quarters): Q1 082/83: −Rs 76.97 lakh, Q2 082/83: Rs 12.36 crore, Q3 082/83: Rs 3.18 crore, Q4 082/83: −Rs 10.73 crore, Q1 083/84: −Rs 11.59 crore. Nyadi's pattern is unusual: last year Q1 was a loss, Q2 and Q3 were profitable and Q4 was a big loss, giving a full-year profit of only Rs 4.04 crore (EPS Rs 2.70). The report blames NEA's "take and pay" dispatch limits and the delayed Tarikuna substation and 132 kV line, which stop the plant from selling all it can produce.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 5,502,925,000 | Rs 5,525,604,000 | −0.41% |
| Total equity | Rs 957,840,000 | Rs 1,032,067,000 | −7.19% |
| Long-term borrowings | Rs 4,152,027,000 | Rs 4,163,287,000 | −0.27% |
| Current borrowings | Rs 100,000,000 | Rs 100,000,000 | +0.00% |
| Other financial assets | Rs 207,364,000 | Rs 114,911,000 | +80.46% |
| Cash and equivalents | Rs 7,686,000 | Rs 60,389,000 | −87.27% |
| Current assets | Rs 234,717,000 | Rs 199,042,000 | +17.92% |
| Current liabilities | Rs 276,361,000 | Rs 226,168,000 | +22.19% |
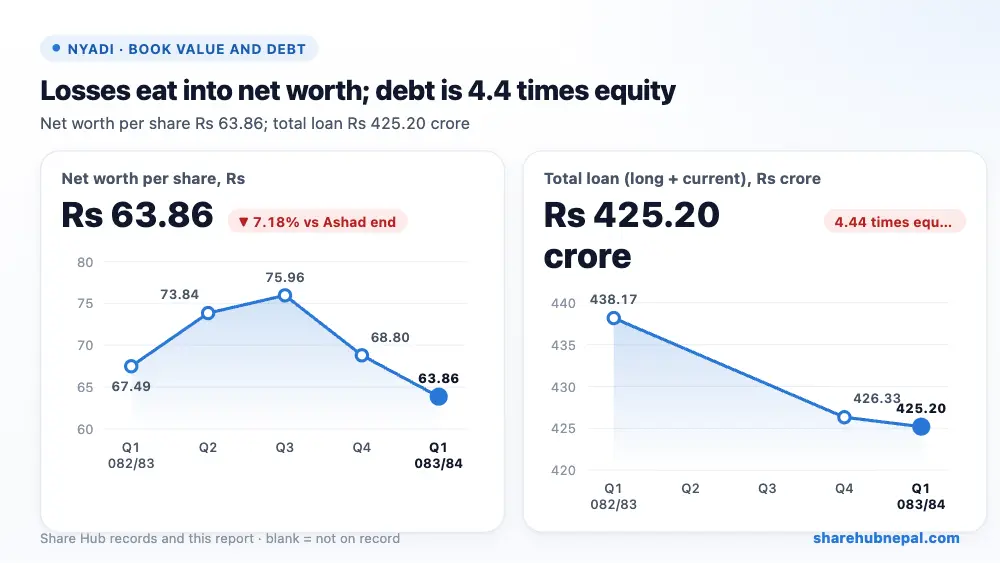
Debt is the big worry. Borrowings total Rs 4.25 arba (including a promoter loan from Butwal Power Company), 4.44 times equity, while equity has fallen to Rs 95.78 crore because of accumulated losses. Cash fell to Rs 76.86 lakh from Rs 6.04 crore and the current ratio is only 0.85, so current liabilities are more than current assets. Equity fell Rs 7.42 crore, which is Rs 4.17 crore less than the loss; the report does not explain the gap.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs -30.90 |
| Net worth per share | Rs 63.86 |
| Market price (Ashwin end) | Rs 342.5 |
| P/E (annualised) | -11.08x |
| P/B | 5.36x |
At the Ashwin-end price of Rs 342.5, the share trades at -11.08 times annualised EPS and 5.36 times net worth per share. With a loss, P/E is not meaningful (the report prints −44.34 on the quarter EPS). The price is about 5.4 times net worth per share, which is very high for a company with losses and heavy debt.
Conclusion
Positives: the plant has restarted and the company says it is running at normal capacity since Ashwin end, finance cost fell 32.87%, and there are no legal cases.
Watch: a Rs 11.59 crore loss in the monsoon quarter, debt at 4.44 times equity, net worth per share far below Rs 100, a current ratio below 1, NEA's "take and pay" limits and the delayed Tarikuna substation, repair costs still to come, and an unexplained Rs 4.17 crore gap between the loss and the fall in equity.
Watch whether Q2 sales recover now that the plant is back, the cost and insurance recovery of the flood repairs, and progress on the Tarikuna substation.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

