













Oriental Hotels Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
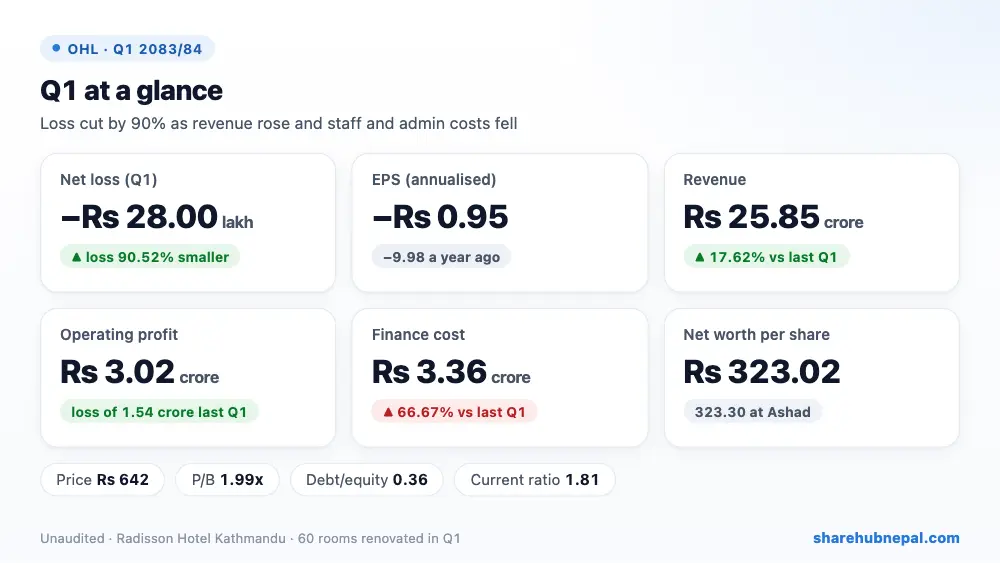
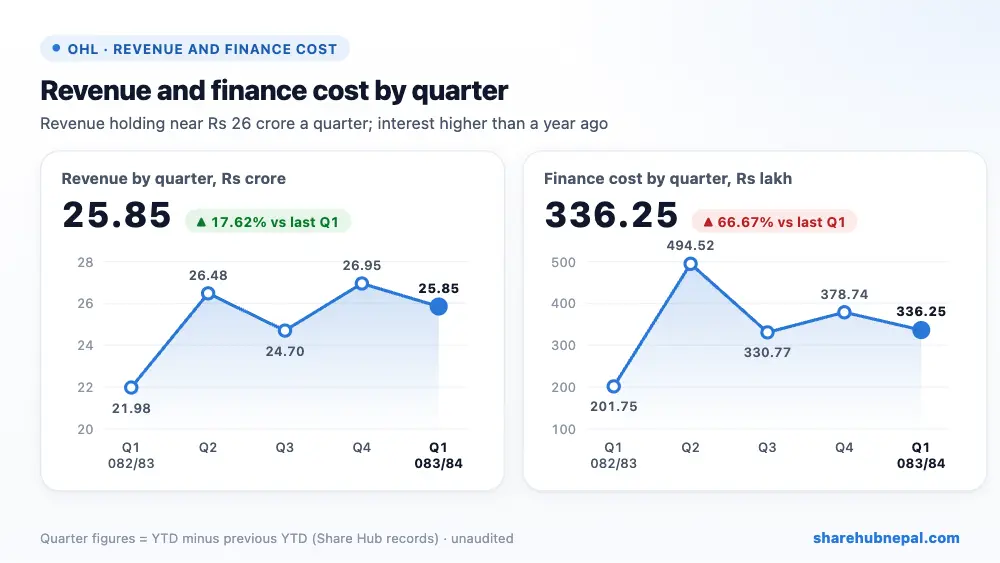
Oriental Hotels, owner of the Radisson Hotel Kathmandu, posted a net loss of Rs 28.00 lakh in the first quarter, 90.52% smaller than the loss of Rs 2.96 crore a year ago. Revenue from operations rose 17.62% to Rs 25.85 crore and the hotel made an operating profit of Rs 3.02 crore, against an operating loss of Rs 1.54 crore last year.
Staff cost fell 20.30% to Rs 7.22 crore and admin cost 25.22% to Rs 4.05 crore. Food and beverage cost rose 38.53% with more business. Two costs kept the hotel in a small loss: depreciation rose 59.52% to Rs 3.19 crore and finance cost rose 66.67% to Rs 3.36 crore, linked to the renovation of 60 rooms on the 3rd, 4th and 5th floors, which was completed at the end of the quarter.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from operations | Rs 258,492,417 | Rs 219,770,105 | +17.62% |
| Other income | Rs 1,504,224 | Rs 2,197,952 | −31.56% |
| Food, beverage and operating supplies | Rs 85,090,069 | Rs 72,578,778 | +17.24% |
| Employee benefits | Rs 72,198,820 | Rs 90,584,320 | −20.30% |
| Administrative and general | Rs 40,549,998 | Rs 54,225,792 | −25.22% |
| Depreciation and amortization | Rs 31,926,890 | Rs 20,014,028 | +59.52% |
| Profit (loss) from operations | Rs 30,230,864 | −Rs 15,434,862 | Turned to profit |
| Finance cost | Rs 33,625,335 | Rs 20,174,524 | +66.67% |
| Net profit (loss) | −Rs 2,800,438 | −Rs 29,555,790 | +90.52% |
| EPS (annualised) | -0.95 | -9.98 | – |
1. Where the profit came from
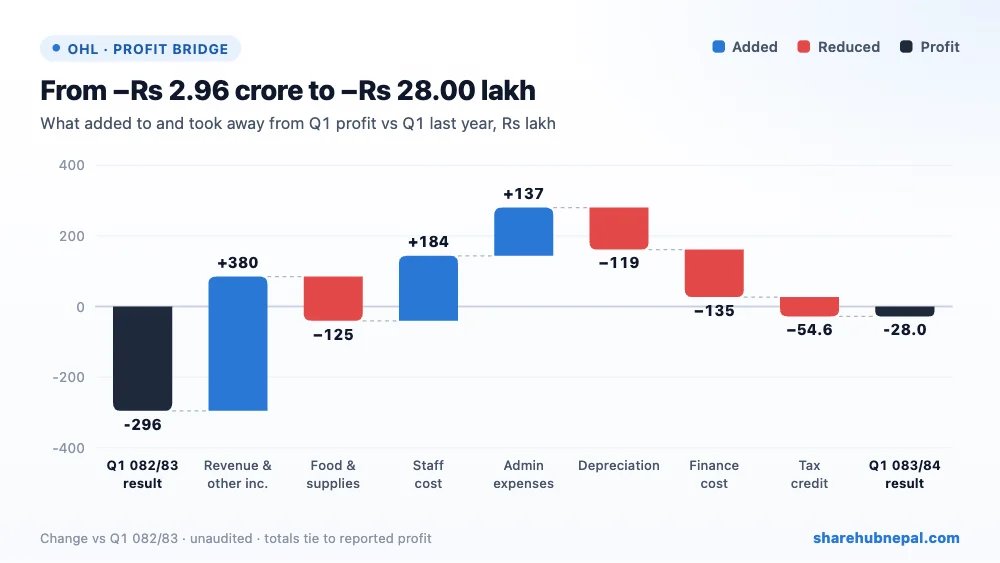
Compared with last year's Q1, higher revenue (net of slightly lower other income) added Rs 3.80 crore, lower staff cost Rs 1.84 crore and lower admin cost Rs 1.37 crore. Higher food and supplies cost took away Rs 1.25 crore, higher finance cost Rs 1.35 crore, higher depreciation Rs 1.19 crore, and a smaller tax credit Rs 54.60 lakh.
2. Profit through the year
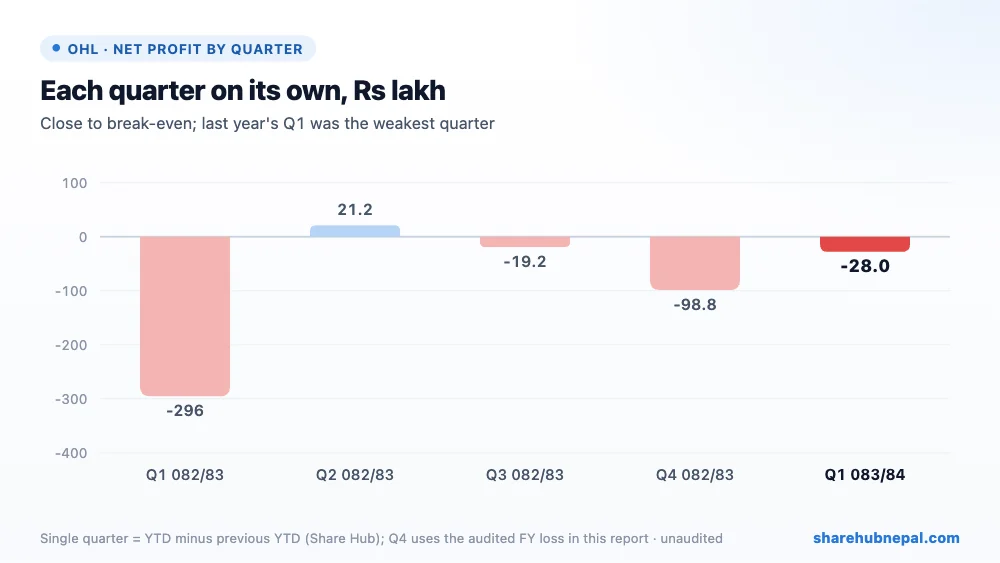
Based on Share Hub's records, single-quarter results in 2082/83 were a loss of Rs 2.96 crore in Q1, a profit of Rs 21.24 lakh in Q2, a loss of Rs 19.20 lakh in Q3 and a loss of about Rs 98.81 lakh in Q4 (using the audited FY loss of Rs 3.92 crore printed in this report; Share Hub's Q4 record shows Rs 4.74 crore). This Q1 is the best first quarter in two years. With the renovated rooms back in use, the company had expected to reach profit.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Loans and borrowings (total) | Rs 1,391,324,986 | Rs 1,368,442,564 | +1.67% |
| Property, plant and equipment | Rs 5,255,818,267 | Rs 5,273,645,266 | −0.34% |
| Capital work-in-progress | Rs 226,655,095 | Rs 184,923,392 | +22.57% |
| Current assets | Rs 676,139,995 | Rs 686,941,098 | −1.57% |
| Current liabilities | Rs 374,470,894 | Rs 527,815,644 | −29.05% |
| Total equity | Rs 3,826,133,864 | Rs 3,829,528,335 | −0.09% |
Total loans are Rs 139.13 crore (Rs 130.24 crore long-term and Rs 8.89 crore current), up from Rs 136.84 crore at Ashad end; long-term loans rose while short-term loans were repaid. Debt is 0.36 times equity. Capital work-in-progress rose to Rs 22.67 crore. Current assets of Rs 67.61 crore are 1.81 times current liabilities. Equity is Rs 382.61 crore, so net worth per share stays high at Rs 323.02.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (quarter, as printed) | Rs -0.24 |
| EPS (annualised) | Rs -0.95 |
| Net worth per share | Rs 323.02 |
| Fixed assets per share | Rs 152.52 |
| Market price (report) | Rs 642 |
| P/B | 1.99x |
| Current ratio | 1.81 |
At Rs 642 the share trades at 1.99 times net worth per share. P/E has no meaning while the company is in loss. The value rests on the hotel's large asset base in Lazimpat and on a return to profit after the renovation.
Conclusion
Positives: revenue up 17.62%, an operating profit instead of a loss, lower staff and admin costs, low debt (0.36x equity), high net worth per share and 60 renovated rooms now back in use.
Watch: still a net loss, finance cost up 66.67% and depreciation up 59.52%, rising long-term loans, and outside risks the company lists (Gen Z protests, wars in the Middle East and Ukraine, new hotels competing for guests).
Oriental Hotels is close to break-even: the business is growing and costs are under control, but interest and depreciation from the renovation still eat the operating profit. Q2 will show whether the renovated rooms lift it into profit.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

