













Panchakanya Mai Hydropower Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
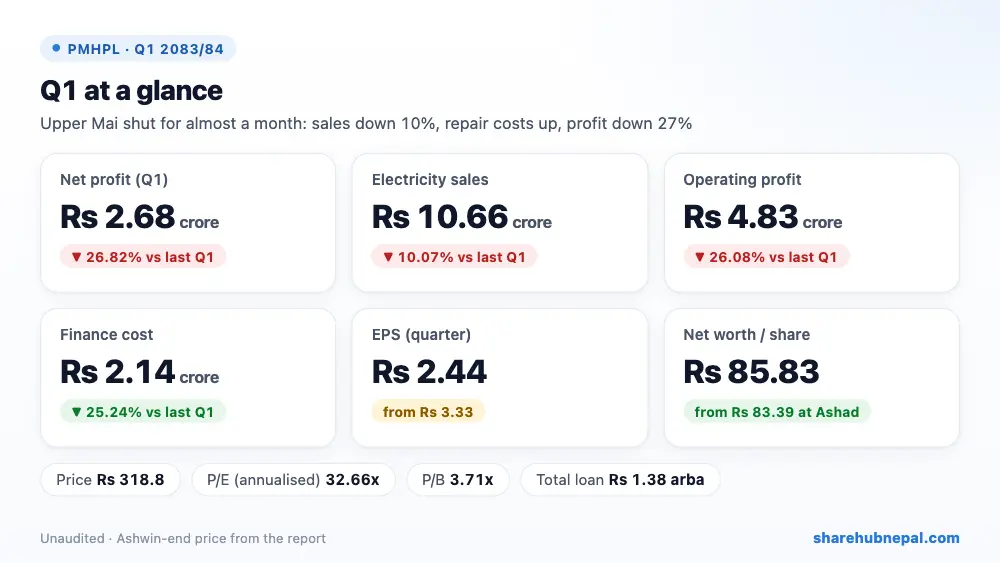
Summary
Panchakanya Mai Hydropower earned Rs 2.68 crore in the first quarter, down 26.82% from Rs 3.67 crore a year ago. Its Upper Mai plant was shut from 21 Bhadra to 16 Ashwin 2083 to repair a leak in the penstock pipe, so electricity sales fell 10.07% to Rs 10.66 crore and plant expenses rose 33.47% to Rs 2.62 crore. Lower interest rates cut finance cost by 25.24%, which saved part of the profit. The management note says profit increased; in fact it fell. Quarter EPS is Rs 2.44 (Rs 9.76 annualised).
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sales | Rs 106,624,203 | Rs 118,568,107 | −10.07% |
| Cost of sales | Rs 26,171,113 | Rs 19,608,679 | +33.47% |
| Other income | Rs 377,214 | Rs 377,214 | +0.00% |
| Operating profit | Rs 48,294,890 | Rs 65,334,773 | −26.08% |
| Finance cost | Rs 21,392,447 | Rs 28,616,722 | −25.24% |
| Income tax | Rs 58,841 | Rs 35,048 | +67.89% |
| Net profit | Rs 26,843,601 | Rs 36,683,002 | −26.82% |
| EPS (quarter) | 2.44 | 3.33 | – |
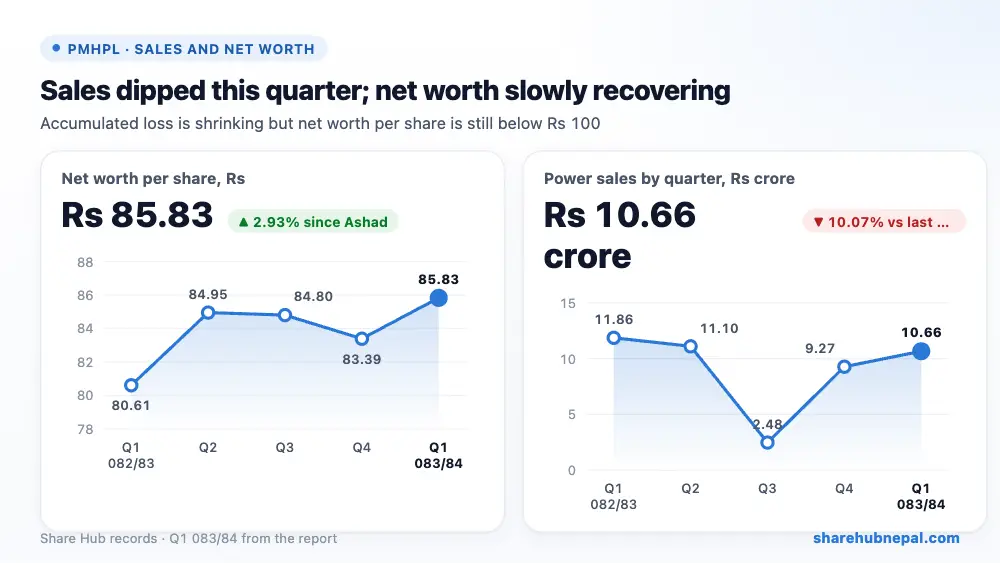
| Net worth per share | 85.83 | 80.61 | – |
1. Where the profit came from
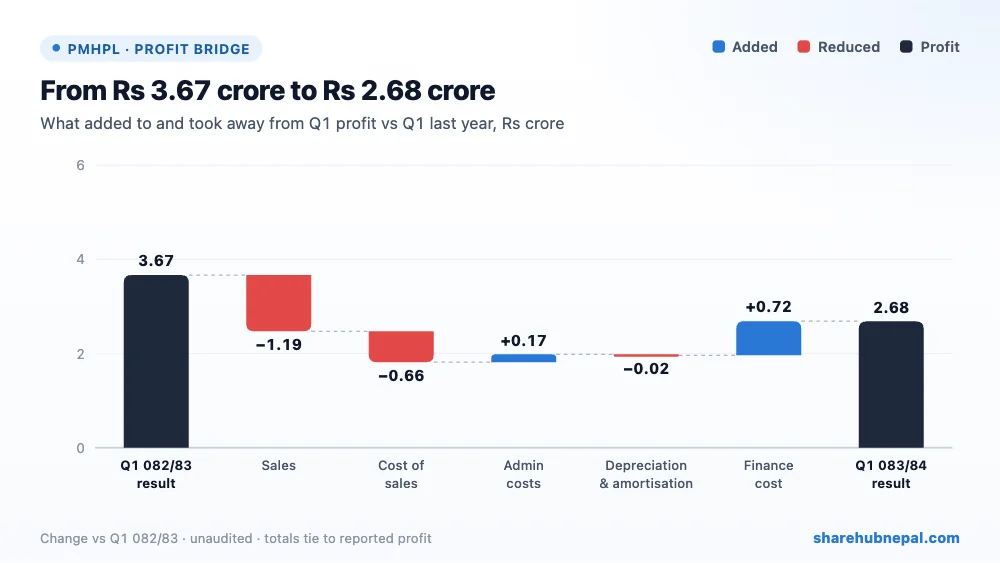
Lower sales took away Rs 1.19 crore and higher plant (repair) expenses Rs 65.62 lakh. Finance cost fell by Rs 72.24 lakh and admin cost by Rs 16.69 lakh. Depreciation (Rs 2.97 crore) and interest (Rs 2.14 crore) still take almost half of sales. The report prints EPS of Rs 2.44 as annualised, but that is the quarter figure; annualised it is Rs 9.76.
2. Profit through the year
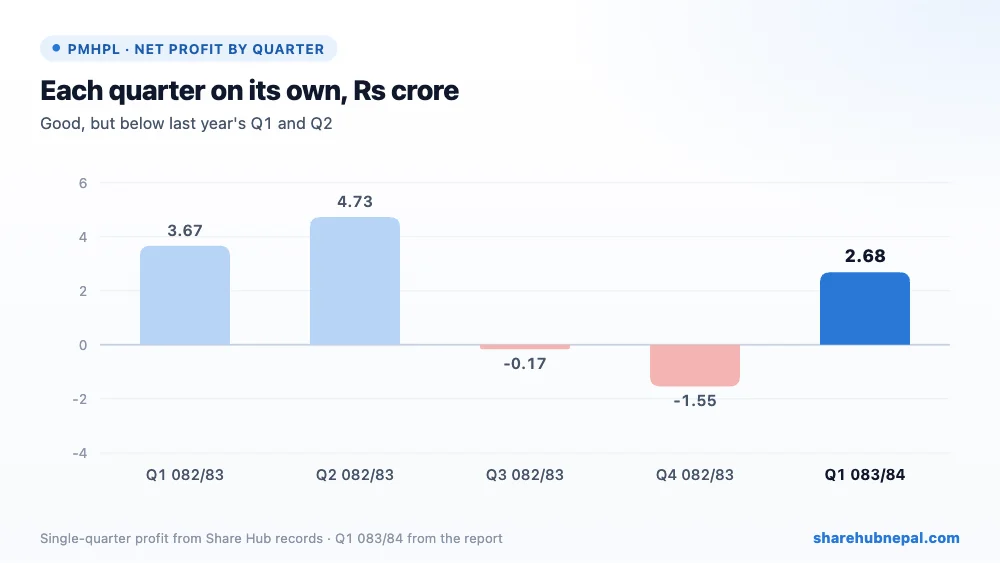
Profit by quarter (Share Hub records): Q1 082/83: Rs 3.67 crore, Q2 082/83: Rs 4.73 crore, Q3 082/83: −Rs 17.01 lakh, Q4 082/83: −Rs 1.55 crore, Q1 083/84: Rs 2.68 crore. Last year Q3 and Q4 were losses (dry season and high interest), and FY 2082/83 EPS was Rs 6.07.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 2,465,191,844 | Rs 2,484,348,929 | −0.77% |
| Total equity | Rs 944,161,258 | Rs 917,317,656 | +2.93% |
| Long-term borrowings | Rs 1,376,203,683 | Rs 1,408,313,261 | −2.28% |
| Current borrowings | Rs 0 | Rs 4,000,000 | −100.00% |
| Cash and equivalents | Rs 4,341,787 | Rs 5,510,619 | −21.21% |
The company repaid its Rs 16.35 crore unsecured loan and Rs 40 lakh short-term loan, but took more secured loan, so total borrowing is Rs 137.62 crore against Rs 140.83 crore at Ashad end. That is still about 1.5 times equity of Rs 94.42 crore. The accumulated loss is down to Rs 15.58 crore, and net worth per share is Rs 85.83, still below face value. Cash is only Rs 43.42 lakh and the current ratio is 0.74.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 9.76 |
| Net worth per share | Rs 85.83 |
| Market price (Ashwin end) | Rs 318.8 |
| P/E (annualised) | 32.66x |
| P/B | 3.71x |
At the Ashwin-end price of Rs 318.8, the share trades at 32.66 times annualised EPS and 3.71 times net worth per share. On FY 2082/83 EPS of Rs 6.07 the P/E is about 52.5x.
Conclusion
Positives: lower interest cost, unsecured loan repaid, accumulated loss shrinking, both plants running again.
Watch: plant shutdown and repair costs, profit down 27%, net worth below face value, low cash and current ratio, and a management note that misstates the profit trend.
A weaker Q1 caused by a one-time repair. If both plants run well through the rest of the year, lower interest should help, but the company still carries a lot of debt and past losses.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

