













Rapti Hydro and General Construction Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
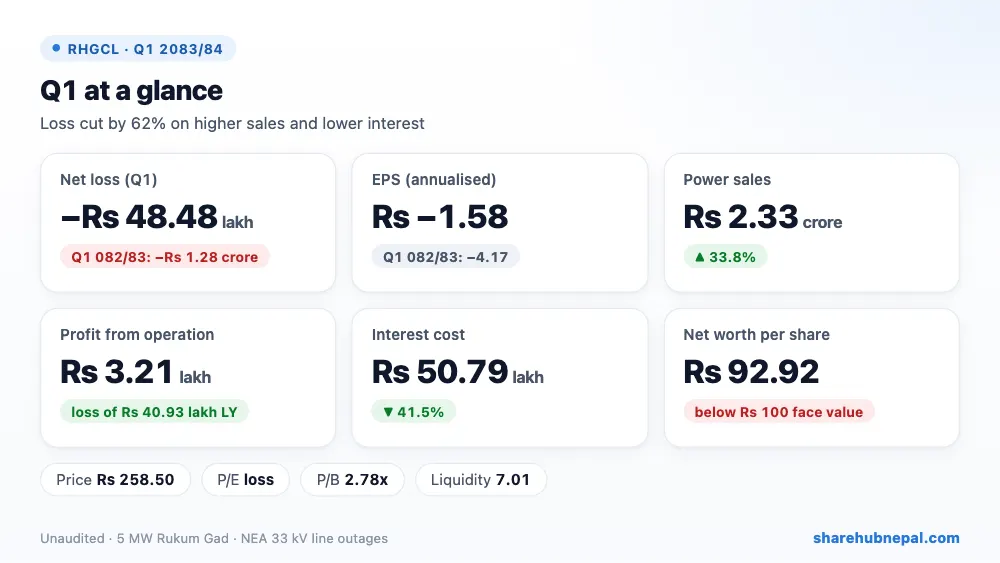
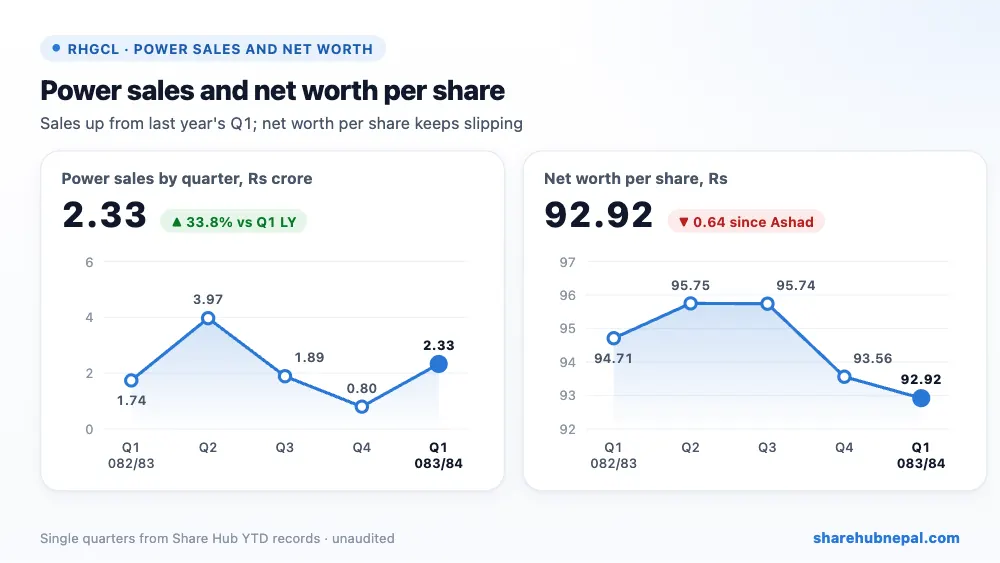
Rapti Hydro and General Construction, which runs the 5 MW Rukum Gad plant in Rukum East, made a net loss of Rs 48.48 lakh in the first quarter of 2083/84, much smaller than the Rs 1.28 crore loss a year ago. Annualised EPS is Rs −1.58 (−4.17 a year ago) and net worth per share is Rs 92.92, still below the Rs 100 face value.
Power sales rose 33.83% to Rs 2.33 crore and the plant made a small operating profit of Rs 3.21 lakh (a loss of Rs 40.93 lakh last year). Interest fell 41.46% to Rs 50.79 lakh, but it is still bigger than operating profit, so the quarter ended in a loss. The company says frequent outages on NEA's 33 kV Rukum West–Salyan–Dang line keep hurting generation.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue | Rs 23,260,271 | Rs 17,380,005 | +33.83% |
| Generation expenses | Rs 7,875,245 | Rs 5,052,703 | +55.86% |
| Depreciation | Rs 15,680,619 | Rs 15,677,703 | +0.02% |
| Other income | Rs 1,104,783 | Rs 0 | – |
| Administrative expenses | Rs 488,153 | Rs 742,889 | −34.29% |
| Profit from operation | Rs 321,036 | −Rs 4,093,291 | Turned to profit |
| Finance costs | Rs 5,078,731 | Rs 8,675,346 | −41.46% |
| Net profit (loss) | −Rs 4,848,140 | −Rs 12,776,549 | +62.05% |
1. Where the profit came from
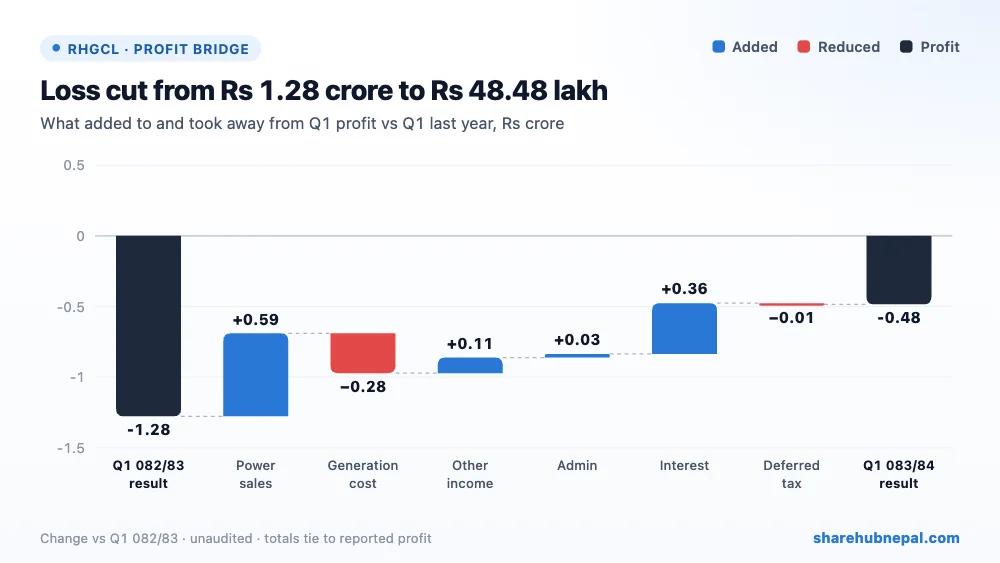
Against Q1 last year, higher power sales added Rs 58.80 lakh, lower interest Rs 35.97 lakh and other income Rs 11.05 lakh. Higher generation cost took away Rs 28.23 lakh. Depreciation was flat. Net: the loss shrank by Rs 79.28 lakh.
2. Profit through the year
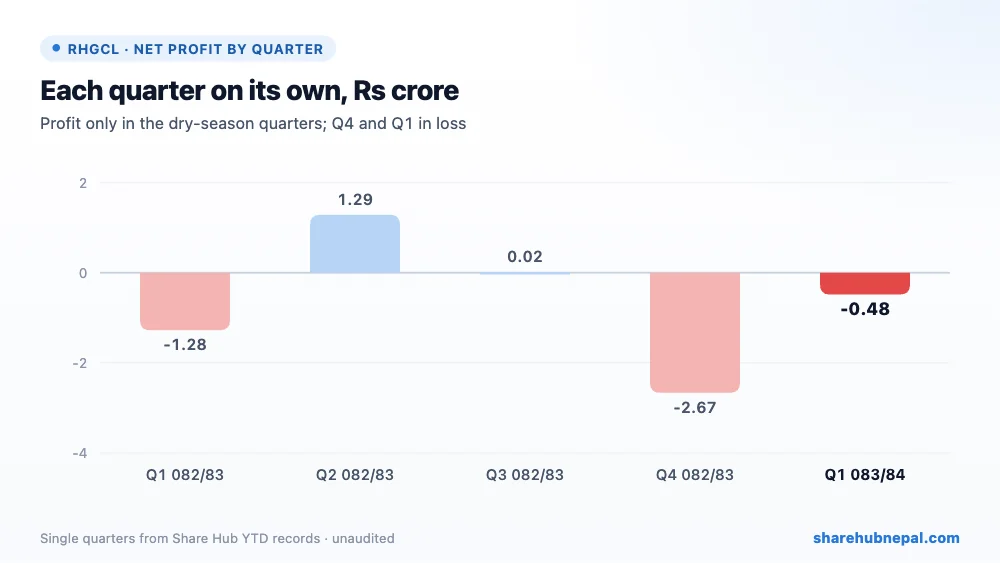
RHGCL's pattern is unusual for a hydro plant: last year it made a loss in Q1 (Rs 1.28 crore), small profits in Q2 (Rs 1.29 crore) and Q3, then a big loss in Q4 (Rs 2.67 crore, year-end depreciation and interest), ending 2082/83 with a loss of Rs 2.64 crore (EPS −2.16). This Q1 is the best first quarter so far, but the company still has not shown a full year of profit.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Property, plant and equipment | Rs 1,532,662,543 | Rs 1,548,515,421 | −1.02% |
| Trade receivables (NEA) | Rs 51,373,665 | Rs 43,998,094 | +16.76% |
| Cash and cash equivalents | Rs 34,309,960 | Rs 36,531,878 | −6.08% |
| Long-term borrowings | Rs 314,289,396 | Rs 316,400,901 | −0.67% |
| Short-term borrowings | Rs 28,710,600 | Rs 27,032,000 | +6.21% |
| Total equity | Rs 1,138,858,125 | Rs 1,146,635,185 | −0.68% |
Debt is moderate: long-term loans Rs 31.43 crore and short-term Rs 2.87 crore (about 0.30 times equity), plus Rs 27.08 crore of other long-term financial liabilities. Liquidity is good (ratio 7.01). Accumulated losses keep other equity negative (−Rs 8.67 crore), which is why net worth per share is below Rs 100. NEA owed Rs 5.14 crore at Ashwin end (the account still has to be reconciled with NEA). The Electricity Regulatory Commission has approved a 1:0.251411 right share (the AGM had asked for 1:0.4661) to repay long-term loans; the SEBON application is in process.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised, report) | Rs −1.58 |
| EPS (quarter, derived) | Rs −0.40 |
| Net worth per share | Rs 92.92 |
| Total assets per share (report) | Rs 143.65 |
| Market price (Q1 close) | Rs 258.50 |
| P/E | loss (report −163.37) |
| P/B | 2.78x |
| Liquidity ratio | 7.01 |
The Q1 closing price was Rs 258.50 (range Rs 237 to Rs 287.30). With a loss there is no meaningful P/E. The price is 2.78 times net worth per share, which is high for a company that has not yet made a yearly profit.
Conclusion
Positives: higher power sales, a small operating profit, interest down 41%, strong liquidity, and an approved right share to cut loans.
Watch: interest still larger than operating profit, NEA line outages, net worth below face value, the right share (more shares), and the NEA receivable that still needs reconciling.
RHGCL is moving in the right direction, with a smaller loss and lower interest, but a 5 MW plant with its debt load needs steady generation and the right-share money before it can turn a yearly profit.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

