













Ridge Line Energy Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
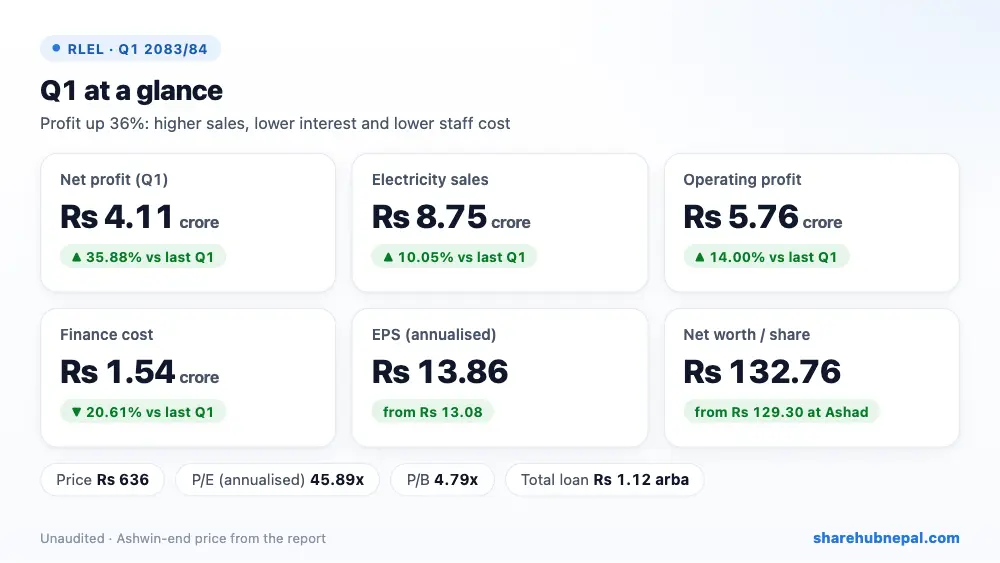
Ridge Line Energy earned Rs 4.11 crore in the first quarter, up 35.88% from Rs 3.02 crore a year ago. Electricity sales rose 10.05% to Rs 8.75 crore. Finance cost fell 20.61% to Rs 1.54 crore as the loan was paid down and rates eased, and employee costs fell by more than half. Cost of sales rose 56.49% to Rs 83.15 lakh but did not stop the gain. The company still pays no income tax. Annualised EPS is Rs 13.86 against Rs 13.08 a year ago, on 28% more shares.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sales | Rs 87,513,939 | Rs 79,522,529 | +10.05% |
| Cost of sales | Rs 8,314,567 | Rs 5,313,087 | +56.49% |
| Other income | Rs 0 | Rs 7,808 | −100.00% |
| Operating profit | Rs 57,569,178 | Rs 50,499,308 | +14.00% |
| Finance cost | Rs 15,355,024 | Rs 19,340,797 | −20.61% |
| Income tax | Rs 0 | Rs 1,952 | −100.00% |
| Net profit | Rs 41,072,824 | Rs 30,228,036 | +35.88% |
| EPS (annualised) | 13.86 | 13.08 | – |
| Net worth per share | 132.76 | 126.21 | – |
1. Where the profit came from
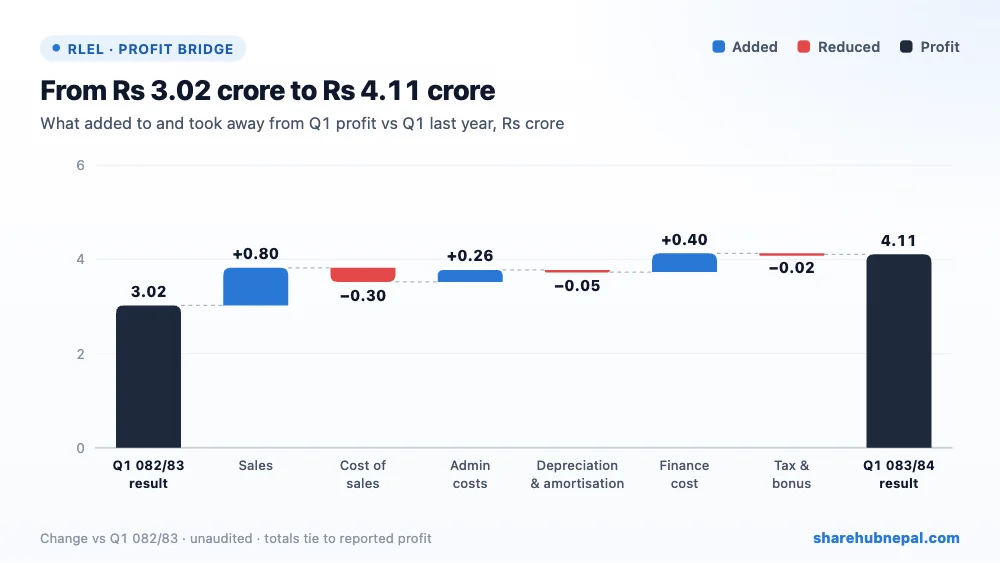
Profit rose by Rs 1.08 crore. Higher sales added Rs 79.91 lakh, lower finance cost Rs 39.86 lakh and lower admin and staff costs Rs 25.59 lakh. Higher cost of sales took away Rs 30.01 lakh and depreciation Rs 4.71 lakh; bonus and CSR provisions rose with profit.
2. Profit through the year
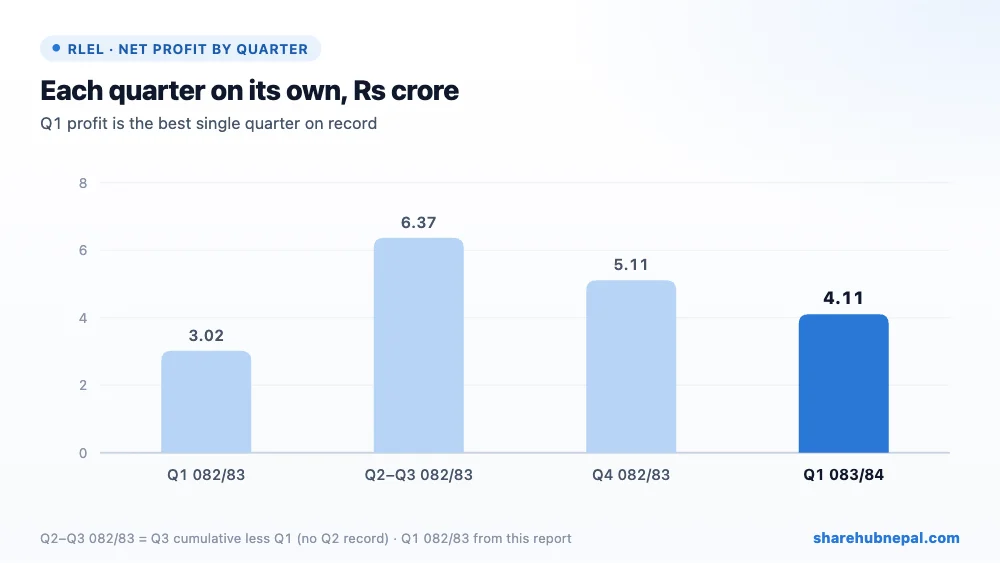
Profit by quarter (Share Hub records): Q1 082/83: Rs 3.02 crore, Q2–Q3 082/83: Rs 6.37 crore, Q4 082/83: Rs 5.11 crore, Q1 083/84: Rs 4.11 crore. Audited FY 2082/83 profit was Rs 14.39 crore (EPS Rs 12.15). This Q1 alone is 29% of that.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 2,696,851,828 | Rs 2,666,602,069 | +1.13% |
| Total equity | Rs 1,573,252,904 | Rs 1,532,206,085 | +2.68% |
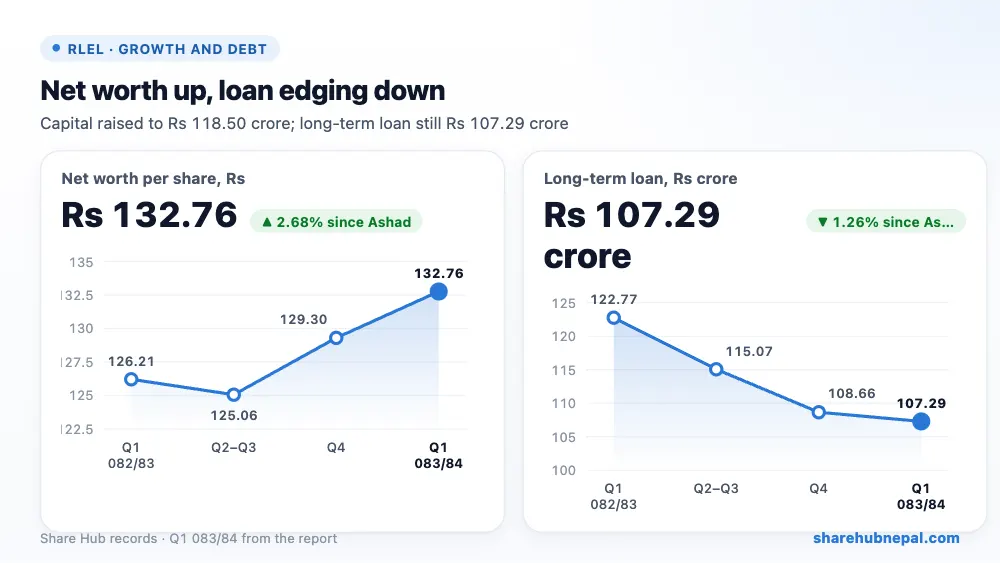
| Long-term borrowings | Rs 1,072,934,552 | Rs 1,086,606,194 | −1.26% |
| Current borrowings | Rs 44,042,724 | Rs 38,583,377 | +14.15% |
| Cash and equivalents | Rs 108,954,892 | Rs 62,855,190 | +73.34% |
Share capital rose to Rs 118.50 crore from Rs 92.43 crore a year ago, and part of the money went into associates (Rs 14.89 crore) and capital work in progress (Rs 7.96 crore), so the company is building or investing in new projects. The long-term loan is Rs 107.29 crore plus Rs 4.40 crore short-term, against equity of Rs 157.33 crore. Cash rose to Rs 10.90 crore and the current ratio is 3.47.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 13.86 |
| Net worth per share | Rs 132.76 |
| Market price (Ashwin end) | Rs 636 |
| P/E (annualised) | 45.89x |
| P/B | 4.79x |
At the Ashwin-end price of Rs 636, the share trades at 45.89 times annualised EPS and 4.79 times net worth per share. Using the audited FY 2082/83 EPS of Rs 12.15, the P/E is about 52x.
Conclusion
Positives: profit up 36%, sales up 10%, finance cost down 21%, stronger cash, no tax.
Watch: still a large loan (Rs 111.69 crore in all), new investments that do not earn yet, rising cost of sales, and a high P/E.
A strong quarter with real growth in sales and lower interest. The next step to watch is whether the new investments start earning.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

