













Reliance Spinning Mills Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
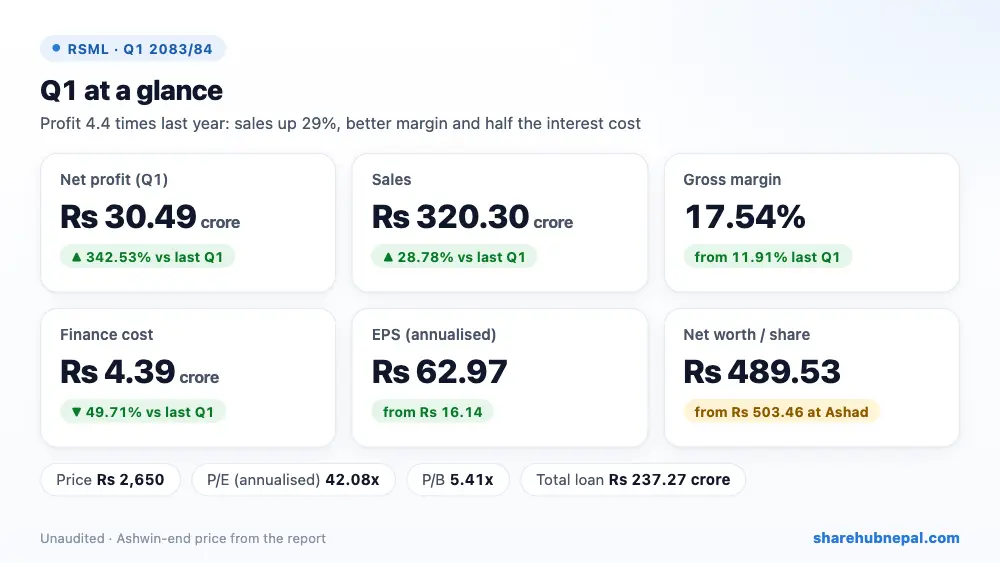
Reliance Spinning Mills earned Rs 30.49 crore in the first quarter, 4.4 times the Rs 6.89 crore of a year ago (+342.53%). Sales rose 28.78% to Rs 320.30 crore and the gross margin improved to 17.54% from 11.91%, so gross profit almost doubled to Rs 56.17 crore. Finance cost halved to Rs 4.39 crore after loans were cut and rates fell. Annualised EPS is Rs 62.97 against Rs 16.14.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from operations | Rs 3,202,992,062 | Rs 2,487,121,154 | +28.78% |
| Cost of sales | Rs 2,641,312,157 | Rs 2,190,841,788 | +20.56% |
| Other income | Rs 12,950,613 | Rs 8,526,009 | +51.90% |
| Operating profit | Rs 405,715,043 | Rs 169,151,681 | +139.85% |
| Finance cost | Rs 43,872,786 | Rs 87,235,262 | −49.71% |
| Income tax | Rs 56,982,398 | Rs 13,026,032 | +337.45% |
| Net profit | Rs 304,859,860 | Rs 68,890,387 | +342.53% |
| EPS (annualised) | 62.97 | 16.14 | – |
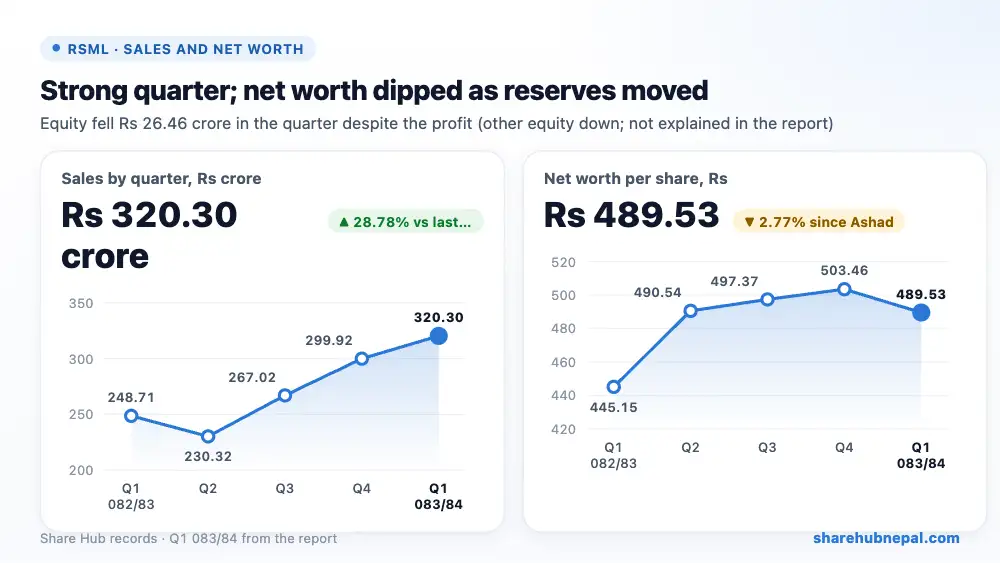
| Net worth per share | 489.53 | 445.15 | – |
1. Where the profit came from
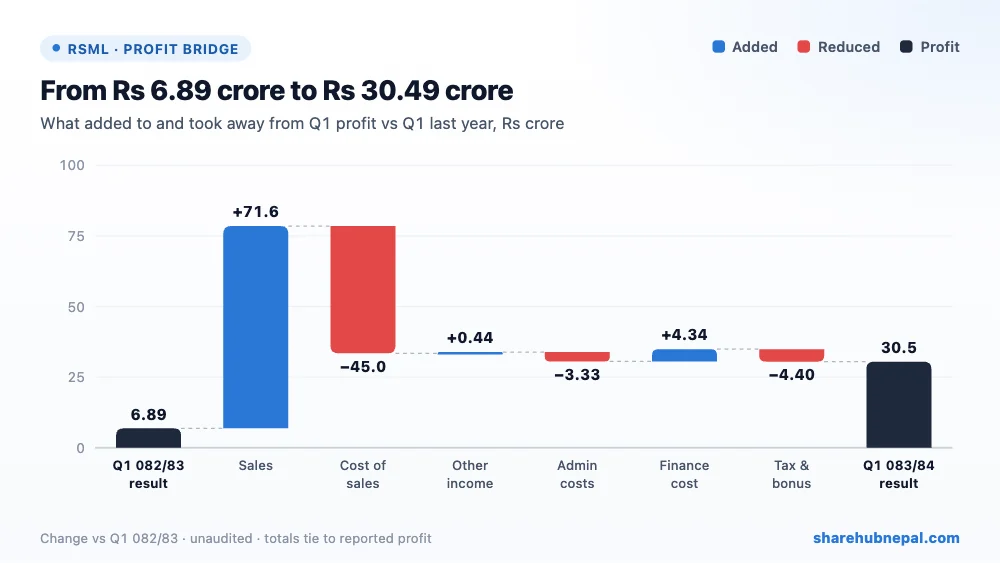
Higher sales added Rs 71.59 crore and higher cost of sales took away Rs 45.05 crore, a net gain of Rs 26.54 crore at the gross level. Lower finance cost added Rs 4.34 crore and other income Rs 44.25 lakh. Selling, admin and other costs rose Rs 3.33 crore and tax Rs 4.40 crore. Management notes that petroleum prices and shipping delays are risks, and that a case over the dedicated-line electricity charge with NEA is still pending in court.
2. Profit through the year
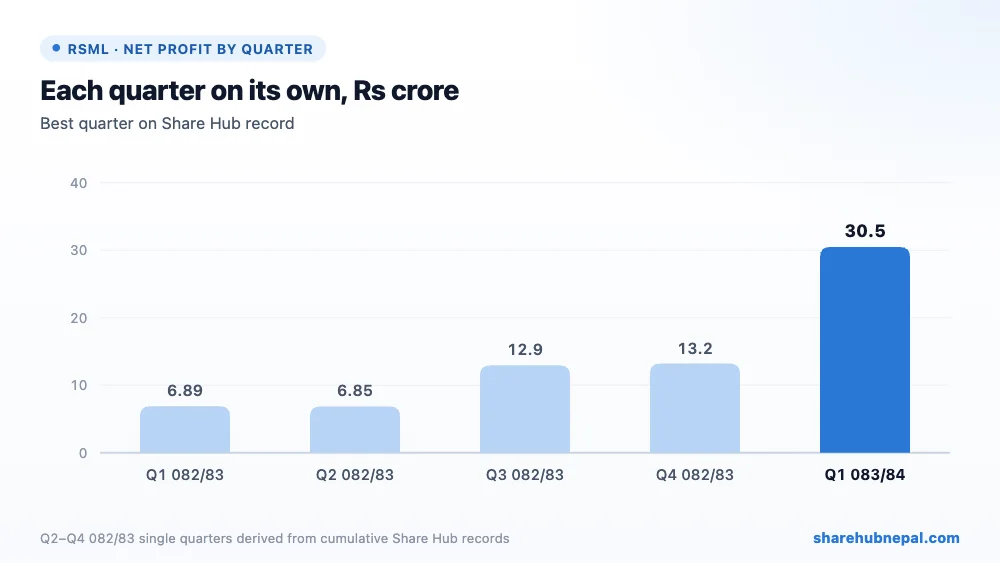
Profit by quarter (Share Hub records): Q1 082/83: Rs 6.89 crore, Q2 082/83: Rs 6.85 crore, Q3 082/83: Rs 12.95 crore, Q4 082/83: Rs 13.21 crore, Q1 083/84: Rs 30.49 crore. Audited FY 2082/83 profit was Rs 40.20 crore, so this one quarter is already three-quarters of last year's total.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 14,265,775,569 | Rs 13,997,825,626 | +1.91% |
| Total equity | Rs 9,301,059,820 | Rs 9,565,664,208 | −2.77% |
| Long-term borrowings | Rs 1,737,379,032 | Rs 1,881,125,016 | −7.64% |
| Current borrowings | Rs 635,363,211 | Rs 568,447,375 | +11.77% |
| Cash and equivalents | Rs 74,402,546 | Rs 494,208,376 | −84.95% |
Total borrowing is Rs 237.27 crore (Rs 173.74 crore long-term and Rs 63.54 crore short-term), down from Rs 458.08 crore a year ago and Rs 244.96 crore at Ashad end. Cash fell from Rs 49.42 crore to Rs 7.44 crore while capital work in progress rose to Rs 41.47 crore, so the company is spending on new capacity. Other financial liabilities rose to Rs 175.49 crore. Equity fell by Rs 26.46 crore despite the profit, which the report does not explain (possibly a dividend payable).
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 62.97 |
| Net worth per share | Rs 489.53 |
| Market price (Ashwin end) | Rs 2650 |
| P/E (annualised) | 42.08x |
| P/B | 5.41x |
At the Ashwin-end price of Rs 2650, the share trades at 42.08 times annualised EPS and 5.41 times net worth per share. On audited FY 2082/83 EPS of about Rs 21 the P/E would be about 125x, so the price already assumes the strong quarter continues.
Conclusion
Positives: sales up 29%, margin up, finance cost halved, debt down sharply, new capacity being built.
Watch: unexplained fall in equity, cash down to Rs 7.44 crore, higher other liabilities, raw-material and shipping risks, NEA electricity dispute, and a high P/B.
An excellent quarter for Reliance Spinning. If margins hold, FY 2083/84 could be far better than last year; watch cash and the equity movement.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

