













Ru Ru Jalbidhyut Pariyojana Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
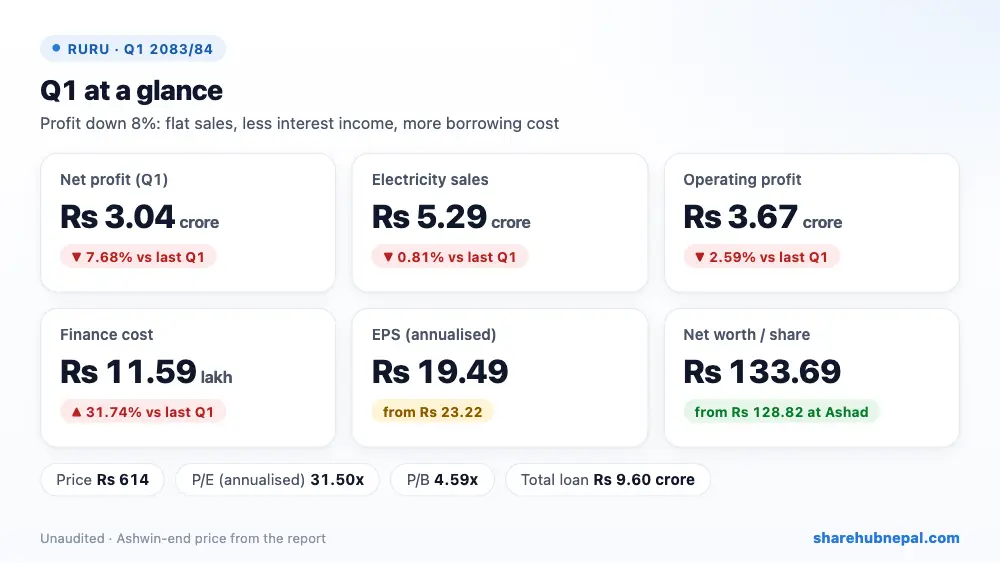
Ru Ru Jalbidhyut (Upper Hugdi Khola) earned Rs 3.04 crore in the first quarter, down 7.68% from Rs 3.29 crore a year ago. Sales were almost flat at Rs 5.29 crore (down 0.81%). The fall came from below the gross profit line: interest income dropped from Rs 6.48 lakh to Rs 15,896 as cash was used for investments, finance cost rose 31.74% to Rs 11.59 lakh, admin cost rose 17.90%, and tax was higher. Annualised EPS is Rs 19.49 against Rs 23.22 a year ago (the share count also rose 10% after a bonus issue).
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sales | Rs 52,889,873 | Rs 53,319,578 | −0.81% |
| Cost of sales | Rs 12,208,012 | Rs 12,262,816 | −0.45% |
| Other income | Rs 19,469 | Rs 648,337 | −97.00% |
| Operating profit | Rs 36,711,019 | Rs 37,685,749 | −2.59% |
| Finance cost | Rs 1,159,121 | Rs 879,850 | +31.74% |
| Income tax | Rs 4,448,408 | Rs 3,767,765 | +18.06% |
| Net profit | Rs 30,408,031 | Rs 32,937,385 | −7.68% |
| EPS (annualised) | 19.49 | 23.22 | – |
| Net worth per share | 133.69 | 143.28 | – |
1. Where the profit came from
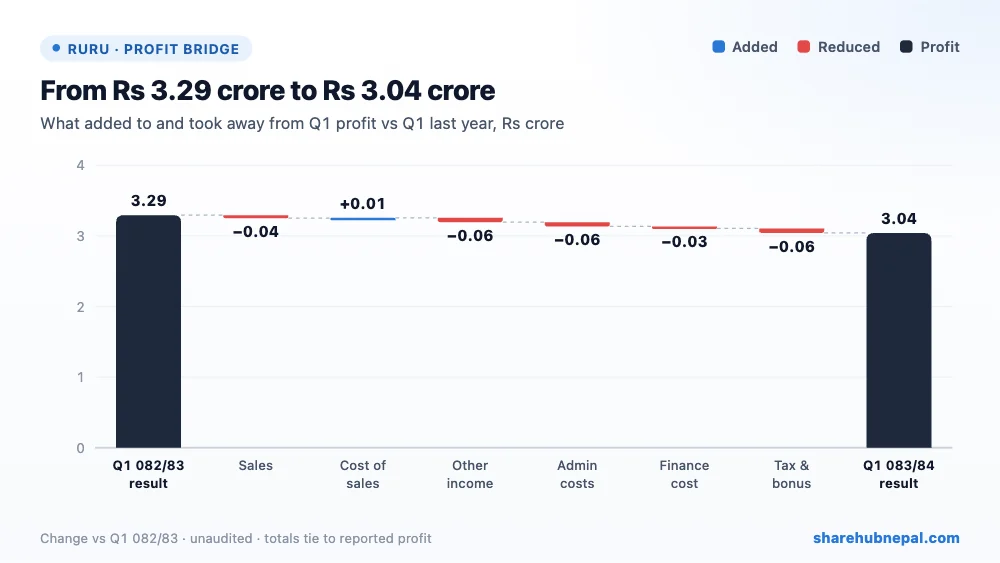
Profit fell by Rs 25.29 lakh. Lower finance income took away Rs 6.32 lakh, higher admin cost Rs 6.03 lakh, higher finance cost Rs 2.79 lakh, lower sales Rs 4.30 lakh and higher tax and bonus Rs 6.43 lakh. Cost of sales was almost unchanged. NEA still owes the company Rs 7.59 crore of the extra 20% posted-rate payment under its power purchase agreement.
2. Profit through the year
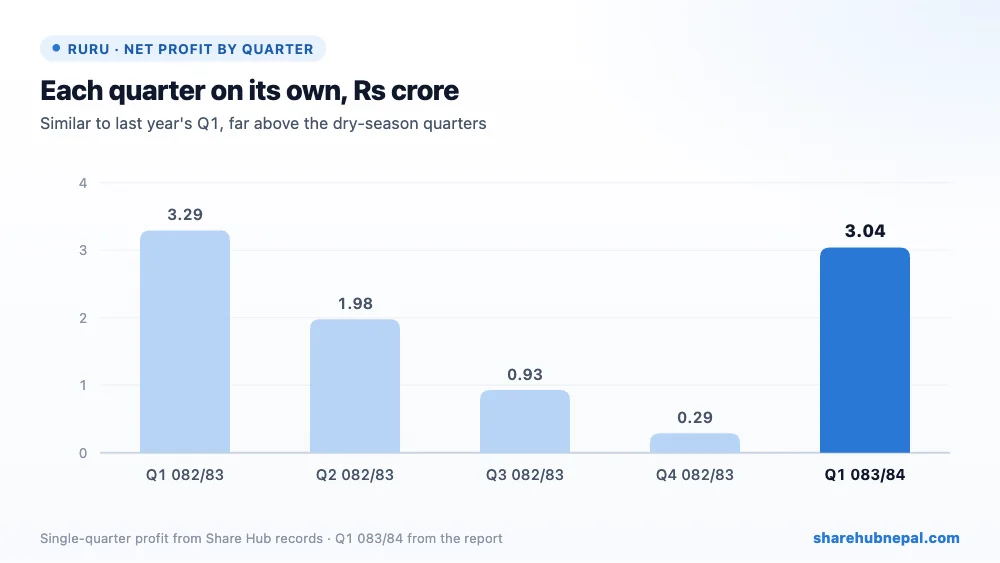
Profit by quarter (Share Hub records): Q1 082/83: Rs 3.29 crore, Q2 082/83: Rs 1.98 crore, Q3 082/83: Rs 93.00 lakh, Q4 082/83: Rs 28.77 lakh, Q1 083/84: Rs 3.04 crore. Last year profit fell each quarter after the monsoon (Q4 only Rs 28.77 lakh); FY 2082/83 EPS was Rs 10.40.
3. Debt and balance sheet
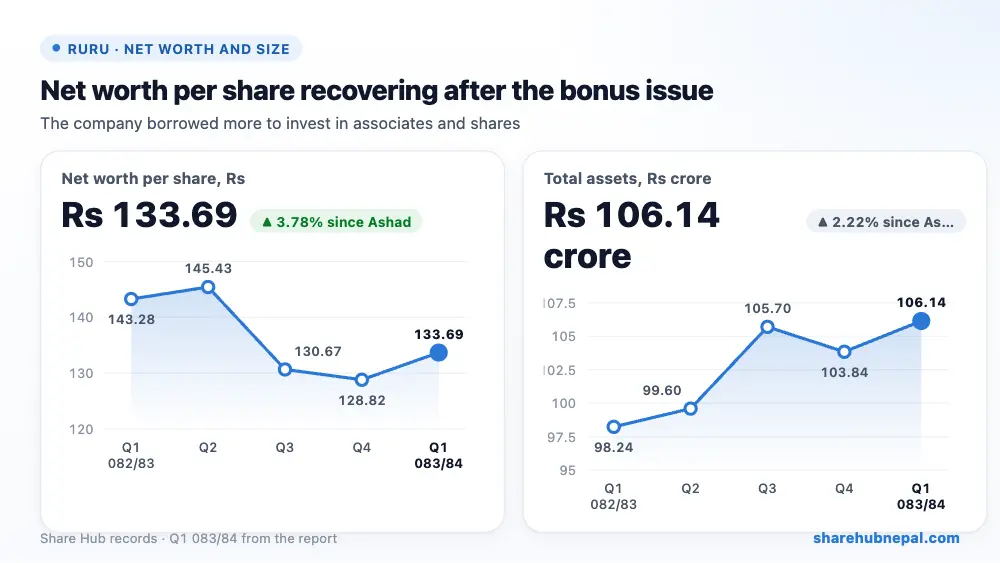
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 1,061,441,281 | Rs 1,038,362,868 | +2.22% |
| Total equity | Rs 834,315,764 | Rs 804,000,973 | +3.77% |
| Long-term borrowings | Rs 47,630,000 | Rs 60,000,000 | −20.62% |
| Current borrowings | Rs 48,370,000 | Rs 48,370,000 | +0.00% |
| Cash and equivalents | Rs 33,885,049 | Rs 23,930,527 | +41.60% |
A year ago the company had Rs 16.09 crore cash and only Rs 4.55 crore borrowing. Since then it has put Rs 15 crore more into associates and Rs 8 crore more into shares (OCI), so cash is now Rs 3.39 crore and borrowing Rs 9.60 crore (Rs 4.76 crore long-term and Rs 4.84 crore short-term). Debt is still small against equity of Rs 83.43 crore. Investments now make up Rs 42.90 crore, about 40% of total assets.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 19.49 |
| Net worth per share | Rs 133.69 |
| Market price (Ashwin end) | Rs 614 |
| P/E (annualised) | 31.50x |
| P/B | 4.59x |
At the Ashwin-end price of Rs 614, the share trades at 31.50 times annualised EPS and 4.59 times net worth per share. On FY 2082/83 EPS of Rs 10.40 the P/E is about 59x, so the share is expensive.
Conclusion
Positives: steady sales and gross margin, low debt, net worth per share back up to Rs 133.69, Rs 7.59 crore still to come from NEA.
Watch: profit down 8%, interest income gone, more borrowing, much of the money tied up in associates and shares, and a high P/E on full-year earnings.
The power plant is running steadily; the weaker profit comes from how the company is using its money. Returns from the new investments will decide whether that pays off.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

