













Sahas Urja Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
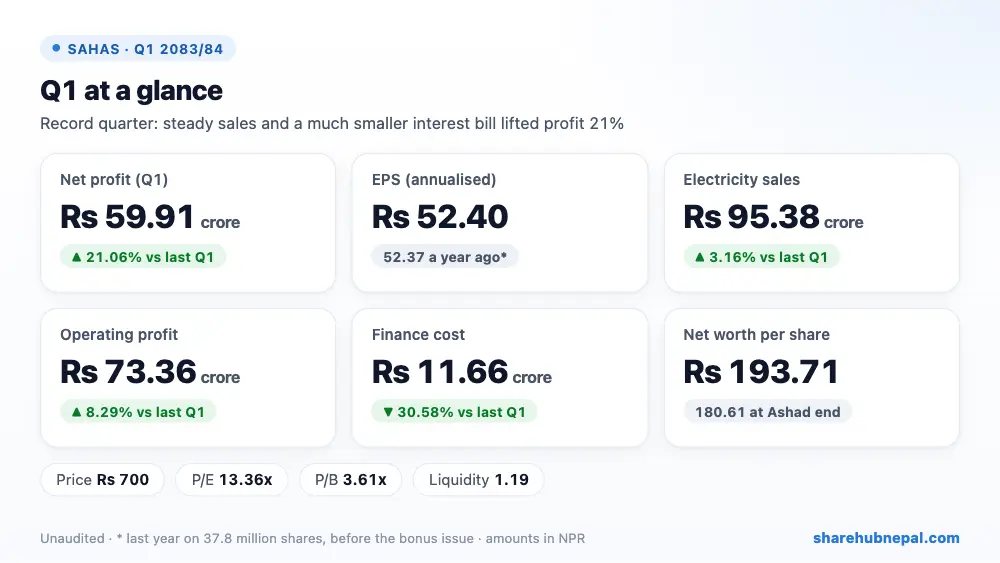
Summary
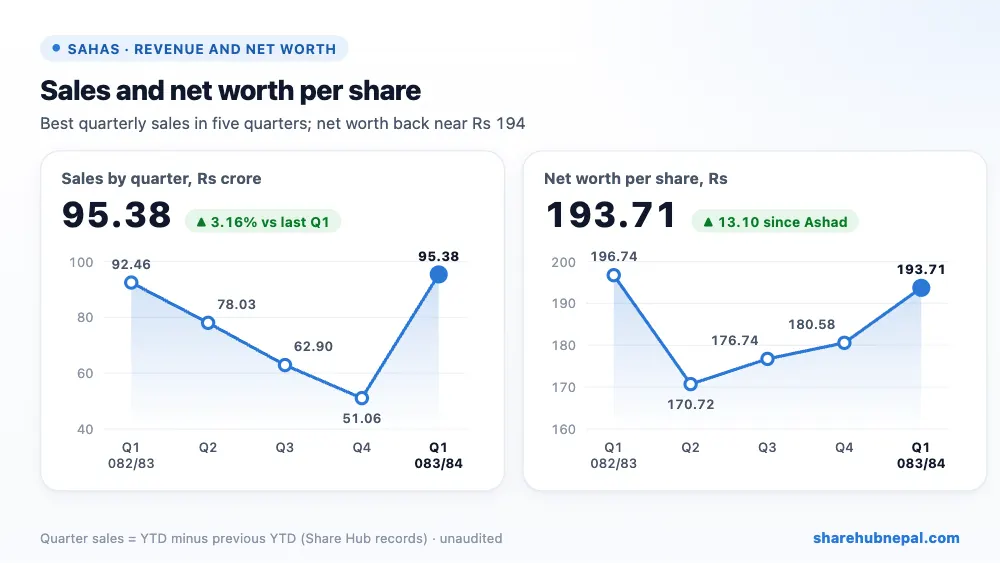
Sahas Urja earned a net profit of Rs 59.91 crore in the first quarter of 2083/84, up 21.06% from Rs 49.49 crore a year ago — its best quarter in the last five. Annualised EPS is Rs 52.40 and net worth per share rose to Rs 193.71 from Rs 180.61 at Ashad end.
The 86 MW Solu Khola (Dudhkoshi) plant ran without a break, and electricity sales rose 3.16% to Rs 95.38 crore. Most of the extra profit came from lower costs: interest fell 30.58% to Rs 11.66 crore as the loan was paid down, admin cost fell 44.14% and direct expenses fell 19.03%. No income tax is charged on the plant's income.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sale of electricity | Rs 953,823,363 | Rs 924,636,987 | +3.16% |
| Direct expenses | Rs 51,772,245 | Rs 63,937,217 | −19.03% |
| Amortisation of project cost | Rs 158,160,410 | Rs 156,190,872 | +1.26% |
| Gross profit | Rs 743,890,707 | Rs 704,508,898 | +5.59% |
| Other income | Rs 5,980,791 | Rs 0 | – |
| Administrative expenses | Rs 12,945,612 | Rs 23,173,423 | −44.14% |
| Operating profit | Rs 733,634,617 | Rs 677,478,849 | +8.29% |
| Finance costs (net of finance income) | Rs 115,956,973 | Rs 167,272,683 | −30.68% |
| Staff bonus and CSR | Rs 18,530,329 | Rs 15,306,185 | +21.06% |
| Net profit | Rs 599,147,315 | Rs 494,899,981 | +21.06% |
| EPS (annualised) | 52.40 | 52.37 | – |
1. Where the profit came from
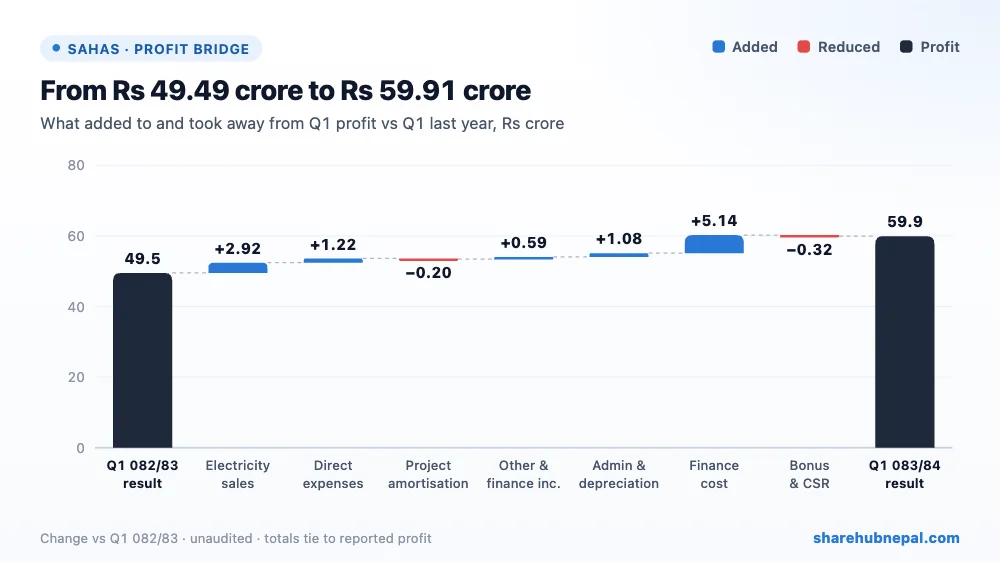
Compared with last year's Q1, lower interest added Rs 5.14 crore, higher sales Rs 2.92 crore, lower direct expenses Rs 1.22 crore, lower admin cost and depreciation Rs 1.08 crore and new other income Rs 59.32 lakh. Higher project amortisation took away Rs 19.70 lakh and higher staff bonus and CSR Rs 32.24 lakh. The net result is Rs 10.42 crore more profit.
2. Profit through the year
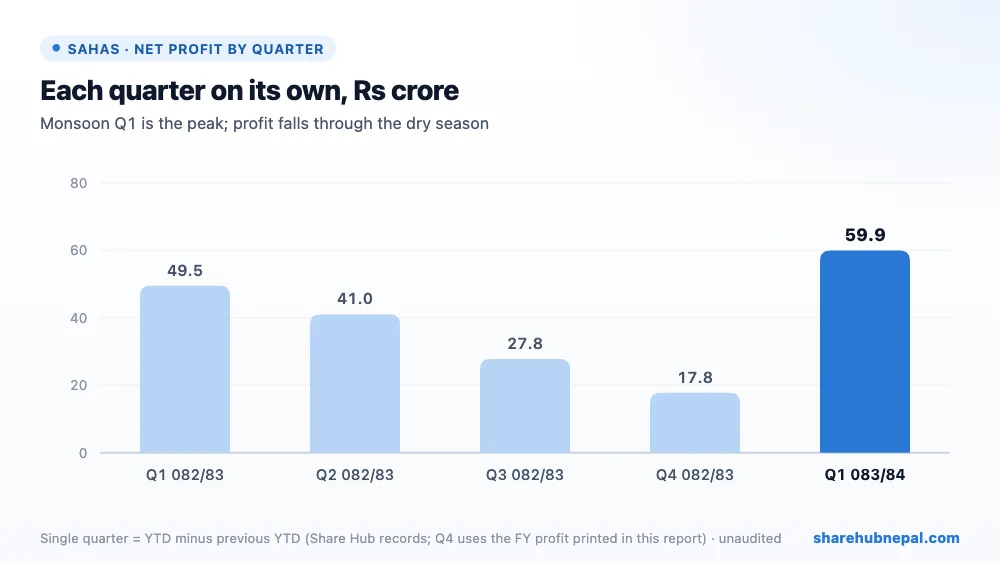
Based on Share Hub's records, single-quarter profit in 2082/83 was Rs 49.49 crore in Q1, Rs 40.99 crore in Q2, Rs 27.79 crore in Q3 and Rs 17.75 crore in Q4 (using the FY profit of Rs 1.36 arba printed in this report). Profit is highest in the monsoon and falls as river flow drops, so the annualised EPS of Rs 52.40 overstates the full year; last year's full-year EPS was Rs 29.74. Still, this Q1 beat last year's by a clear margin, which points to a better 2083/84.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Intangible assets (project, net) | Rs 14,851,778,322 | Rs 14,965,598,203 | −0.76% |
| Investment in subsidiary | Rs 2,162,470,400 | Rs 2,162,470,400 | +0.00% |
| Cash and cash equivalents | Rs 739,406,559 | Rs 540,012,068 | +36.92% |
| Medium and long-term loan | Rs 8,592,211,838 | Rs 8,855,742,950 | −2.98% |
| Bridge gap loan | Rs 1,199,999,915 | Rs 1,199,999,915 | +0.00% |
| Shareholders' fund | Rs 8,854,354,168 | Rs 8,255,263,353 | +7.26% |
| Total assets | Rs 18,793,631,380 | Rs 18,457,408,124 | +1.82% |
Total loans are Rs 9.79 arba (long-term Rs 8.59 arba plus a Rs 1.20 arba bridge gap loan) against a shareholders' fund of Rs 8.85 arba, about 1.1 times. The long-term loan fell Rs 26.35 crore in Q1. Cash rose to Rs 73.94 crore and the liquidity ratio is 1.19. Rs 2.16 arba is invested in the subsidiary Times Energy, which is developing the 341 MW Budhi Gandaki (PROR) project; design is in the final stage, but a sudden flood in the Budhi Gandaki damaged the site's housing (loss still being assessed).
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised, as printed) | Rs 52.40 |
| EPS (quarter) | Rs 13.1 |
| Net worth per share | Rs 193.71 |
| Total assets per share | Rs 410.90 |
| Market price (Q1 close) | Rs 700 |
| P/E (annualised, as printed) | 13.36x |
| P/B | 3.61x |
| Liquidity ratio | 1.19 |
The Q1 closing price was Rs 700 (range Rs 636 to Rs 725). The report's P/E of 13.36 uses annualised EPS; on last year's full-year EPS of Rs 29.74 the P/E is about 23.5 times. The price is 3.61 times net worth per share. A 1:1 right share has been approved by the Electricity Regulatory Commission and is waiting for SEBON approval; it will double the share count, so EPS per share will fall unless the new money earns quickly.
Conclusion
Positives: record Q1 profit, steady generation, interest cost down 31%, lower admin and direct costs, rising cash, no income tax on generation income, and a large new project (Budhi Gandaki 341 MW) through the subsidiary.
Watch: the seasonal drop in profit through the dry season, the 1:1 right issue diluting EPS, the cost and funding of Budhi Gandaki, the Rs 1.20 arba bridge gap loan that must be refinanced, flood damage at the Budhi Gandaki site, and river-flow risk from climate change at the run-of-river plant.
A strong start to the year: Sahas earns well from its running plant and is cutting interest cost as it repays debt. The next big questions are the right issue and how the Budhi Gandaki project is funded.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

