













Sanvi Energy Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
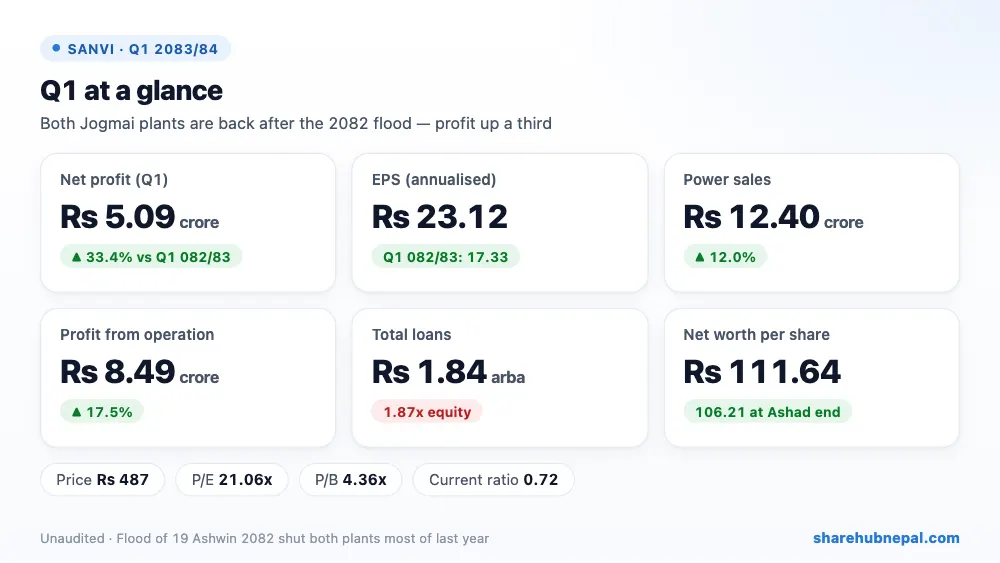
Summary
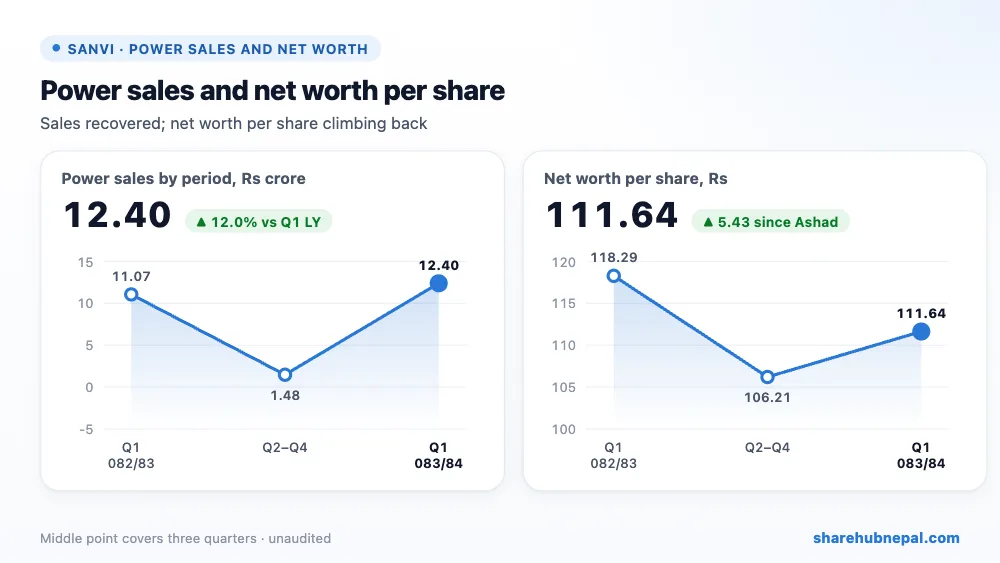
Sanvi Energy earned a net profit of Rs 5.09 crore in the first quarter of 2083/84, up 33.45% from Rs 3.81 crore a year ago. Annualised EPS is Rs 23.12 (17.33 a year ago) and net worth per share rose to Rs 111.64 from Rs 106.21 at Ashad end.
This is the first full monsoon quarter since the 19 Ashwin 2082 flood on the Jogmai Khola in Ilam shut both of the company's plants. After rebuilding, the Jogmai Khola Small Hydro (7.6 MW) restarted on 29 Jestha 2083 and the Jogmai Cascade (5.2 MW) on 24 Ashad 2083. Power sales rose 11.95% to Rs 12.40 crore, and profit from operation rose 17.53%. Protection works and some repairs are still going on.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from operations | Rs 123,983,430 | Rs 110,746,432 | +11.95% |
| Cost of sales | Rs 2,492,104 | Rs 2,232,532 | +11.63% |
| Administrative expenses | Rs 11,196,135 | Rs 11,553,724 | −3.10% |
| Depreciation and amortisation | Rs 26,248,442 | Rs 24,765,351 | +5.99% |
| Profit from operation | Rs 84,852,039 | Rs 72,194,825 | +17.53% |
| Finance costs | Rs 32,405,112 | Rs 34,071,732 | −4.89% |
| Staff bonus and CSR | Rs 1,573,408 | Rs 0 | – |
| Net profit | Rs 50,873,519 | Rs 38,123,093 | +33.45% |
1. Where the profit came from
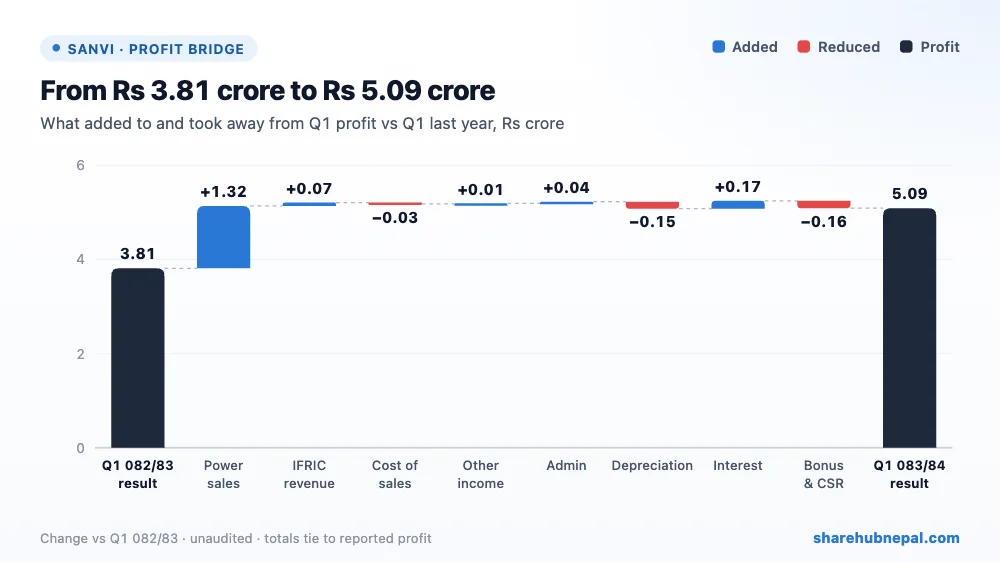
Against Q1 last year, higher power sales added Rs 1.32 crore, lower interest Rs 16.67 lakh, lower admin cost Rs 3.58 lakh and IFRIC-12 construction revenue Rs 7.05 lakh. Higher depreciation took away Rs 14.83 lakh and the new staff bonus and CSR provisions Rs 15.73 lakh. Net: profit up Rs 1.28 crore.
2. Profit through the year
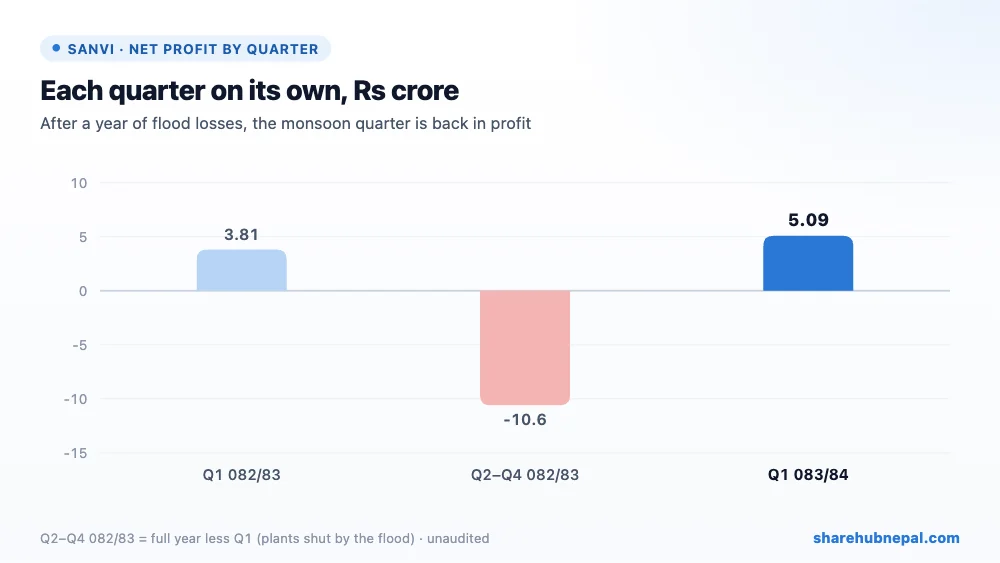
Last year shows how much the flood hurt: Q1 earned Rs 3.81 crore, but with both plants shut from 19 Ashwin the next three quarters lost Rs 10.60 crore together, so 2082/83 ended with a loss of Rs 6.79 crore (EPS −7.72). Part of that year's income was a Rs 7.70 crore insurance claim. With both plants running again, Q1 2083/84 is back to normal monsoon earnings; the dry-season quarters will be smaller, but should be far better than last year's shutdown quarters.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Intangible (project) assets | Rs 2,608,762,220 | Rs 2,624,336,289 | −0.59% |
| Trade receivables | Rs 84,228,688 | Rs 20,531,375 | +310.24% |
| Cash and cash equivalents | Rs 44,912,825 | Rs 34,912,173 | +28.65% |
| Non-current borrowings | Rs 1,529,143,508 | Rs 1,555,143,508 | −1.67% |
| Current borrowings | Rs 311,078,059 | Rs 178,078,059 | +74.69% |
| Total equity | Rs 982,400,567 | Rs 934,640,893 | +5.11% |
Debt is the main weakness. Long-term loans are Rs 1.53 arba and short-term loans jumped to Rs 31.11 crore from Rs 17.81 crore, so total loans are 1.87 times equity. Current liabilities (Rs 34.73 crore) are larger than current assets (Rs 24.85 crore); the current ratio is only 0.72. Receivables from NEA rose to Rs 8.42 crore with the monsoon sales. The insurer has paid Rs 12.70 crore of claim advances so far (Rs 5 crore property loss, Rs 7.70 crore loss of profit); final settlement is still pending.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised, report) | Rs 23.12 |
| EPS (quarter, derived) | Rs 5.78 |
| Net worth per share | Rs 111.64 |
| Market price (Q1 close) | Rs 487 |
| P/E (report) | 21.06x |
| P/B | 4.36x |
| Current ratio | 0.72 |
| Debt to equity | 1.87x |
The Q1 closing price was Rs 487 (range Rs 470.30 to Rs 665.70). The P/E is 21.06 on the annualised Q1 EPS and the price is 4.36 times net worth per share. Q1 is the best season, so the full-year P/E will likely be higher.
Conclusion
Positives: both plants back in operation, sales and operating profit above last year's Q1, lower interest, insurance claim advances received, and no legal cases.
Watch: high loans and rising short-term borrowing, a current ratio below 1, remaining protection and repair works, flood risk on the Jogmai Khola, the final insurance settlement, and a small unexplained gap between profit and the rise in equity.
Sanvi has recovered well from the 2082 flood and earned a good monsoon profit. The next test is whether it can keep the plants running through the year and bring its short-term debt down.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

