













Sikles Hydropower Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
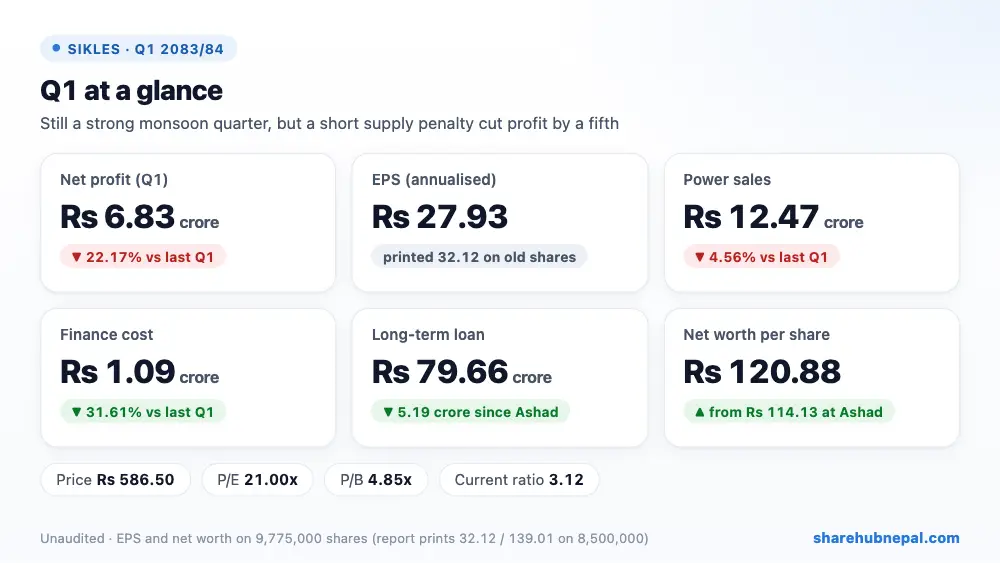
Sikles Hydropower, which runs the 13 MW Madkyu Khola project in Kaski, earned a net profit of Rs 6.83 crore in the first quarter, down 22.17% from Rs 8.77 crore a year ago. On the current 9,775,000 shares, annualised EPS is Rs 27.93 (the report prints 32.12 because it uses the 8,500,000 shares from before the bonus issue).
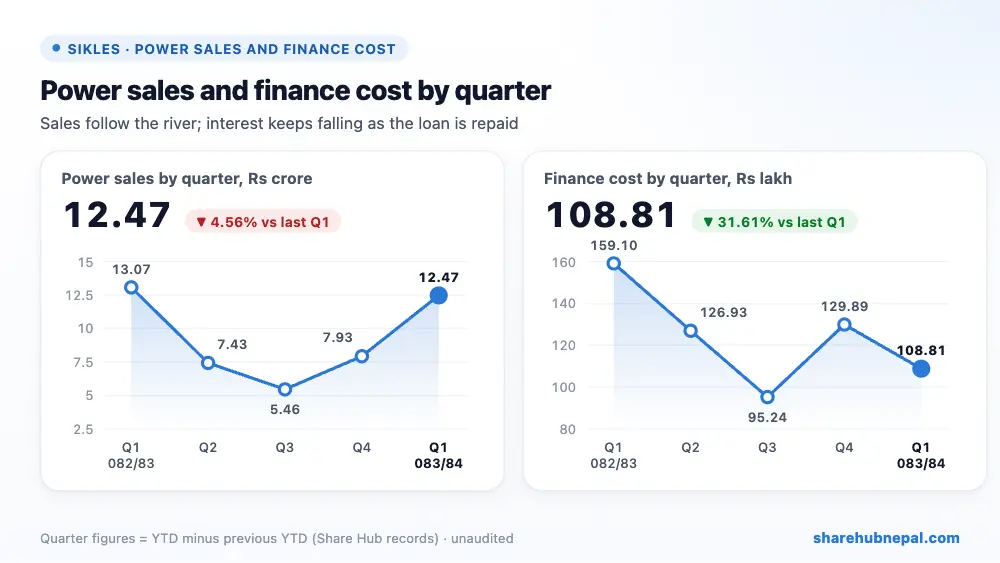
Power sales slipped 4.56% to Rs 12.47 crore. The main hit came from project operating expenses, which jumped to Rs 1.43 crore from Rs 30.77 lakh; the company says a short supply penalty pushed them up. Administrative costs and depreciation also rose. Finance cost fell 31.61% to Rs 1.09 crore as the loan is being repaid. Net margin was 54.74%, against 67.12% a year ago.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Income from power sales | Rs 124,697,893 | Rs 130,653,082 | −4.56% |
| Royalty | Rs 1,945,199 | Rs 1,694,750 | +14.78% |
| Project operating expenses | Rs 14,251,847 | Rs 3,076,829 | +363.20% |
| Administrative expenses | Rs 8,341,833 | Rs 5,603,593 | +48.87% |
| Finance cost | Rs 10,880,659 | Rs 15,910,352 | −31.61% |
| Depreciation | Rs 21,037,204 | Rs 17,118,545 | +22.89% |
| Net profit | Rs 68,260,804 | Rs 87,699,849 | −22.17% |
| EPS (annualised, 9,775,000 shares) | 27.93 | 35.89 | – |
1. Where the profit came from
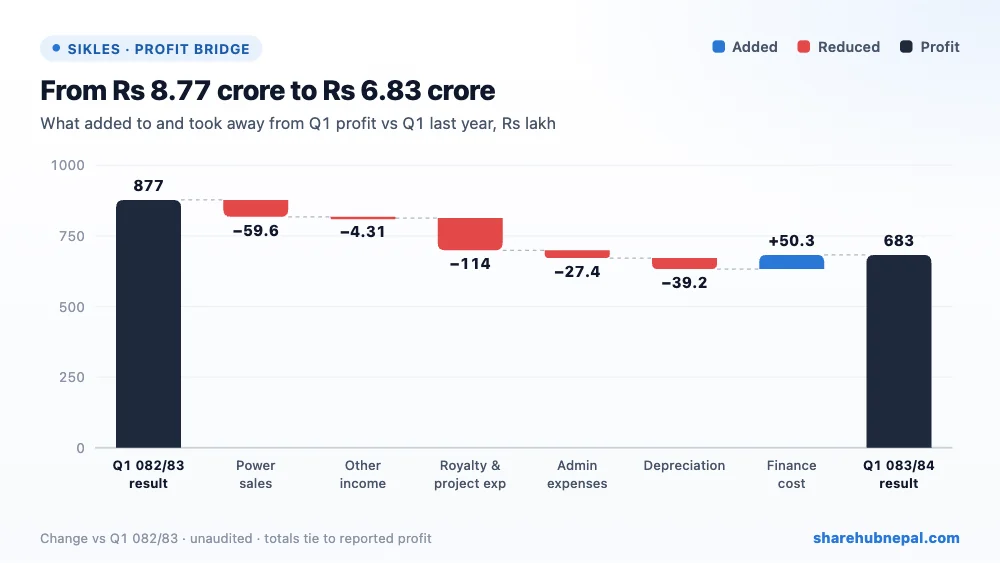
Compared with last year's Q1, higher royalty and project expenses took away Rs 1.14 crore, lower power sales Rs 59.55 lakh, higher depreciation Rs 39.19 lakh, higher administrative cost Rs 27.38 lakh and lower other income Rs 4.31 lakh. Lower finance cost added back Rs 50.30 lakh.
2. Profit through the year
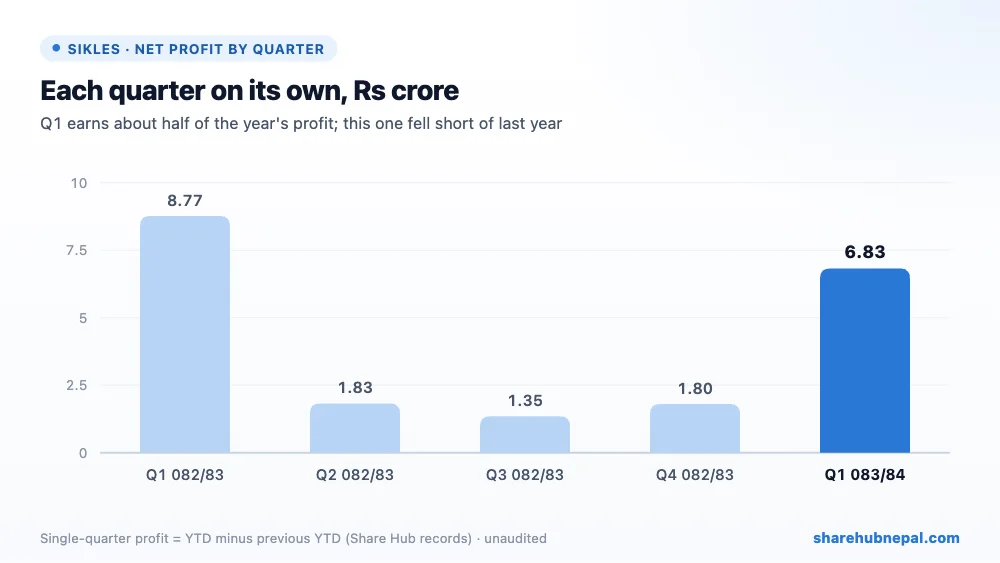
Based on Share Hub's records, single-quarter profit in 2082/83 was Rs 8.77 crore in Q1, Rs 1.83 crore in Q2, Rs 1.35 crore in Q3 and Rs 1.80 crore in Q4 (full year Rs 13.75 crore, EPS 14.07). Q1 alone earned about 64% of last year's profit, so annualising Q1 overstates the full year.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Long-term loan | Rs 796,580,089 | Rs 848,436,455 | −6.11% |
| Property, plant and equipment (net) | Rs 1,858,513,918 | Rs 1,881,631,230 | −1.23% |
| Current assets | Rs 176,151,394 | Rs 148,672,906 | +18.48% |
| Current liabilities | Rs 56,492,149 | Rs 66,269,869 | −14.75% |
| Total equity | Rs 1,181,593,075 | Rs 1,115,597,812 | +5.92% |
The long-term loan fell to Rs 79.66 crore from Rs 84.84 crore at Ashad end, only 0.67 times equity. Current assets of Rs 17.62 crore are 3.12 times current liabilities. Equity rose to Rs 118.16 crore, Rs 22.66 lakh less than the quarter's profit (not explained in the report). Net worth per share is Rs 120.88 on the current shares; the report prints Rs 139.01 on the old share count.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised, as printed) | Rs 32.12 |
| EPS (annualised, 9,775,000 shares) | Rs 27.93 |
| Net worth per share (as printed) | Rs 139.01 |
| Net worth per share (9,775,000 shares) | Rs 120.88 |
| Market price (report) | Rs 586.50 |
| P/E (report) | 18.26x |
| P/E (9,775,000 shares) | 21.00x |
At Rs 586.50 the share trades at 21.0 times annualised EPS on the current shares (18.26 as printed) and 4.85 times net worth per share. On last year's full-year EPS of Rs 14.07 the P/E is about 41.7.
Conclusion
Positives: still a large Q1 profit, falling loan and finance cost, low debt (0.67x equity), strong liquidity (current ratio 3.12) and no tax charge.
Watch: the short supply penalty and much higher project costs, lower power sales, the EPS and net worth printed on the old share count, the equity gap of Rs 22.66 lakh, and a seasonal Q1 that overstates annual EPS.
Sikles remains a profitable, low-debt plant, but this monsoon quarter was weaker because of the penalty and higher costs. Watch whether the penalty repeats in the coming quarters.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

