













Solu Hydropower Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the average quarter of FY 2082/83 (one quarter of the full-year figures) and with Ashad end 2083. The company was listed on 28 Falgun 2082, so the report has no Q1 2082/83 column.
Summary
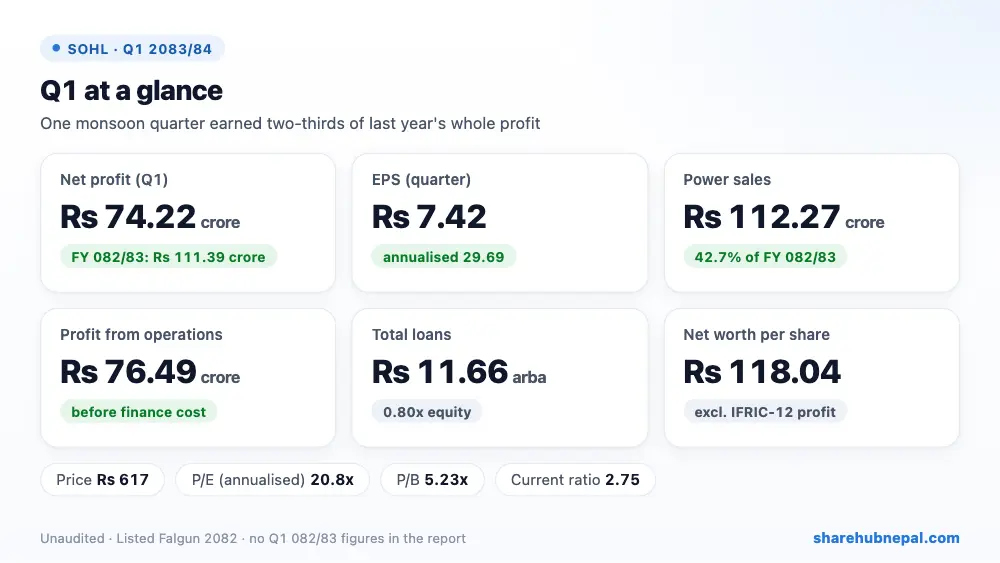
Solu Hydropower earned a net profit of Rs 74.22 crore in the first quarter of 2083/84 — two-thirds of its whole profit for 2082/83 (Rs 1.11 arba). Quarter EPS is Rs 7.42 (about Rs 29.69 annualised) and net worth per share, as printed without IFRIC-12 profit, is Rs 118.04.
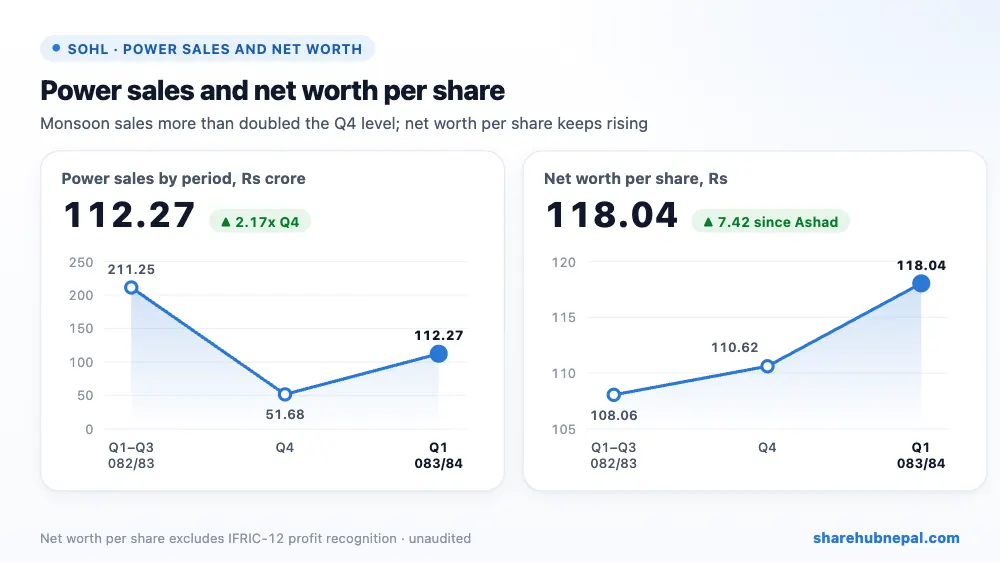
The company was listed in Falgun 2082, so the report has no figures for Q1 last year. We compare Q1 with an average quarter of 2082/83 instead. Monsoon sales of Rs 1.12 arba were 42.7% of last year's total, generation cost was Rs 34.22 crore, and net finance cost was only Rs 2.28 crore. No staff bonus, CSR or tax was provided in Q1.
| Indicator | Q1 2083/84 | FY 2082/83 ÷ 4 | Change |
| Revenue from operations | Rs 1,122,708,720 | Rs 657,311,472 | +70.80% |
| Generation expenses | Rs 342,223,793 | Rs 302,678,244 | +13.07% |
| Administrative expenses | Rs 15,557,853 | Rs 23,700,892 | −34.36% |
| Profit from operations | Rs 764,927,074 | Rs 330,932,335 | +131.14% |
| Net finance costs | Rs 22,764,199 | Rs 43,849,969 | −48.09% |
| Staff bonus and CSR | Rs 0 | Rs 8,612,471 | −100.00% |
| Net profit | Rs 742,162,875 | Rs 278,469,894 | +166.51% |
1. Where the profit came from
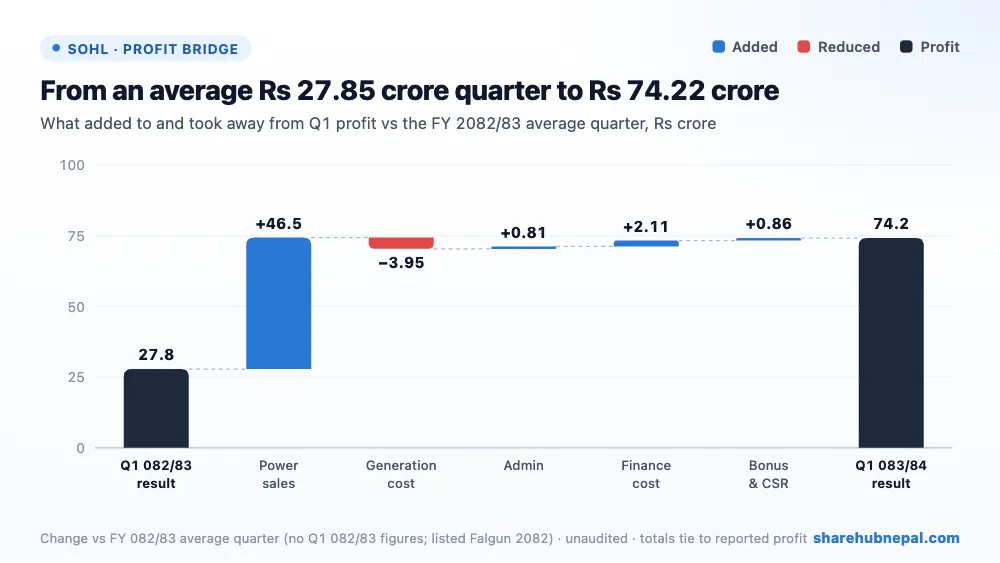
Against an average quarter of last year (Rs 27.85 crore), higher monsoon sales added Rs 46.54 crore, lower finance cost added Rs 2.11 crore, lower admin cost Rs 81.43 lakh, and no bonus/CSR provision Rs 86.12 lakh. Higher generation cost took away Rs 3.95 crore. Note that last year's finance cost and bonus were for the full year, so Q1 looks better partly because some year-end charges come later.
2. Profit through the year
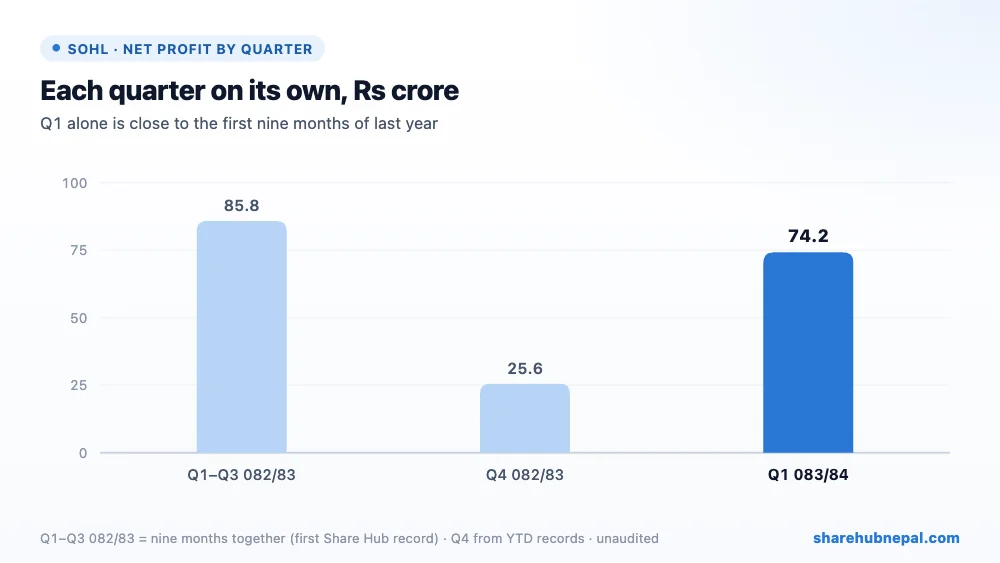
Share Hub has SOHL figures only from Q3 2082/83: the first nine months earned Rs 85.81 crore and Q4 alone Rs 25.58 crore. This Q1 (Rs 74.22 crore) is almost as much as those nine months. Hydropower profit is highest in the monsoon, so the annualised EPS of 29.69 will very likely not hold for the full year; last year's full-year EPS was 11.14.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Intangible (project) assets | Rs 21,509,580,235 | Rs 21,735,414,483 | −1.04% |
| Foreign currency fluctuation account | Rs 2,484,822,009 | Rs 2,605,134,785 | −4.62% |
| Trade and other receivables | Rs 1,327,053,895 | Rs 871,241,156 | +52.32% |
| Cash and cash equivalents | Rs 862,677,638 | Rs 606,801,758 | +42.17% |
| Long-term loans | Rs 10,961,376,811 | Rs 11,158,494,590 | −1.77% |
| Short-term loans | Rs 697,722,393 | Rs 695,917,389 | +0.26% |
| Total equity | Rs 14,546,550,600 | Rs 13,804,387,725 | +5.38% |
SOHL is a large, loan-funded project company: the plant is carried as an intangible asset of Rs 21.51 arba under IFRIC 12, plus a foreign currency fluctuation account of Rs 2.48 arba. Loans total Rs 11.66 arba (0.80 times equity); Rs 4.12 arba of the long-term loans is classed as 'unsustainable'. Cash rose to Rs 86.27 crore and NEA receivables to Rs 1.33 arba; the current ratio improved to 2.75 from 1.54. Equity rose by exactly the Q1 profit to Rs 14.55 arba.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (quarter, report) | Rs 7.42 |
| EPS (annualised, derived) | Rs 29.69 |
| Net worth per share (report, excl. IFRIC-12) | Rs 118.04 |
| Book equity per share | Rs 145.47 |
| Market price (Q1 close) | Rs 617 |
| P/E (report, on quarter EPS) | 83.14x |
| P/E (annualised EPS) | 20.78x |
| Current ratio | 2.75 |
| Debt to equity | 0.80x |
The Q1 closing price was Rs 617 (range Rs 500.10 to Rs 725; turnover Rs 865 crore in 61 days). The report's P/E of 83.14 uses the quarter EPS; on the annualised EPS it is 20.8 times, and on last year's EPS of 11.14 it is 55.4 times. The price is 5.23 times the printed net worth per share.
Conclusion
Positives: a very strong monsoon quarter, low finance cost in the quarter, better liquidity, rising cash, and no legal cases.
Watch: large loans (including Rs 4.12 arba classed 'unsustainable'), the foreign currency account, year-end bonus/CSR/tax charges not yet booked, much weaker dry-season quarters, and the lack of a last-year Q1 comparison.
SOHL had an excellent monsoon quarter. The full-year picture will depend on dry-season sales and on how its large loan book and year-end provisions play out.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

