













Shuvam Power Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
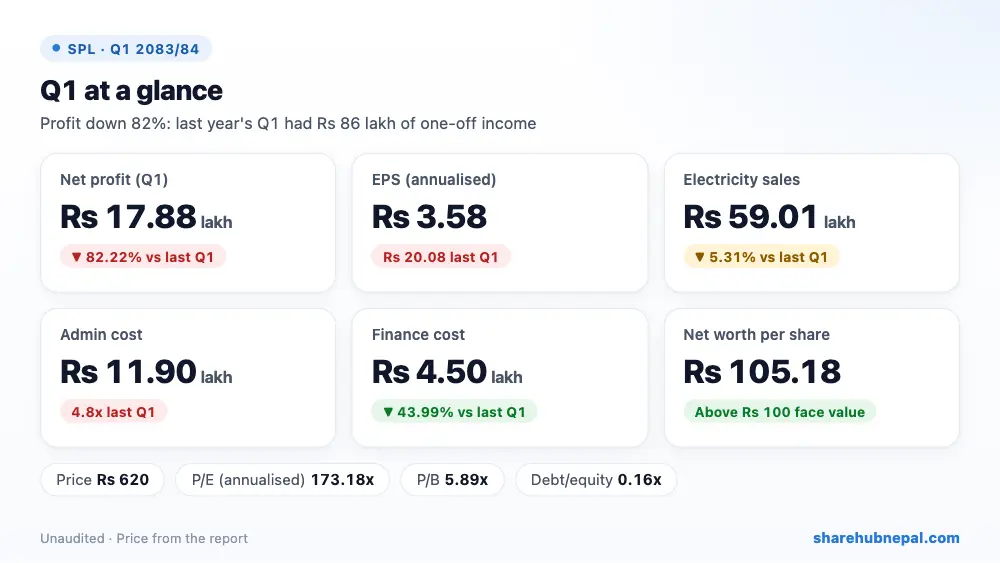
Shuvam Power (Lower Piluwa Khola small hydropower project) earned a net profit of Rs 17.88 lakh in the first quarter, down 82.22% from Rs 1.01 crore a year ago. Annualised EPS is Rs 3.58.
Most of the fall is because last year's Q1 included Rs 86 lakh of non-operating income, which did not repeat. Electricity sales also slipped 5.31% to Rs 59.01 lakh and administrative expenses rose to Rs 11.90 lakh from Rs 2.50 lakh. Finance cost fell 43.99% and tax was lower.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
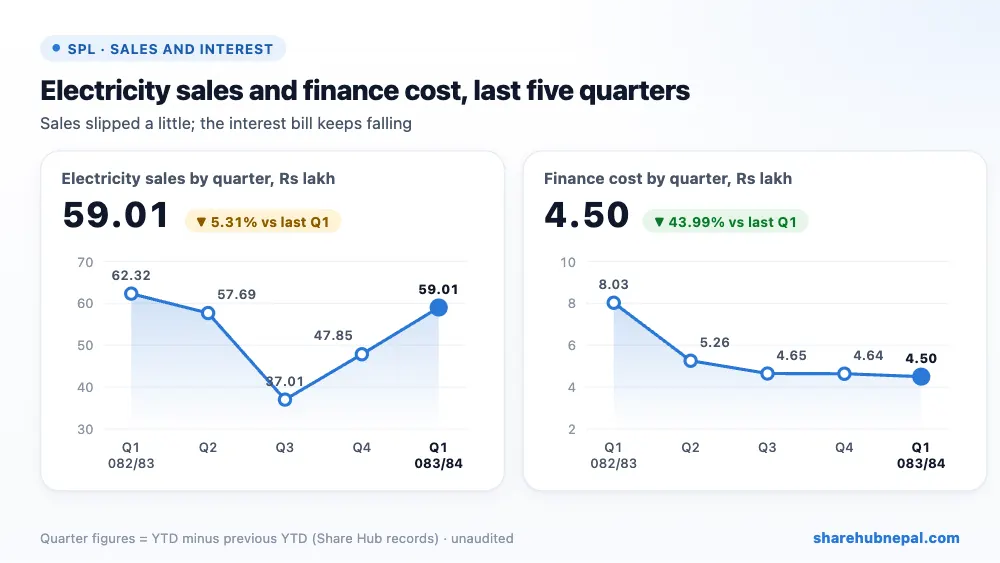
| Electricity sales | Rs 5,901,452 | Rs 6,232,287 | −5.31% |
| Non-operating income | Rs 0 | Rs 8,600,000 | −100.00% |
| Administrative expenses | Rs 1,190,142 | Rs 249,824 | +376.39% |
| Finance cost | Rs 450,000 | Rs 803,387 | −43.99% |
| Net profit | Rs 1,787,635 | Rs 10,052,479 | −82.22% |
| EPS (annualised) | 3.58 | 20.08 | – |
1. Where the profit came from
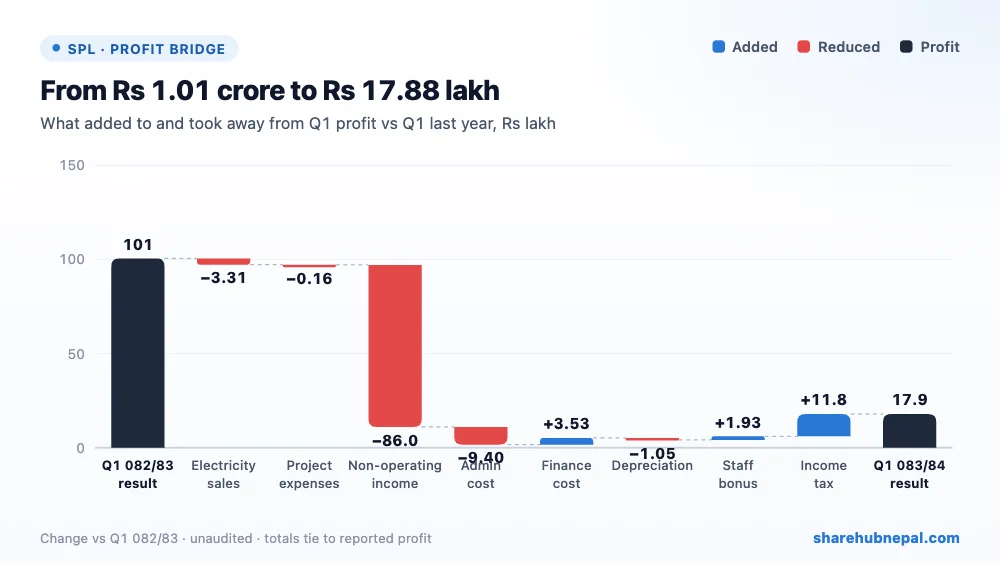
Compared with last year's Q1, the absence of non-operating income took away Rs 86 lakh, higher administrative expenses Rs 9.40 lakh, lower sales Rs 3.31 lakh and higher depreciation Rs 1.05 lakh. Lower tax added Rs 11.81 lakh, lower finance cost Rs 3.53 lakh and a smaller staff bonus Rs 1.93 lakh.
2. Profit through the year
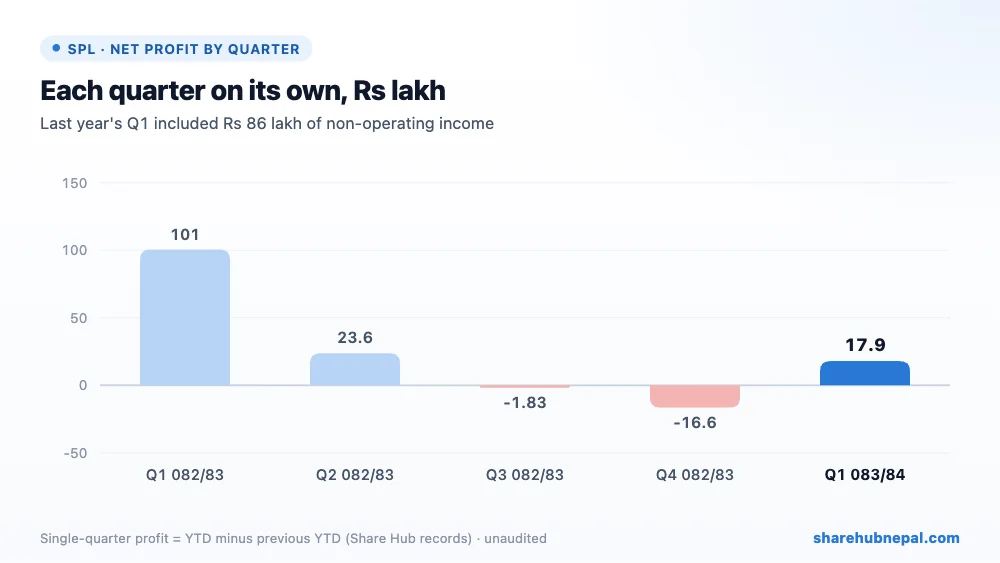
Based on Share Hub's records (Q1 2082/83 corrected in this update), single-quarter profits in 2082/83 were Rs 1.01 crore in Q1 (helped by the one-off income) and Rs 23.64 lakh in Q2, followed by small losses of Rs 1.83 lakh in Q3 and Rs 16.55 lakh in Q4. The full-year profit was Rs 1.06 crore, almost all from Q1.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Secured bank loans | Rs 26,770,119 | Rs 24,500,120 | +9.27% |
| Short-term borrowings | Rs 5,700,000 | Rs 2,892,000 | +97.10% |
| Net fixed assets | Rs 155,528,829 | Rs 153,707,666 | +1.18% |
| Advance, loan and deposits | Rs 29,458,998 | Rs 20,453,629 | +44.03% |
| Total assets | Rs 245,113,130 | Rs 237,494,828 | +3.21% |
| Total equity | Rs 209,257,149 | Rs 202,451,041 | +3.36% |
Total bank debt rose to Rs 3.25 crore from Rs 2.74 crore (secured loans Rs 2.68 crore, short-term borrowing Rs 57 lakh), still only 0.16 times equity. Trade receivables fell to Rs 36.96 lakh and advances rose to Rs 2.95 crore. Equity rose to Rs 20.93 crore; retained earnings grew by more than the quarter's profit, which the report does not explain.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 3.58 |
| Net worth per share | Rs 105.18 |
| Total assets per share | Rs 122.56 |
| Market price (report) | Rs 620 |
| P/E on annualised EPS | 173.18x |
| P/B | 5.93x |
| Current ratio | 5.28 |
At Rs 620 the share trades at 173.18 times annualised EPS and 5.93 times net worth per share. That is very expensive for a small plant whose profit is shrinking.
Conclusion
Positives: finance cost down 43.99%, low debt, a strong current ratio (5.28), and net worth above face value.
Watch: profit down 82.22%, lower electricity sales, administrative expenses 4.8 times last year, losses in Q3 and Q4 last year, an unexplained rise in retained earnings, and a P/E above 170.
Shuvam Power's core power business earns only a small profit, and last year's strong Q1 was flattered by one-off income. The share price looks far ahead of what the company earns.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

