













Three Star Hydropower Ltd. – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
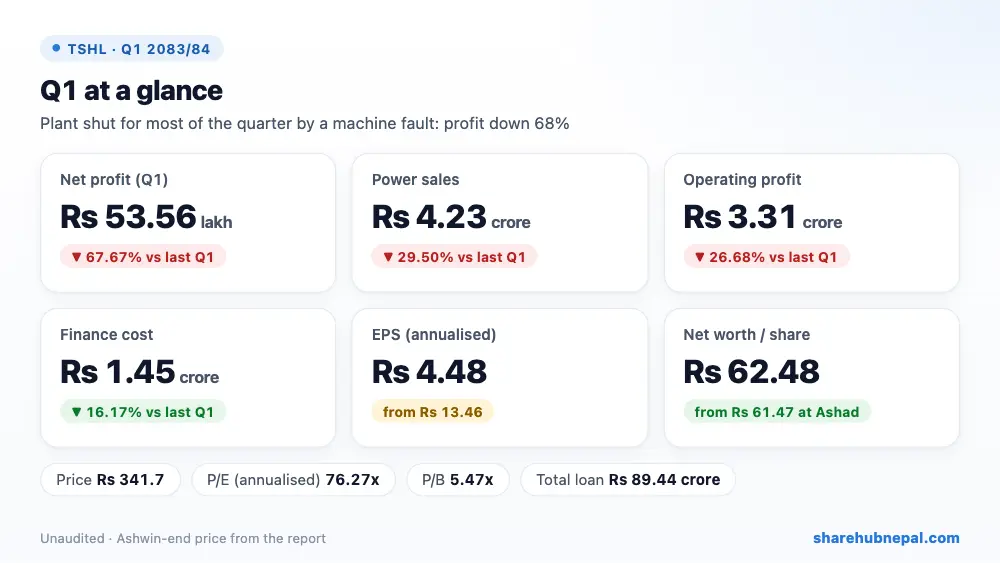
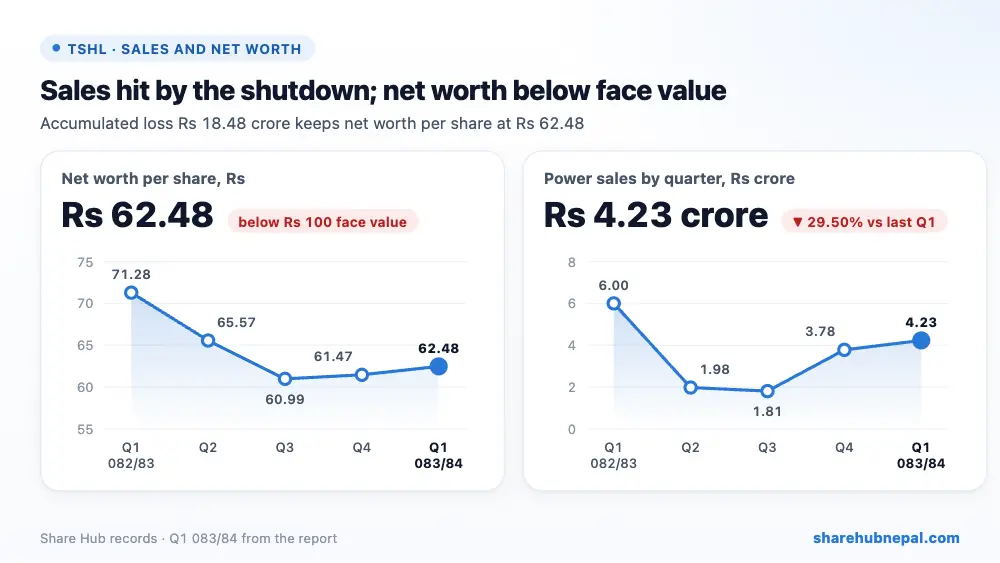
Three Star Hydropower (Sapsup Khola, 6.6 MW) earned Rs 53.56 lakh in the first quarter, down 67.67% from Rs 1.66 crore a year ago. The power house stopped on 25 Ashad 2083 because of a sudden electro-mechanical fault and both machines were back in full operation only from 11 Ashwin 2083, so most of the monsoon was lost. Power sales fell 29.50% to Rs 4.23 crore and the company also paid Rs 46.70 lakh in fines and penalties. Annualised EPS is Rs 4.48 against Rs 13.46.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sales | Rs 42,325,977 | Rs 60,039,511 | −29.50% |
| Cost of sales | Rs 5,630,992 | Rs 11,565,925 | −51.31% |
| Other income | Rs 4,192,103 | Rs 0 | – |
| Operating profit | Rs 33,054,158 | Rs 45,080,967 | −26.68% |
| Finance cost | Rs 14,544,433 | Rs 17,350,011 | −16.17% |
| Income tax | Rs 0 | Rs 0 | – |
| Net profit | Rs 5,356,485 | Rs 16,569,497 | −67.67% |
| EPS (annualised) | 4.48 | 13.46 | – |
| Net worth per share | 62.48 | 71.28 | – |
1. Where the profit came from
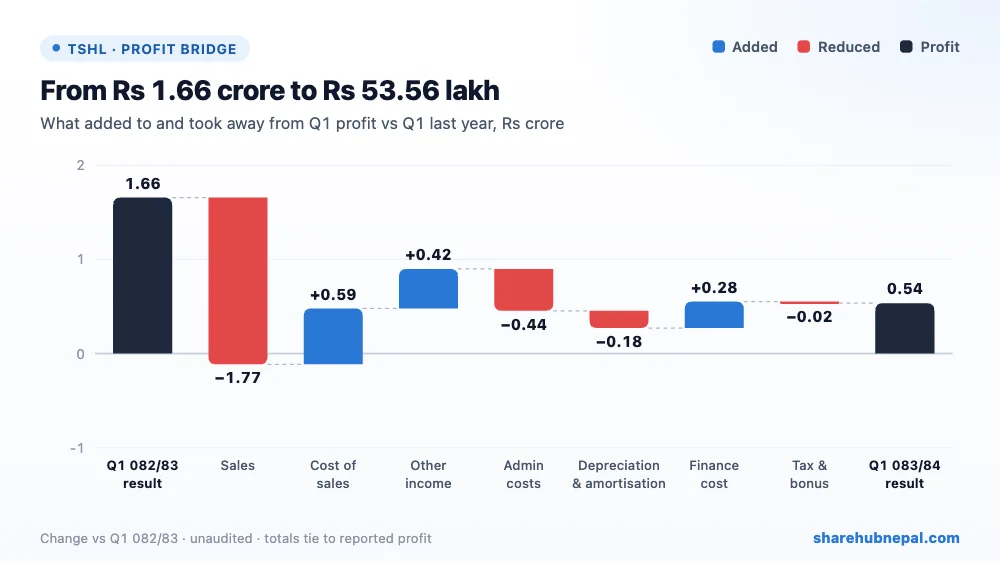
Lower power sales took away Rs 1.77 crore and fines plus higher admin cost Rs 44.40 lakh; depreciation rose by Rs 18.27 lakh. Royalty and project expenses were Rs 59.35 lakh lower, finance cost Rs 28.06 lakh lower, and an unexplained non-operating income of Rs 41.92 lakh helped. Without that income the quarter would have been almost break-even.
2. Profit through the year
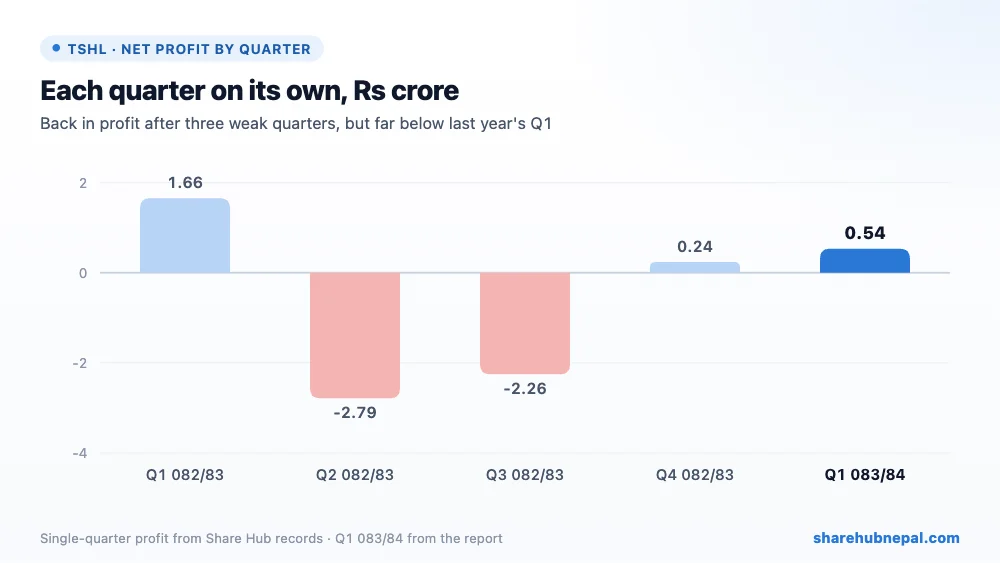
Profit by quarter (Share Hub records): Q1 082/83: Rs 1.66 crore, Q2 082/83: −Rs 2.79 crore, Q3 082/83: −Rs 2.26 crore, Q4 082/83: Rs 23.87 lakh, Q1 083/84: Rs 53.56 lakh. Last year the company lost money in Q2 and Q3 and ended FY 2082/83 with a loss of Rs 3.15 crore (EPS Rs -6.40).
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 1,391,614,532 | Rs 1,414,217,912 | −1.60% |
| Total equity | Rs 307,738,197 | Rs 302,753,371 | +1.65% |
| Long-term borrowings | Rs 864,409,685 | Rs 865,502,545 | −0.13% |
| Current borrowings | Rs 30,000,000 | Rs 30,000,000 | +0.00% |
| Cash and equivalents | Rs 294,033 | Rs 88,398 | +232.62% |
The balance sheet is weak. Accumulated losses of Rs 18.48 crore have cut net worth per share to Rs 62.48, well below the Rs 100 face value. The bank loan is Rs 86.44 crore plus Rs 3 crore short-term, about 2.9 times equity. Cash is only Rs 2.94 lakh, and current liabilities (Rs 21.93 crore, mostly payables) are more than six times current assets (current ratio 0.15).
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 4.48 |
| Net worth per share | Rs 62.48 |
| Market price (Ashwin end) | Rs 341.7 |
| P/E (annualised) | 76.27x |
| P/B | 5.47x |
At the Ashwin-end price of Rs 341.7, the share trades at 76.27 times annualised EPS and 5.47 times net worth per share. The price is more than five times net worth per share for a company with accumulated losses and weak liquidity, so the share is expensive on fundamentals.
Conclusion
Positives: both units running again from 11 Ashwin, back in profit, lower project and interest costs.
Watch: long shutdown in the peak season, fines and penalties, accumulated losses, very low cash and current ratio, high debt.
With both machines now running, Q2 should be better, but TSHL needs several good years to clear its losses and ease its cash squeeze.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

