













Trishuli Jal Vidhyut Company Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
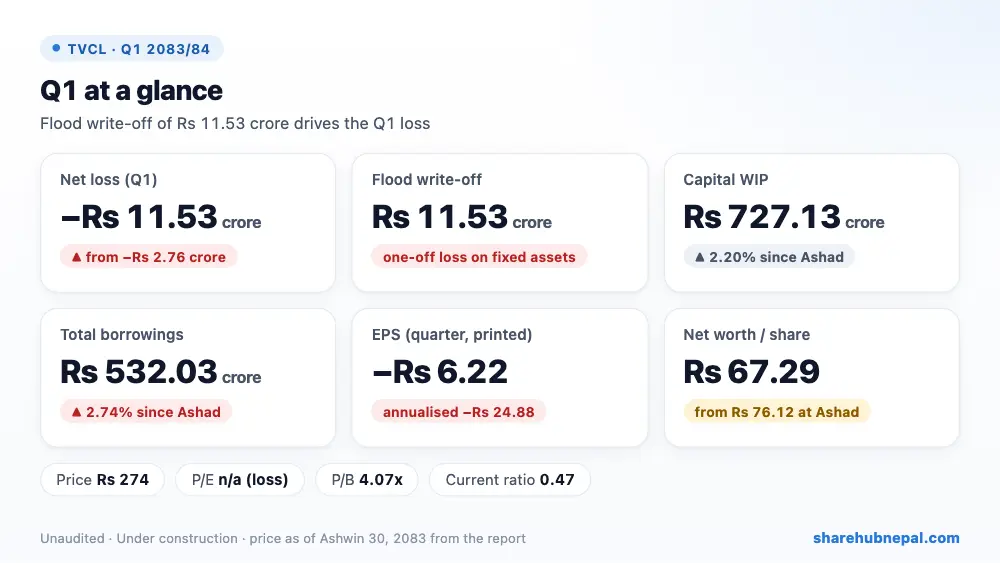
Summary
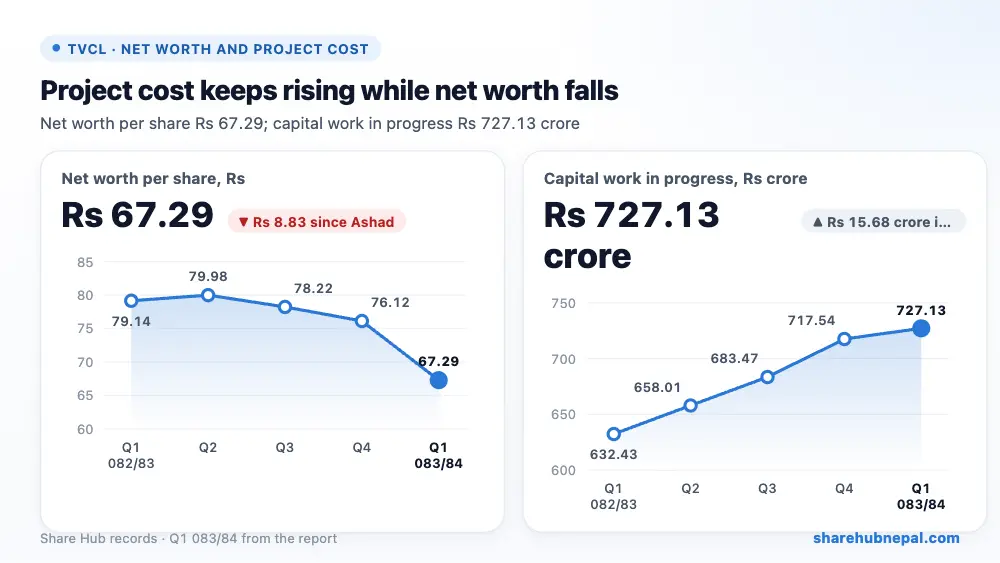
Trishuli Jal Vidhyut, which is building the Upper Trishuli 3B project, lost Rs 11.53 crore in the first quarter of FY 2083/84, against a loss of Rs 2.76 crore a year ago. Almost all of it is a Rs 11.53 crore write-off of buildings, vehicles and equipment destroyed by the Lende–Bhotekoshi–Trishuli flood of 10 Bhadra 2083. The flood also badly damaged the headworks, tunnels, penstock and powerhouse, and 183 people lost their lives (176 are still missing, including company staff). The project has no sales yet. Net worth per share fell to Rs 67.29 (as printed) from Rs 76.12 at Ashad end.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Employee cost | Rs 6,939,226 | Rs 6,796,303 | +2.10% |
| Administrative expenses | Rs 1,354,703 | Rs 1,521,398 | −10.96% |
| Depreciation | Rs 490,651 | Rs 463,386 | +5.88% |
| Foreign exchange (gain)/loss | −Rs 8,783,687 | Rs 18,789,256 | Turned to loss |
| Loss on fixed assets (flood) | Rs 115,289,741 | Rs 0 | – |
| Net loss | −Rs 115,290,633 | −Rs 27,570,343 | −318.17% |
| EPS (quarter, as printed) | -6.22 | -1.54 | – |
| Net worth per share | 67.29 | 79.14 | – |
1. Where the profit came from
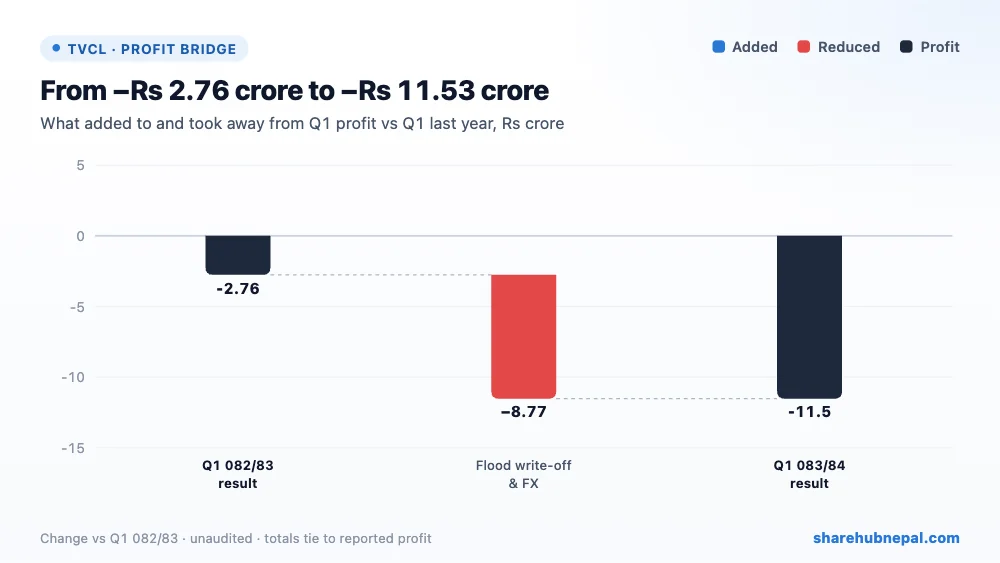
The write-off of flood-damaged assets (Rs 11.53 crore) is the main reason for the bigger loss. A foreign exchange gain of Rs 87.84 lakh this quarter, against a Rs 1.88 crore exchange loss a year ago, helped. Staff and admin costs (Rs 82.94 lakh) and depreciation (Rs 4.91 lakh) were about the same as last year.
2. Profit through the year
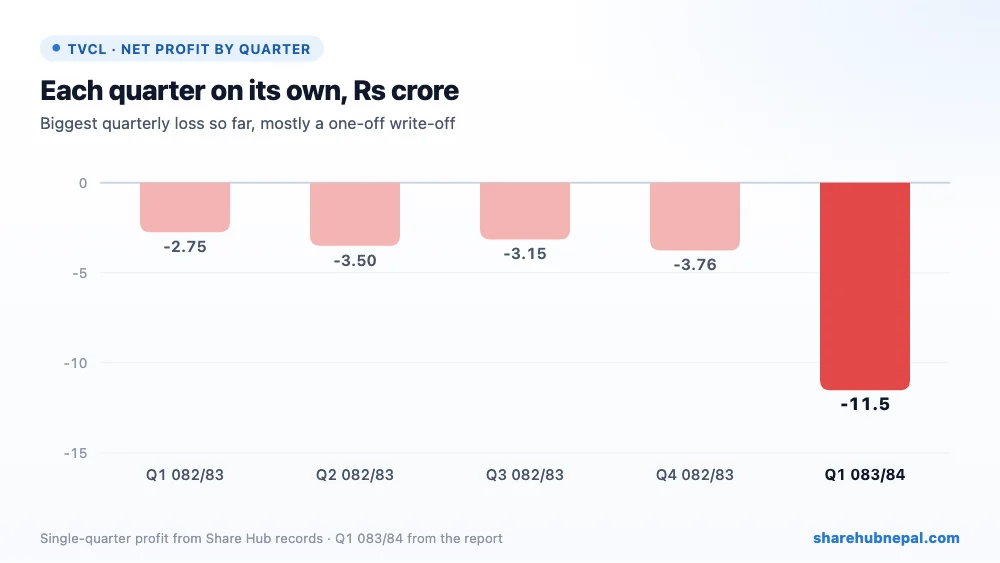
Profit by quarter (Share Hub records): Q1 082/83: −Rs 2.75 crore, Q2 082/83: −Rs 3.50 crore, Q3 082/83: −Rs 3.15 crore, Q4 082/83: −Rs 3.76 crore, Q1 083/84: −Rs 11.53 crore. The company has made a loss every quarter because the project is still being built; this quarter's loss is the largest because of the flood write-off.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 8,306,038,203 | Rs 8,294,978,900 | +0.13% |
| Total equity | Rs 1,246,620,434 | Rs 1,361,911,067 | −8.47% |
| Long-term borrowings | Rs 4,719,105,982 | Rs 4,637,334,387 | +1.76% |
| Current borrowings | Rs 601,151,930 | Rs 541,151,930 | +11.09% |
| Cash and equivalents | Rs 31,576,240 | Rs 41,536,473 | −23.98% |
| Capital work in progress | Rs 7,271,274,079 | Rs 7,114,435,622 | +2.20% |
| Property, plant and equipment | Rs 30,085,783 | Rs 146,743,690 | −79.50% |
| Other advances | Rs 956,901,379 | Rs 977,786,972 | −2.14% |
Total assets are Rs 830.60 crore, most of it capital work in progress of Rs 727.13 crore. The damaged headworks, tunnels, penstock and powerhouse have not been written down yet, so the real damage is still to be booked. Insurance claims have been filed with Siddhartha Premier Insurance (buildings) and, through the contractors, with Sanima GIC (contractor's all-risk policy). Borrowings rose to Rs 532.03 crore (long-term Rs 471.91 crore, short-term Rs 60.12 crore). Equity fell to Rs 124.66 crore with accumulated losses of Rs 54.25 crore, and the current ratio is only 0.47.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs -24.88 |
| Net worth per share | Rs 67.29 |
| Market price (Ashwin end) | Rs 274 |
| P/E (annualised) | -11.01x |
| P/B | 4.07x |
At the Ashwin-end price of Rs 274, the share trades at -11.01 times annualised EPS and 4.07 times net worth per share. With no earnings and a project that must be largely rebuilt, the price depends on insurance payouts and extra funding from the promoters (Nepal Electricity Authority and Nepal Telecom) and the Nabil Bank-led lenders.
Conclusion
Positives: strong promoters (Nepal Electricity Authority and Nepal Telecom), insurance claims filed, the Nabil Bank-led consortium is discussing extra funding, and a survey team is studying how to rebuild.
Watch: project structures heavily damaged, completion delayed beyond Ashad 2084, project cost will rise, damage to civil works not booked yet, borrowings rising, current ratio 0.47, net worth well below face value.
TVCL is now a rebuilding story: watch the damage assessment, the insurance settlement, any write-down of the Rs 727 crore work in progress and how the extra cost will be financed.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

