













Upper Hewakhola Hydropower Co. Ltd – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
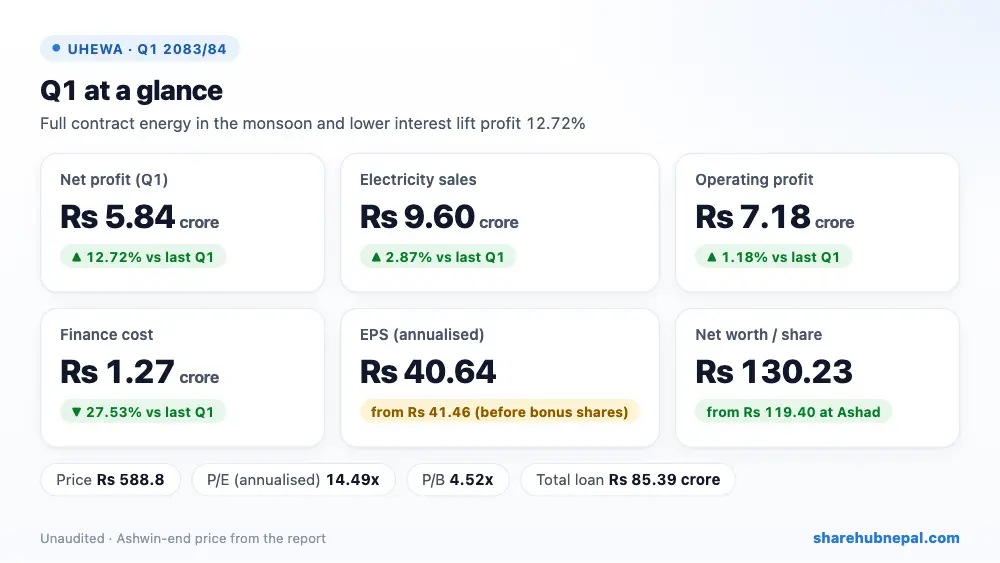
Upper Hewakhola Hydropower earned a net profit of Rs 5.84 crore in the first quarter of FY 2083/84, up 12.72% from Rs 5.18 crore a year ago. The plant produced 100% of the energy promised in its power purchase agreement, so electricity sales rose 2.87% to Rs 9.60 crore. The bigger help came from interest: finance cost fell 27.53% to Rs 1.27 crore as the loan is being repaid. Annualised EPS is Rs 40.64 (Rs 41.46 a year ago, before bonus shares) and net worth per share is Rs 130.23.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sales | Rs 95,996,233 | Rs 93,319,758 | +2.87% |
| Cost of sales | Rs 2,440,629 | Rs 1,632,634 | +49.49% |
| Other income | Rs 1,167,341 | Rs 40,156 | +2807.02% |
| Operating profit | Rs 71,789,830 | Rs 70,953,514 | +1.18% |
| Finance cost | Rs 12,728,079 | Rs 17,562,824 | −27.53% |
| Income tax | Rs 0 | Rs 0 | – |
| Net profit | Rs 58,422,219 | Rs 51,827,920 | +12.72% |
| EPS (annualised) | 40.64 | 41.46 | – |
| Net worth per share | 130.23 | 125.96 | – |
1. Where the profit came from
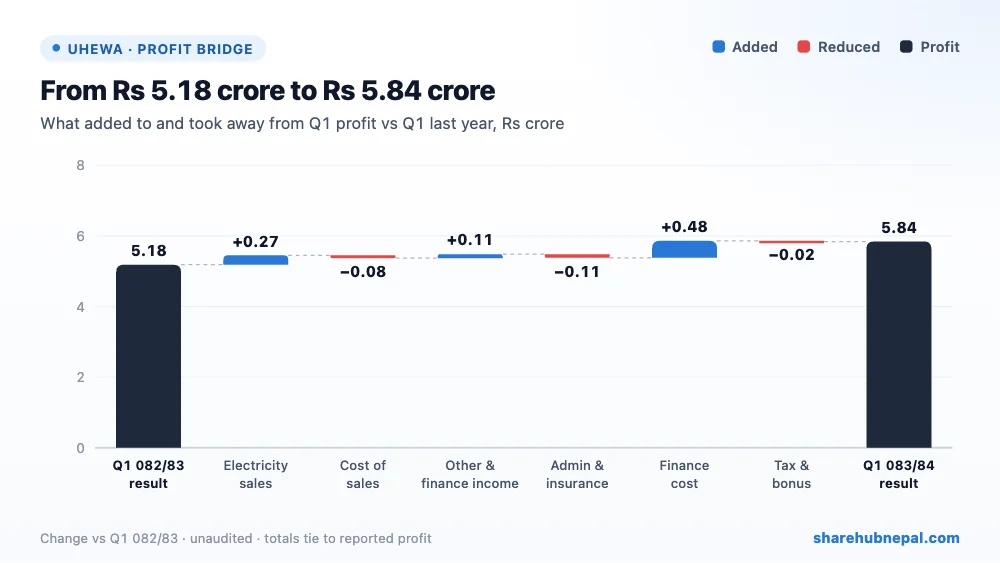
Sales of Rs 9.60 crore less cost of sales of Rs 24.41 lakh gave a gross profit of Rs 9.36 crore. Admin and insurance costs rose 16.83% to Rs 72.95 lakh, and other operating expenses including depreciation stayed at Rs 1.45 crore, so operating profit was Rs 7.18 crore (+1.18%). Finance cost fell by Rs 48.35 lakh to Rs 1.27 crore, and other income added Rs 11.67 lakh. After staff bonus and CSR of Rs 18.07 lakh (no income tax), net profit was Rs 5.84 crore.
2. Profit through the year
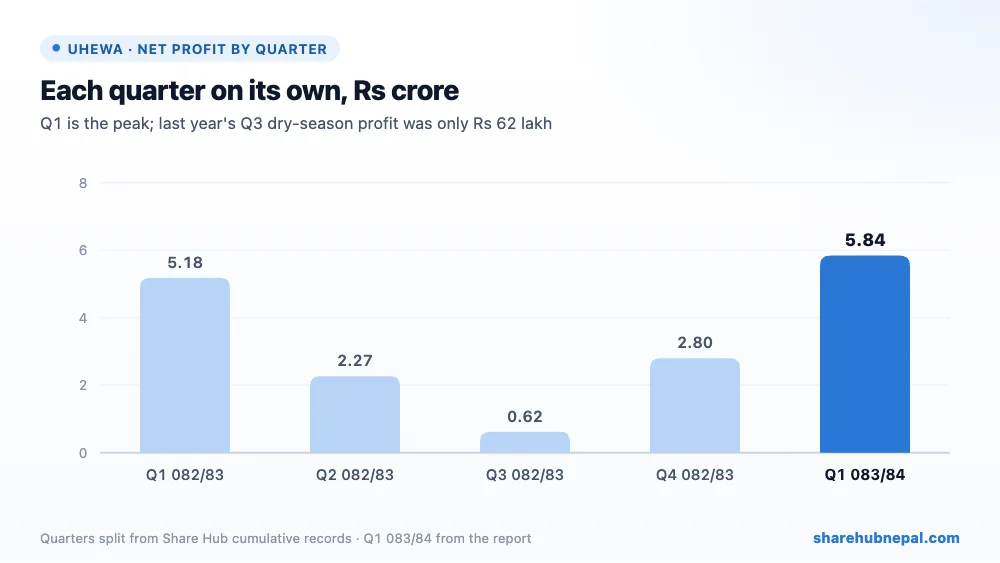
Profit by quarter (Share Hub cumulative records, split into quarters): Q1 082/83: Rs 5.18 crore, Q2 082/83: Rs 2.27 crore, Q3 082/83: Rs 62.11 lakh, Q4 082/83: Rs 2.80 crore, Q1 083/84: Rs 5.84 crore. Profit is very seasonal: last year Q1 earned Rs 5.18 crore but Q3 only Rs 62.11 lakh, and the full year was Rs 10.87 crore (EPS Rs 18.91). So the annualised EPS of Rs 40.64 is far above what a full year normally gives.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 1,628,021,545 | Rs 1,608,019,711 | +1.24% |
| Total equity | Rs 750,638,390 | Rs 689,925,463 | +8.80% |
| Long-term financial liabilities (loan) | Rs 849,179,609 | Rs 883,379,609 | −3.87% |
| Current financial liabilities | Rs 4,677,074 | Rs 27,658,673 | −83.09% |
| Investments (shares and new projects) | Rs 204,377,243 | Rs 181,894,489 | +12.36% |
| Trade and other receivables | Rs 74,890,265 | Rs 62,673,122 | +19.49% |
| Cash and equivalents | Rs 521,501 | Rs 338,056 | +54.26% |
| Trade and other payables | Rs 23,526,472 | Rs 7,055,965 | +233.43% |
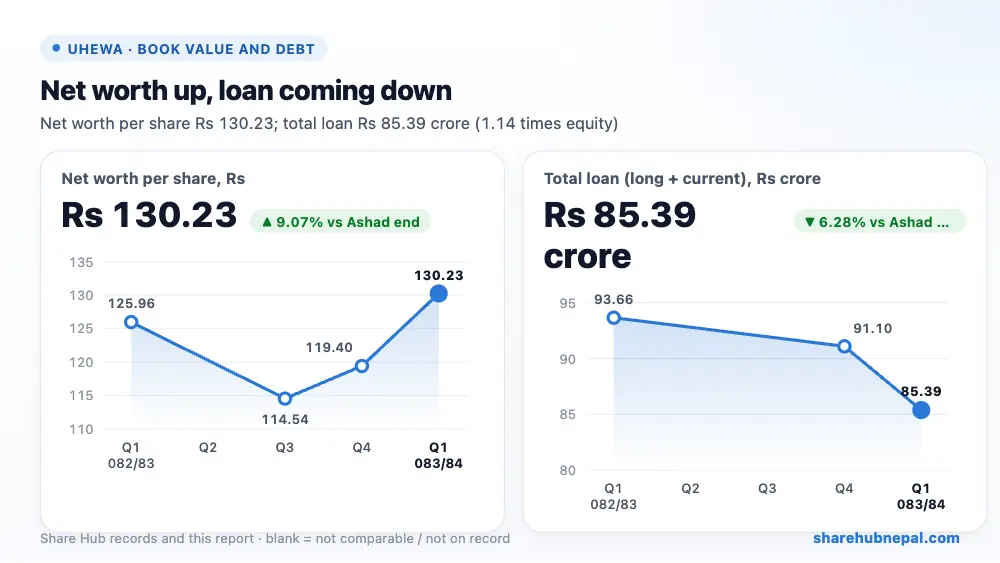
The long-term loan fell by Rs 3.42 crore to Rs 84.92 crore and current financial liabilities by Rs 2.30 crore, so total debt is Rs 85.39 crore, 1.14 times equity. The company is putting money into new projects: investments rose to Rs 20.44 crore, including the 27.9 MW Iddukhu hydropower project and shares of two other hydropower companies. Cash is very low at Rs 5.22 lakh, but Rs 7.49 crore is due from customers (mainly NEA). Equity rose 8.80% to Rs 75.06 crore; reserves rose Rs 38.46 lakh more than the profit, which the report does not explain.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 40.64 |
| Net worth per share | Rs 130.23 |
| Market price (Ashwin end) | Rs 588.8 |
| P/E (annualised) | 14.49x |
| P/B | 4.52x |
At the Ashwin-end price of Rs 588.8, the share trades at 14.49 times annualised EPS and 4.52 times net worth per share. On last year's actual EPS of Rs 18.91, the P/E would be about 31 times, so the low P/E here comes mostly from annualising the best quarter.
Conclusion
Positives: full contract energy delivered, profit up 12.72%, finance cost down 27.53%, loan steadily repaid, new investment in the Iddukhu project, no insurance claims in two years, and no legal cases.
Watch: profit is highly seasonal, cash is almost nil, money is going into new projects and shares that will not earn for some time, reserves moved more than the profit without explanation, and the company names climate change as its main risk.
Watch dry-season profit in Q2 and Q3, progress of the Iddukhu investment, and further loan repayment.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

