













Universal Power Company Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
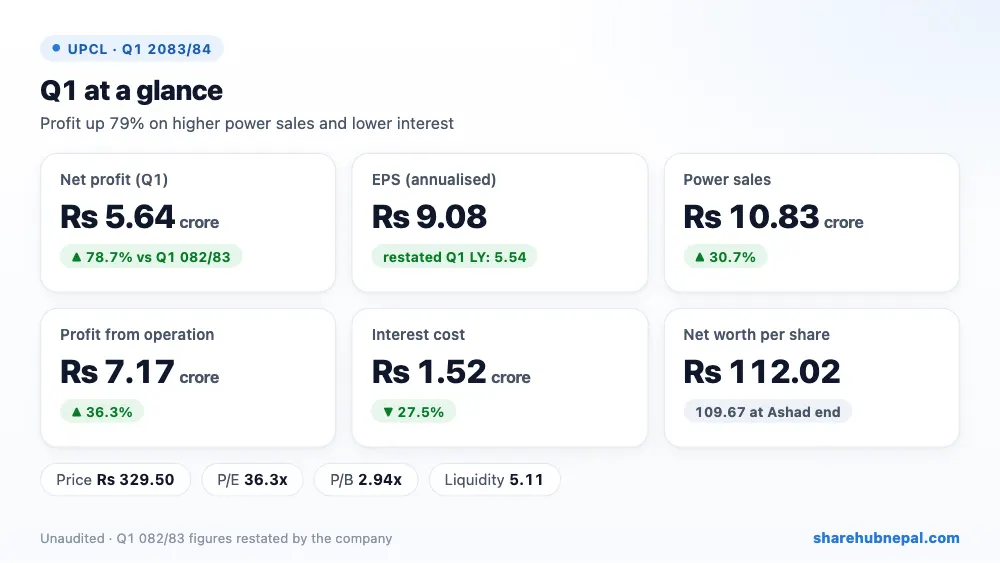
Summary
Universal Power Company, which runs the 11 MW Lower Khare Khola plant in Dolakha, earned a net profit of Rs 5.64 crore in the first quarter of 2083/84, up 78.70% from Rs 3.16 crore in the same quarter last year (the company has restated last year's figures; Share Hub's old record showed Rs 5.36 crore). Annualised EPS is Rs 9.08 and net worth per share is Rs 112.02.
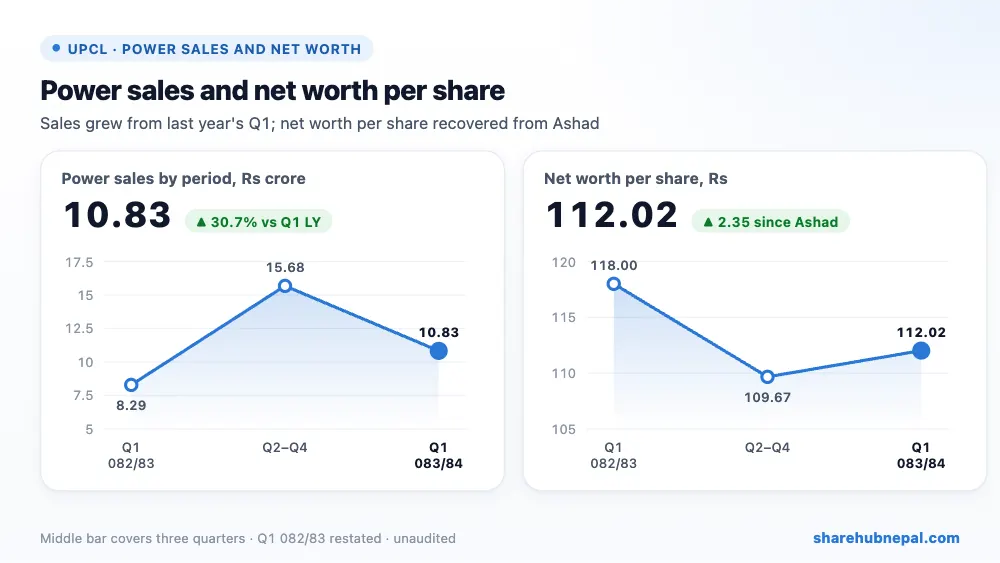
Power sales rose 30.65% to Rs 10.83 crore even though the 6 Shrawan 2083 flood damaged the intake and headrace pipe and stopped generation for a day, and NEA asked the plant to generate below capacity at times (spill). Lower interest cost also helped. One quarter of monsoon sales (Rs 10.83 crore) is already 45% of the whole of last year's sales (Rs 23.97 crore).
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue (power sales) | Rs 108,260,126 | Rs 82,860,930 | +30.65% |
| Generation expenses | Rs 11,619,540 | Rs 7,550,130 | +53.90% |
| Depreciation | Rs 30,059,719 | Rs 29,963,129 | +0.32% |
| Other income | Rs 10,175,932 | Rs 12,497,424 | −18.58% |
| Administrative and other expenses | Rs 5,091,977 | Rs 5,259,949 | −3.19% |
| Profit from operation | Rs 71,664,822 | Rs 52,585,145 | +36.28% |
| Finance costs | Rs 15,153,487 | Rs 20,909,992 | −27.53% |
| Net profit | Rs 56,398,696 | Rs 31,561,298 | +78.70% |
| Other comprehensive income | Rs 18,608,073 | −Rs 254,379,414 | Turned to profit |
1. Where the profit came from
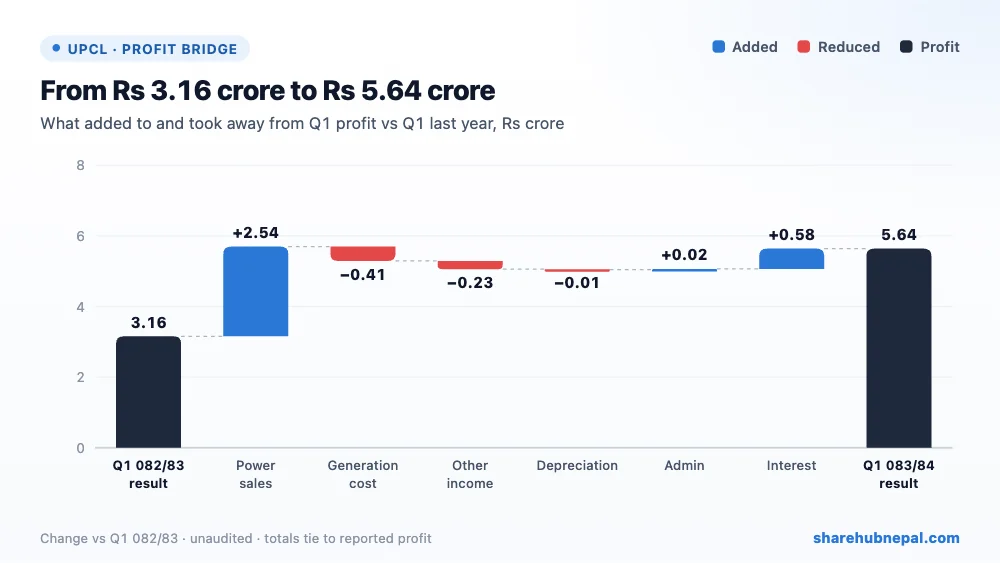
Compared with Q1 last year, higher power sales added Rs 2.54 crore and lower interest added Rs 57.57 lakh. Higher generation cost took away Rs 40.69 lakh and lower other income Rs 23.21 lakh. Depreciation and admin cost were almost unchanged. Net effect: profit up Rs 2.48 crore.
2. Profit through the year
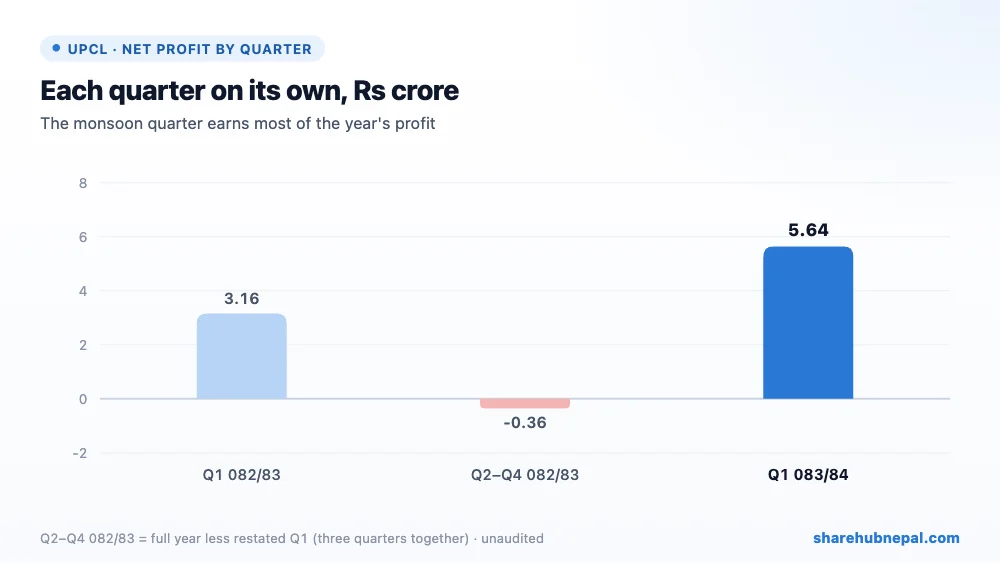
Hydropower profit depends on the season. Last year UPCL earned Rs 3.16 crore (restated) in Q1 but the remaining three quarters together made a small loss of Rs 35.93 lakh, so the full-year profit was only Rs 2.80 crore (EPS 1.13). This year's Q1 is better, but investors should not simply multiply it by four: the annualised EPS of 9.08 will very likely not hold through the dry season.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Property, plant and equipment | Rs 2,572,412,505 | Rs 2,602,475,812 | −1.16% |
| Investment in associates | Rs 745,610,679 | Rs 720,805,063 | +3.44% |
| Trade receivables (NEA) | Rs 84,616,135 | Rs 54,745,460 | +54.56% |
| Cash and cash equivalents | Rs 104,807,108 | Rs 96,910,254 | +8.15% |
| Long-term borrowings | Rs 1,201,567,373 | Rs 1,225,944,210 | −1.99% |
| Short-term borrowings | Rs 89,853,047 | Rs 102,953,047 | −12.72% |
| Total equity | Rs 2,783,813,742 | Rs 2,725,432,029 | +2.14% |
Debt is moderate: long-term loans fell to Rs 1.20 arba and short-term loans to Rs 8.99 crore, about 0.46 times equity of Rs 2.78 arba. Liquidity is strong (ratio 5.11). NEA owed Rs 8.46 crore for power at Ashwin end. The investment in associates rose to Rs 74.56 crore: Rapti Hydro and General Construction (Rukum Gad 5 MW) is now generating and listed, and Upper Ingkhu Khola (24.22 MW) is waiting for its power purchase agreement. A 1:1 right share, to repay loans and invest in Upper Chhujung (40.7 MW), still needs Electricity Regulatory Commission approval.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised, report) | Rs 9.08 |
| EPS (quarter, derived) | Rs 2.27 |
| Net worth per share | Rs 112.02 |
| Total assets per share | Rs 171.86 |
| Market price (Q1 close) | Rs 329.50 |
| P/E (report) | 36.30x |
| P/B | 2.94x |
| Liquidity ratio | 5.11 |
| Debt to equity | 0.46x |
The Q1 closing price was Rs 329.50 (range Rs 310 to Rs 370). On the annualised EPS the P/E is 36.3 times, and the price is 2.94 times net worth per share. On last year's full-year EPS (1.13) the P/E would be far higher, so the price already assumes a much better year than 2082/83.
Conclusion
Positives: profit up 79%, power sales up 31%, interest cost down 28%, strong liquidity, falling loans, and a growing group of associate projects.
Watch: the weak dry-season quarters (last year Q2–Q4 together made a loss), NEA spill instructions and flood risk, the insurance claim for the Shrawan flood damage, the pending right share (more shares will dilute EPS), and the restated prior-year figures.
UPCL had a good monsoon quarter, with higher sales and lower interest. The full-year result will depend on the dry season and on how the associate projects and the right share move forward.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

