













Upper Solu Hydro Electric Company Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
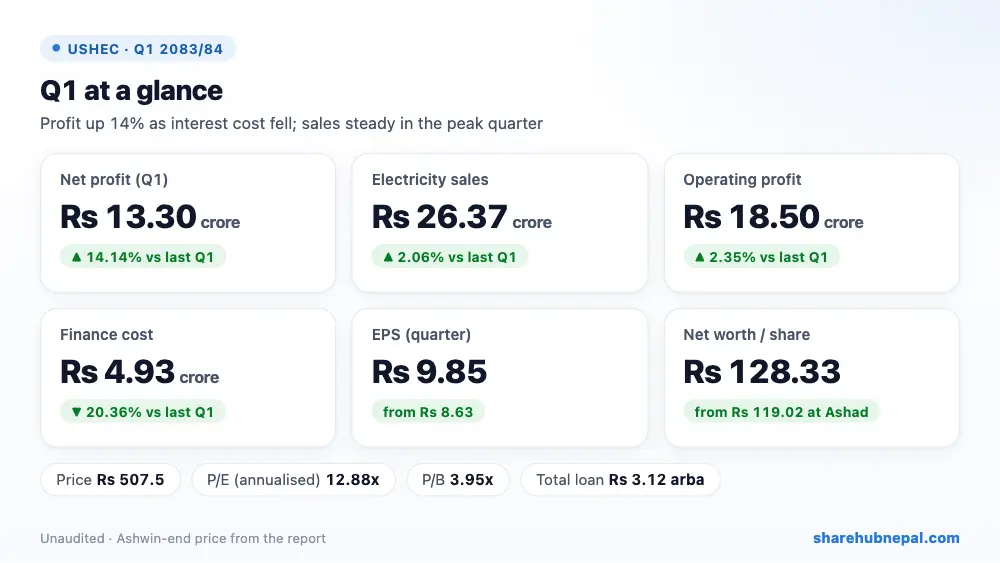
Upper Solu Hydro Electric earned Rs 13.30 crore in the first quarter, up 14.14% from Rs 11.65 crore a year ago. Electricity sales rose 2.06% to Rs 26.37 crore, plant operating cost was flat, and finance cost fell 20.36% to Rs 4.93 crore as the loan was paid down and interest rates eased. The company pays no income tax yet. Quarter EPS is Rs 9.85 (Rs 39.40 annualised).
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sales | Rs 263,675,263 | Rs 258,348,199 | +2.06% |
| Cost of sales | Rs 21,357,761 | Rs 21,468,297 | −0.51% |
| Other income | Rs 545,248 | Rs 434,143 | +25.59% |
| Operating profit | Rs 185,006,417 | Rs 180,763,363 | +2.35% |
| Finance cost | Rs 49,323,690 | Rs 61,931,508 | −20.36% |
| Income tax | Rs 0 | Rs 0 | – |
| Net profit | Rs 132,969,072 | Rs 116,498,336 | +14.14% |
| EPS (quarter) | 9.85 | 8.63 | – |
| Net worth per share | 128.33 | 112.67 | – |
1. Where the profit came from
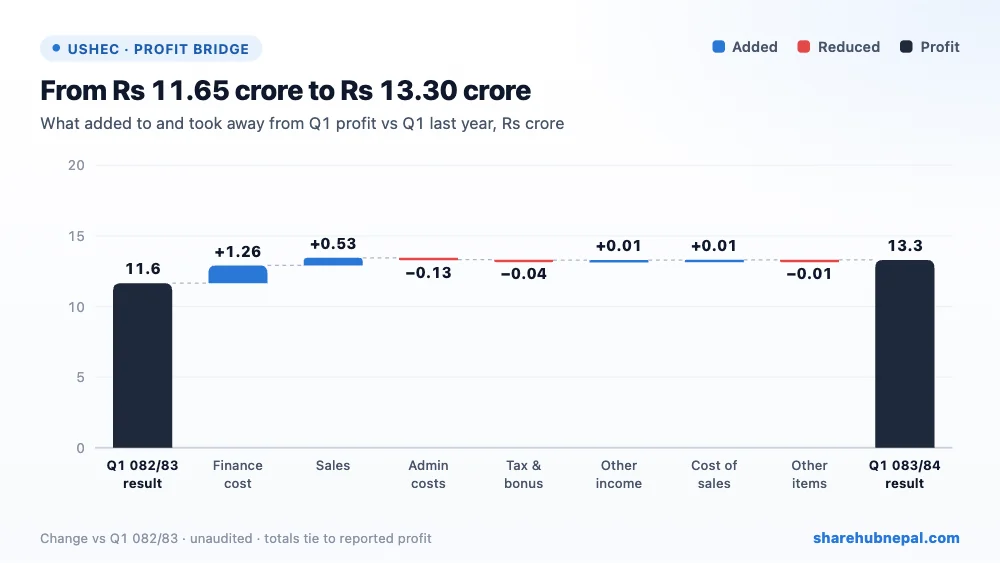
Profit rose by Rs 1.65 crore. Lower finance cost added Rs 1.26 crore and higher sales Rs 53.27 lakh. Admin and staff costs went up by Rs 12.53 lakh and staff bonus by Rs 3.80 lakh. Depreciation (about Rs 4.82 crore a quarter) and interest are still the two biggest costs, together eating more than a third of sales.
2. Profit through the year
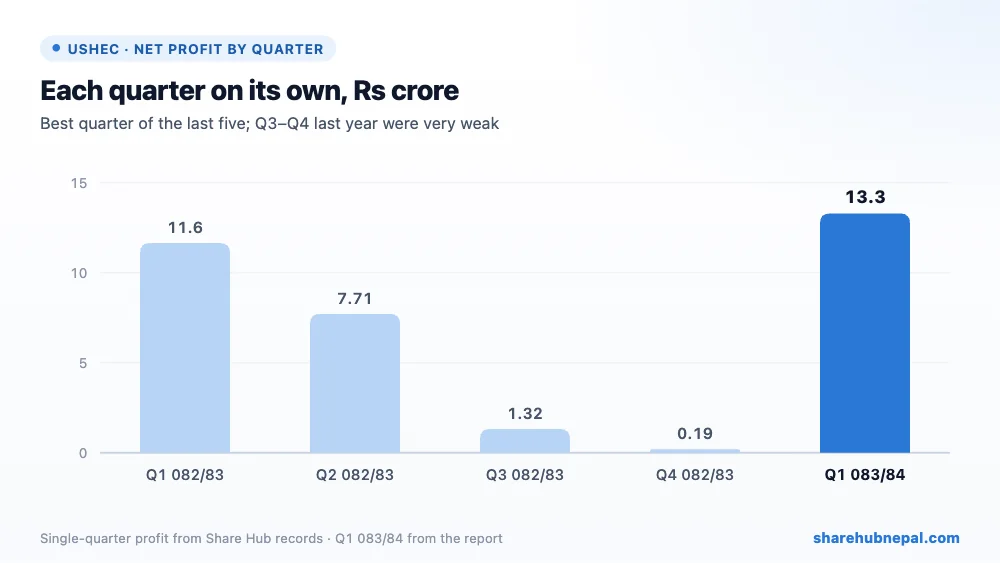
Profit by quarter (Share Hub records): Q1 082/83: Rs 11.65 crore, Q2 082/83: Rs 7.71 crore, Q3 082/83: Rs 1.32 crore, Q4 082/83: Rs 19.21 lakh, Q1 083/84: Rs 13.30 crore. Profit is very seasonal: Q1 (monsoon) earns most of the year's profit, while last year's Q3 and Q4 earned only Rs 1.32 crore and Rs 19.21 lakh. FY 2082/83 EPS was Rs 15.46, so the annualised Rs 39.40 overstates the full year.
3. Debt and balance sheet
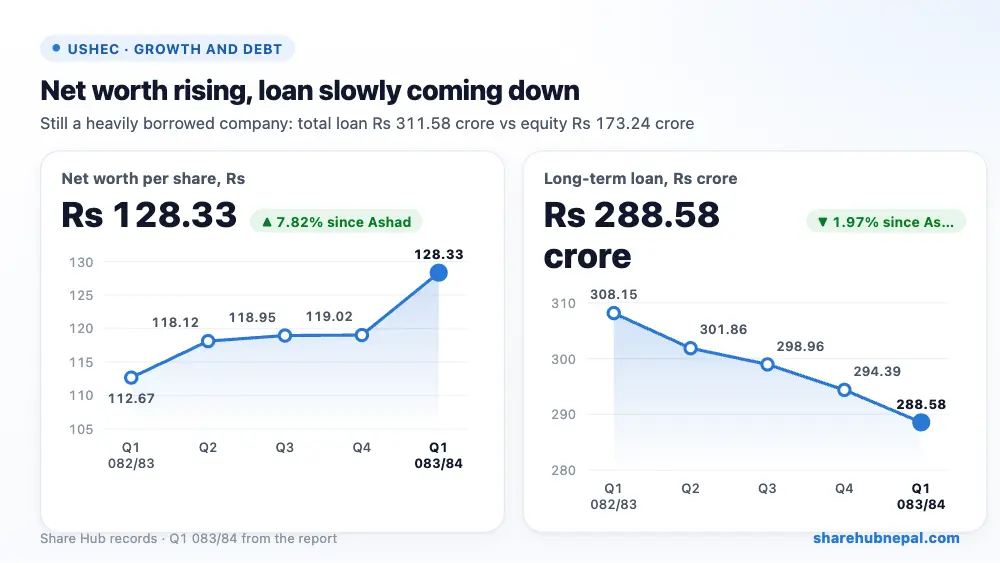
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 4,887,389,194 | Rs 4,810,204,564 | +1.60% |
| Total equity | Rs 1,732,442,518 | Rs 1,606,755,347 | +7.82% |
| Long-term borrowings | Rs 2,885,777,440 | Rs 2,943,857,982 | −1.97% |
| Current borrowings | Rs 229,995,118 | Rs 223,480,783 | +2.91% |
| Cash and equivalents | Rs 331,345,353 | Rs 276,149,748 | +19.99% |
Debt is the main thing to watch. The long-term loan is Rs 288.58 crore (down 1.97% in the quarter) and the short-term loan Rs 23.00 crore, a total of Rs 311.58 crore against equity of Rs 173.24 crore, so debt is about 1.8 times equity. Cash rose to Rs 33.13 crore and receivables to Rs 22.11 crore. Net worth per share rose to Rs 128.33 from Rs 119.02 at Ashad end.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 39.40 |
| Net worth per share | Rs 128.33 |
| Market price (Ashwin end) | Rs 507.5 |
| P/E (annualised) | 12.88x |
| P/B | 3.95x |
At the Ashwin-end price of Rs 507.5, the share trades at 12.88 times annualised EPS and 3.95 times net worth per share. Because Q1 is the peak season, the annualised P/E looks low; on FY 2082/83 EPS of Rs 15.46 the P/E is about 32.8x.
Conclusion
Positives: profit up 14%, finance cost down 20%, no tax, net worth per share up to Rs 128.33, more cash.
Watch: high debt (about 1.8x equity), strong seasonality with weak dry-season quarters, and sales growth of only 2%.
A good monsoon quarter. Profit should keep improving as the loan is repaid, but the full-year result depends on the dry-season quarters, which were very weak last year.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

