













Upper Syange Hydropower Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
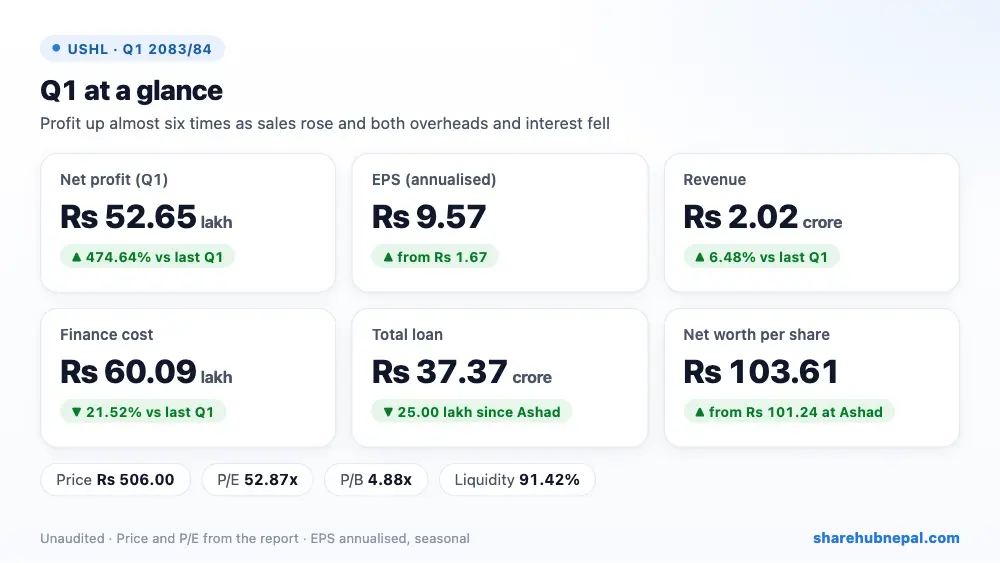
Upper Syange Hydropower, which runs the 2.4 MW Upper Syange project and has invested in the 24.5 MW Dobhan Khola project in Gorkha, earned a net profit of Rs 52.65 lakh in the first quarter, up from only Rs 9.16 lakh a year ago. Annualised EPS is Rs 9.57.
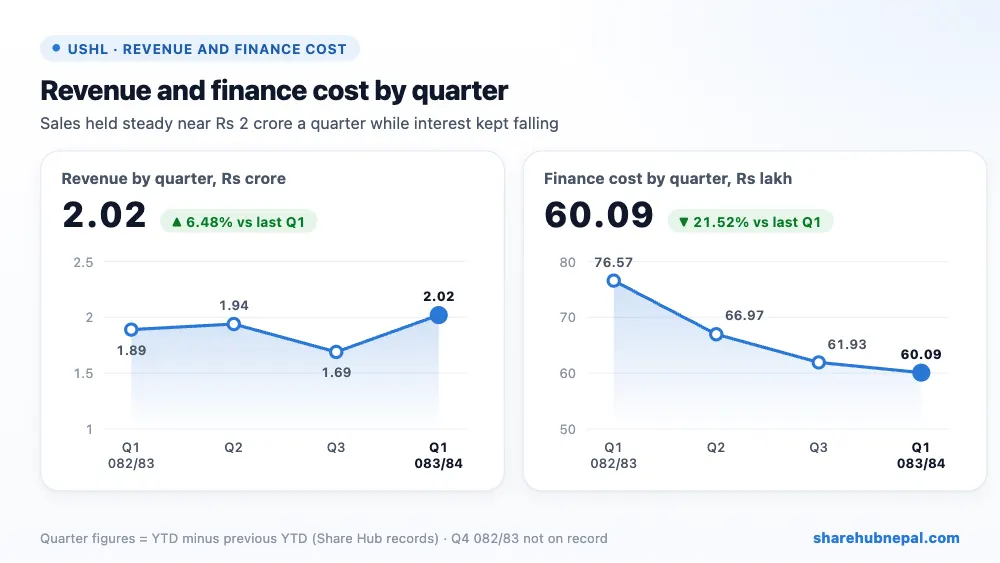
Revenue rose 6.48% to Rs 2.02 crore. The bigger help came from costs: staff and administrative expenses fell 24.08% and finance cost fell 21.52% to Rs 60.09 lakh. Operation profit rose 32.47% to Rs 1.14 crore and the net margin jumped to 26.09% from 4.84%.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from operation | Rs 20,175,915 | Rs 18,948,395 | +6.48% |
| Cost of operation | Rs 463,518 | Rs 771,994 | −39.96% |
| Staff and administrative expenses | Rs 4,006,810 | Rs 5,277,598 | −24.08% |
| Depreciation and amortisation | Rs 4,325,769 | Rs 4,308,103 | +0.41% |
| Operation profit | Rs 11,381,119 | Rs 8,591,657 | +32.47% |
| Finance cost | Rs 6,008,969 | Rs 7,656,780 | −21.52% |
| Net profit | Rs 5,264,707 | Rs 916,179 | +474.64% |
| EPS (annualised) | 9.57 | 1.67 | – |
1. Where the profit came from
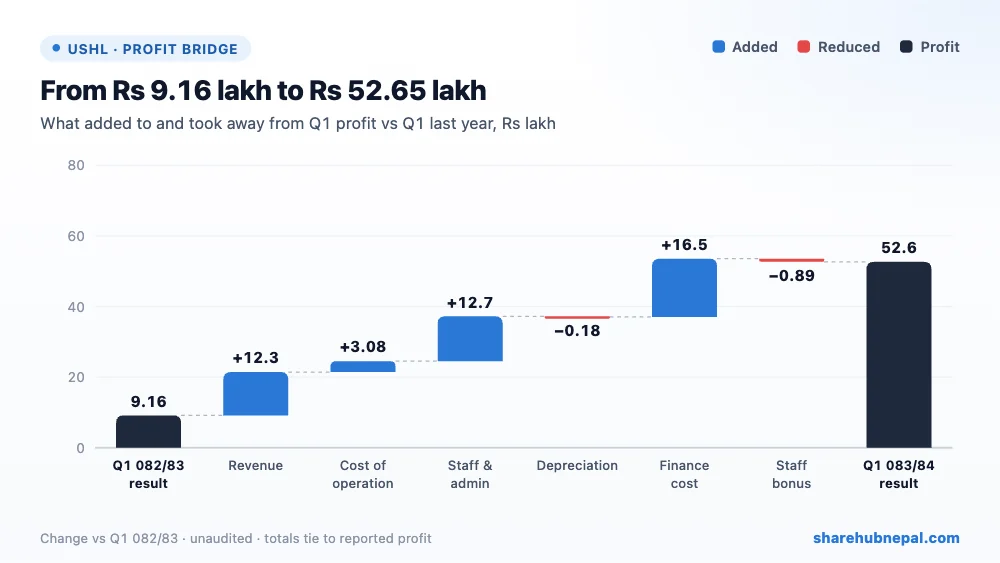
Compared with last year's Q1, lower finance cost added Rs 16.48 lakh, lower staff and administrative cost Rs 12.71 lakh, higher revenue Rs 12.28 lakh and lower cost of operation Rs 3.08 lakh. A bigger staff bonus took away Rs 88,745 and depreciation Rs 17,666.
2. Profit through the year
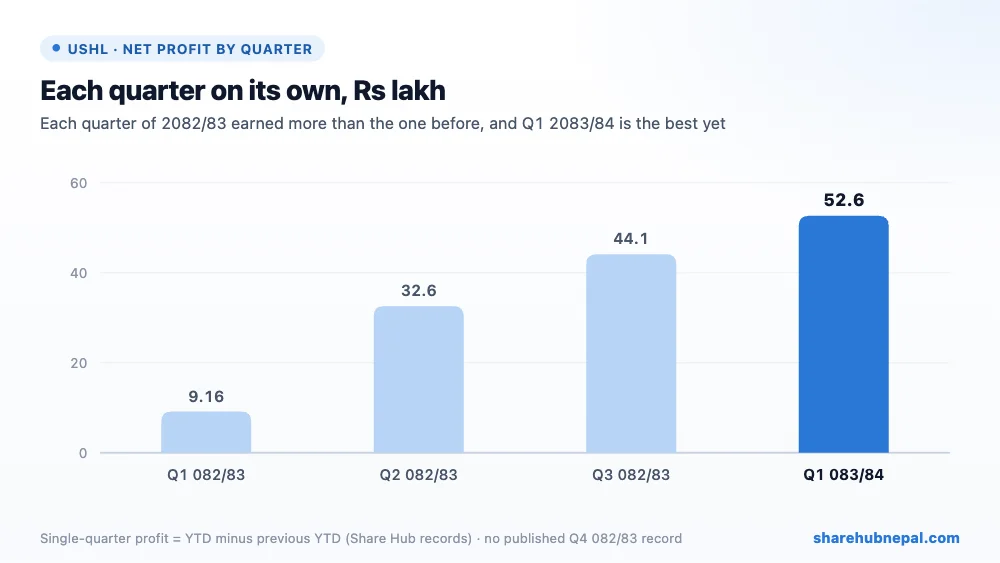
Based on Share Hub's records, single-quarter profit in 2082/83 was Rs 9.16 lakh in Q1, Rs 32.57 lakh in Q2 and Rs 44.12 lakh in Q3. Share Hub has no published Q4 082/83 record for USHL, so Q4 is not shown. Q1 2083/84 is the best quarter in this series.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Long-term loan | Rs 323,700,000 | Rs 327,700,000 | −1.22% |
| Short-term loan | Rs 50,041,720 | Rs 48,541,720 | +3.09% |
| Intangible (project) assets | Rs 433,455,213 | Rs 437,677,845 | −0.96% |
| Investments | Rs 125,348,388 | Rs 125,348,388 | +0.00% |
| Cash and bank | Rs 20,475,413 | Rs 21,771,392 | −5.95% |
| Total assets | Rs 611,089,877 | Rs 609,188,551 | +0.31% |
| Total equity | Rs 227,985,717 | Rs 222,721,010 | +2.36% |
Total loan is Rs 37.37 crore (Rs 32.37 crore long-term and Rs 5.00 crore short-term), 1.64 times equity, a little lower than Rs 37.62 crore at Ashad end. Investments of Rs 12.53 crore (mainly Dobhan Khola) did not change. Current assets of Rs 4.78 crore are slightly below current liabilities of Rs 5.23 crore (liquidity 91.42%). Equity grew by the full profit to Rs 22.80 crore and net worth per share rose to Rs 103.61. The Ashad column is audited.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 9.57 |
| EPS (quarter) | Rs 2.39 |
| Net worth per share | Rs 103.61 |
| Market price (report) | Rs 506.00 |
| P/E (report) | 52.87x |
| P/B | 4.88x |
| Liquidity ratio | 91.42% |
At Rs 506 the share trades at 52.87 times annualised EPS (as reported) and 4.88 times net worth per share. That is a high price for a small 2.4 MW plant; much of it depends on how Dobhan Khola turns out.
Conclusion
Positives: profit up almost six times, falling finance cost, lower overheads, revenue growth, and net worth above face value.
Watch: a very high P/E and P/B, a seasonal Q1 that overstates the annual EPS, liquidity below 100%, transmission limits until the Tarikuna (Khudi) substation is built, and the risk in the Dobhan Khola investment.
Upper Syange had a much better first quarter, helped by cost control and cheaper borrowing. The plant is small, so the share price mostly reflects hopes for Dobhan Khola; watch its construction progress.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

