













Asian Hydropower Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
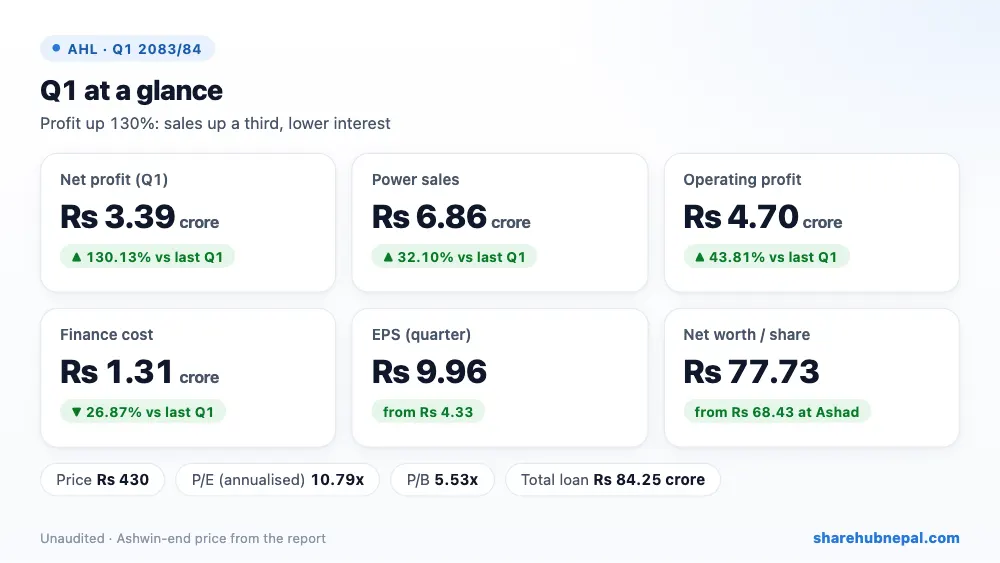
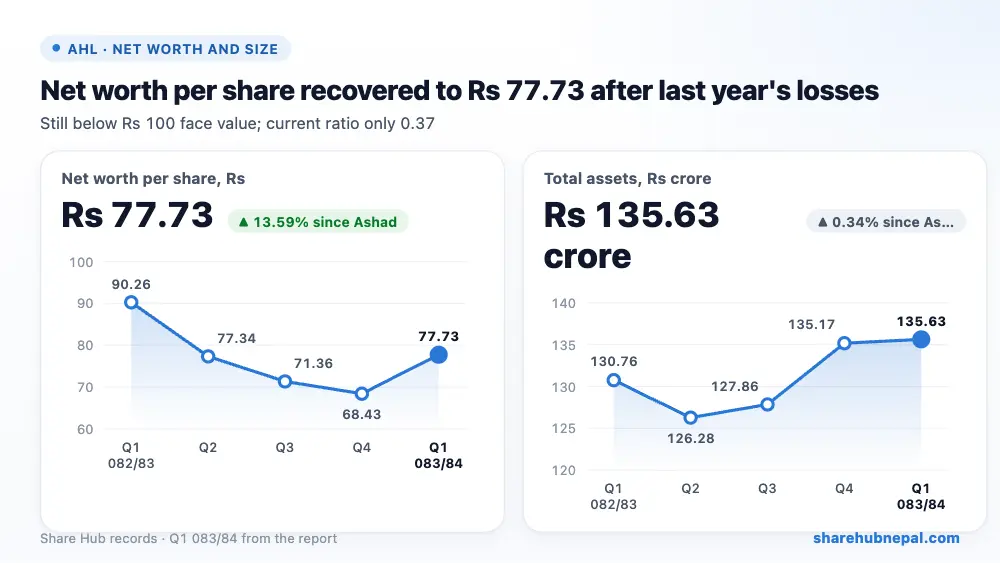
Asian Hydropower earned Rs 3.39 crore in the first quarter of FY 2083/84, up 130.13% from Rs 1.47 crore a year ago. Power sales rose 32.10% to Rs 6.86 crore and finance cost fell 26.87% to Rs 1.31 crore. This follows three loss-making quarters that took FY 2082/83 to a loss of Rs 5.92 crore. Quarter EPS is Rs 9.96 and net worth per share recovered to Rs 77.73 from Rs 68.43 at Ashad end.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sales | Rs 68,645,783 | Rs 51,964,857 | +32.10% |
| Cost of sales | Rs 8,533,379 | Rs 6,633,042 | +28.65% |
| Other income | Rs 0 | Rs 0 | – |
| Operating profit | Rs 47,025,218 | Rs 32,699,632 | +43.81% |
| Finance cost | Rs 13,146,242 | Rs 17,977,752 | −26.87% |
| Income tax | Rs 0 | Rs 0 | – |
| Net profit | Rs 33,878,976 | Rs 14,721,880 | +130.13% |
| EPS (quarter) | 9.96 | 4.33 | – |
| Net worth per share | 77.73 | 90.26 | – |
1. Where the profit came from
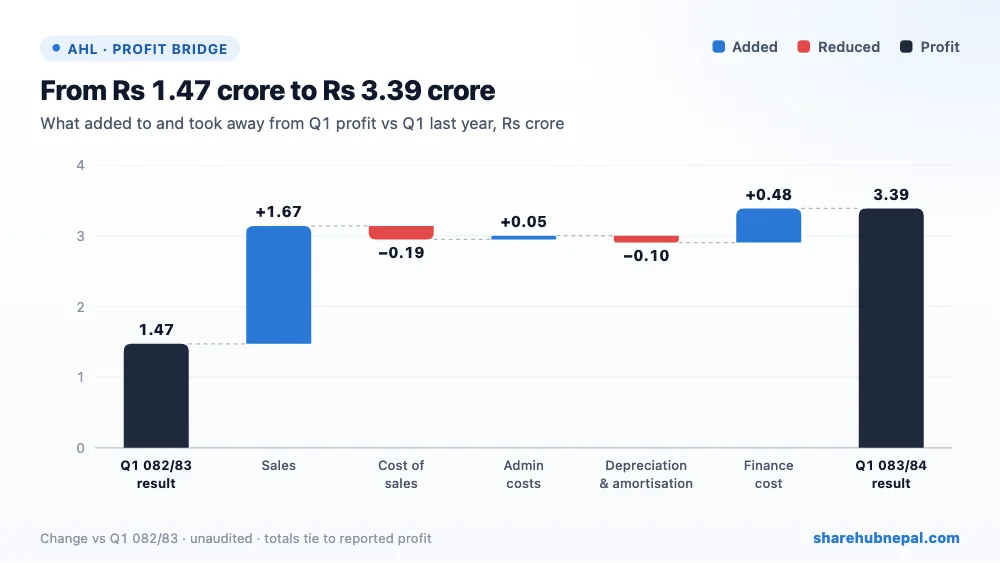
Higher sales added Rs 1.67 crore and lower interest Rs 48.32 lakh. Admin cost fell Rs 5.16 lakh. Cost of sales rose Rs 19.00 lakh and amortisation Rs 9.71 lakh. There is no income tax.
2. Profit through the year
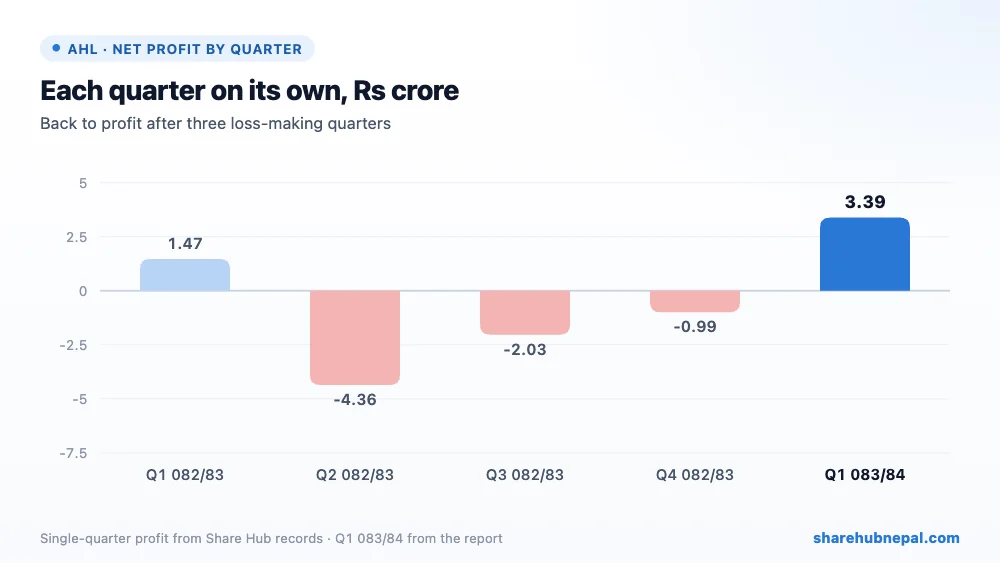
Profit by quarter (Share Hub records): Q1 082/83: Rs 1.47 crore, Q2 082/83: −Rs 4.36 crore, Q3 082/83: −Rs 2.03 crore, Q4 082/83: −Rs 99.43 lakh, Q1 083/84: Rs 3.39 crore. Q2, Q3 and Q4 of last year were all losses, and FY 2082/83 EPS was -17.41. The annualised Q1 figure will not hold through the dry season.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 1,356,331,604 | Rs 1,351,716,056 | +0.34% |
| Total equity | Rs 264,296,106 | Rs 232,673,256 | +13.59% |
| Long-term borrowings | Rs 842,471,039 | Rs 846,549,703 | −0.48% |
| Cash and equivalents | Rs 329,315 | Rs 202,474 | +62.65% |
Total assets are Rs 1.36 arba, nearly all the Rs 1.26 arba concession asset. Long-term loan is Rs 84.25 crore. Equity is Rs 26.43 crore against paid-up capital of Rs 34 crore because of an accumulated loss of Rs 7.57 crore. Cash is only Rs 3.29 lakh, and payables plus other current liabilities of Rs 24.96 crore are far above current assets of Rs 9.24 crore (current ratio 0.37). The company has an NEA letter of intent for two solar projects (Haripur 10 MW and Dhalkebar 30 MW), still in the pre-development phase.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 39.84 |
| Net worth per share | Rs 77.73 |
| Market price (Ashwin end) | Rs 430 |
| P/E (annualised) | 10.79x |
| P/B | 5.53x |
At the Ashwin-end price of Rs 430, the share trades at 10.79 times annualised EPS and 5.53 times net worth per share. On last year's full-year loss there are no real earnings to support the price; the report's own P/E of 43.15 uses quarter EPS.
Conclusion
Positives: back to profit, sales up 32%, interest down 27%, net worth per share up Rs 9.30 in the quarter, two solar projects in the pipeline.
Watch: three loss quarters last year, accumulated loss, net worth still below face value, almost no cash and current ratio 0.37, and a price at 5.5 times book.
A good wet-season quarter that repairs part of last year's losses. Whether the year ends in profit depends on the dry months, which were all losses last year.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

