













Bikash Hydropower Company Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
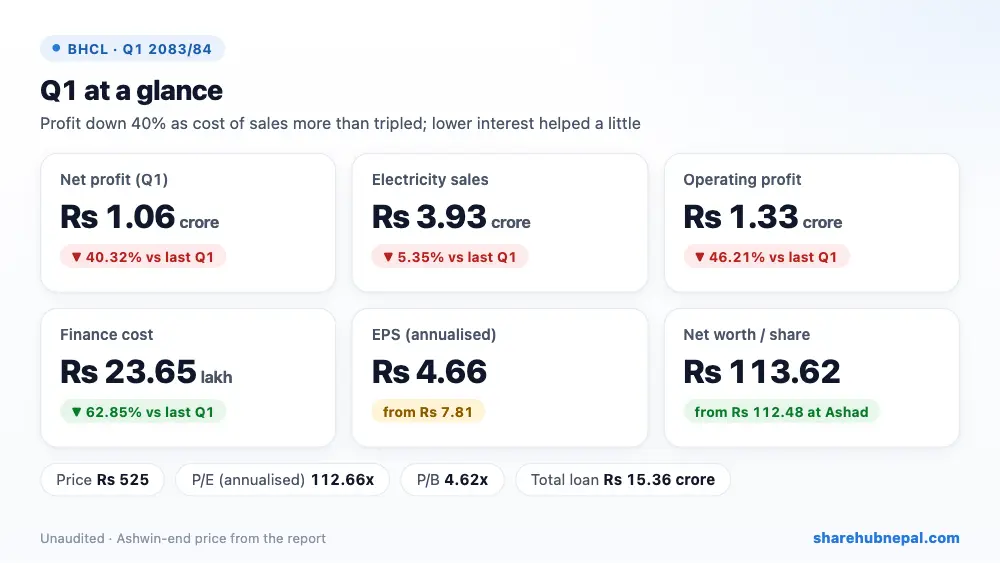
Summary
Bikash Hydropower earned Rs 1.06 crore in the first quarter, down 40.32% from Rs 1.78 crore a year ago. Electricity sales slipped 5.35% to Rs 3.93 crore, but the bigger hit was cost of sales, which jumped from Rs 33.84 lakh to Rs 1.19 crore. The report does not explain the jump. Lower finance cost (down 62.85% as the bank loan was repaid) softened the fall. Annualised EPS is Rs 4.66 against Rs 7.81 a year ago.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sales | Rs 39,347,555 | Rs 41,572,310 | −5.35% |
| Cost of sales | Rs 11,914,050 | Rs 3,383,571 | +252.11% |
| Other income | Rs 220 | Rs 123,212 | −99.82% |
| Operating profit | Rs 13,285,273 | Rs 24,697,260 | −46.21% |
| Finance cost | Rs 2,364,749 | Rs 6,365,695 | −62.85% |
| Income tax | Rs 55 | Rs 30,803 | −99.82% |
| Net profit | Rs 10,595,038 | Rs 17,754,481 | −40.32% |
| EPS (annualised) | 4.66 | 7.81 | – |
| Net worth per share | 113.62 | 103.77 | – |
1. Where the profit came from
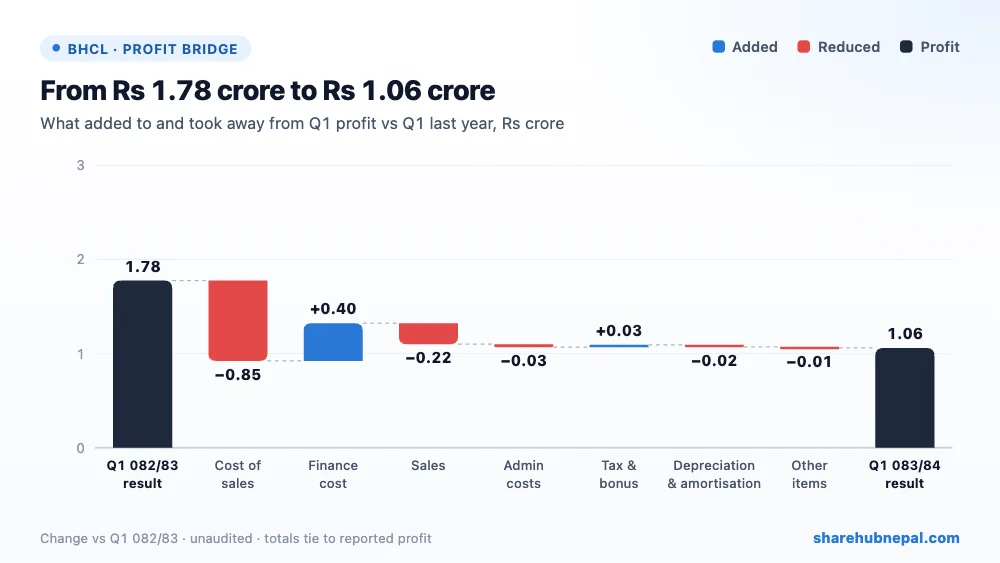
Profit fell by Rs 71.59 lakh. Higher cost of sales took away Rs 85.30 lakh and lower sales Rs 22.25 lakh; admin and depreciation costs added another Rs 5.34 lakh. On the plus side, finance cost fell by Rs 40.01 lakh, and staff bonus and CSR provisions were lower because profit was lower. Investors should ask the company why plant operating cost rose so sharply in a peak-water quarter.
2. Profit through the year
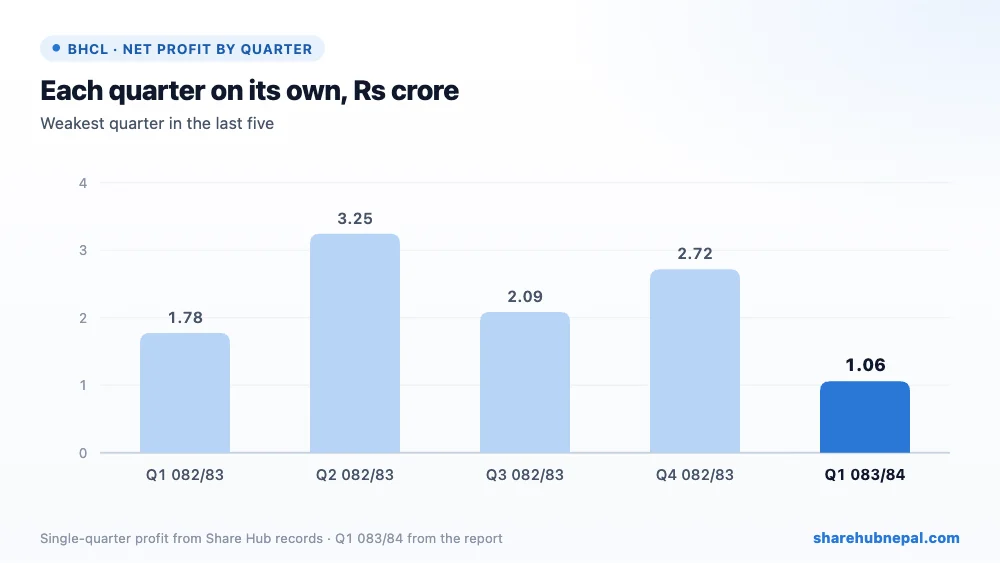
Profit by quarter (Share Hub records): Q1 082/83: Rs 1.78 crore, Q2 082/83: Rs 3.25 crore, Q3 082/83: Rs 2.09 crore, Q4 082/83: Rs 2.72 crore, Q1 083/84: Rs 1.06 crore. This Q1 is the weakest of the last five quarters; last year's Q2 was the best at Rs 3.25 crore.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 1,192,027,108 | Rs 1,192,278,498 | −0.02% |
| Total equity | Rs 1,032,876,918 | Rs 1,022,529,098 | +1.01% |
| Long-term borrowings | Rs 128,640,400 | Rs 140,640,400 | −8.53% |
| Current borrowings | Rs 25,000,000 | Rs 24,000,000 | +4.17% |
| Cash and equivalents | Rs 50,453,679 | Rs 24,888,270 | +102.72% |
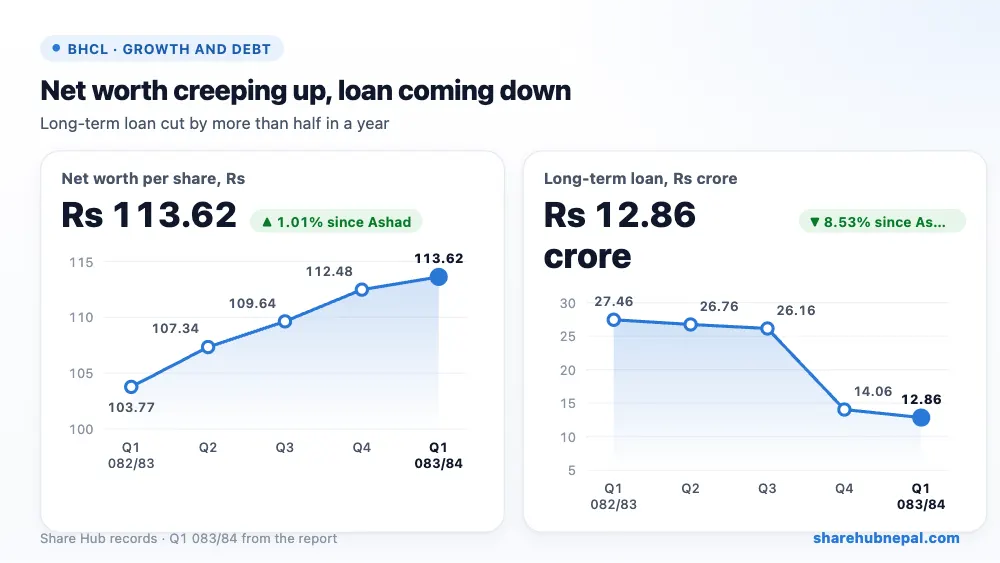
The balance sheet keeps getting safer. The long-term loan fell to Rs 12.86 crore from Rs 14.06 crore at Ashad end and Rs 27.46 crore a year ago; with the Rs 2.50 crore short-term loan, total debt is Rs 15.36 crore against equity of Rs 103.29 crore. Cash doubled to Rs 5.05 crore. The company holds a Rs 10 crore long-term investment, linked to its plan to build the upper Majhkhola project.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 4.66 |
| Net worth per share | Rs 113.62 |
| Market price (Ashwin end) | Rs 525 |
| P/E (annualised) | 112.66x |
| P/B | 4.62x |
At the Ashwin-end price of Rs 525, the share trades at 112.66 times annualised EPS and 4.62 times net worth per share. That is very expensive. Even on the audited FY 2082/83 EPS of Rs 10.75 the P/E is about 48.8x.
Conclusion
Positives: debt falling fast, finance cost down 63%, cash doubled, net worth per share up to Rs 113.62.
Watch: profit down 40% with an unexplained tripling of cost of sales, lower sales in the peak season, and a very high P/E.
BHCL is financially safe and nearly through its debt, but this quarter's earnings are weak and the stock price assumes much better profits than the plant is delivering.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

