













Barahi Hydropower Public Ltd. – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
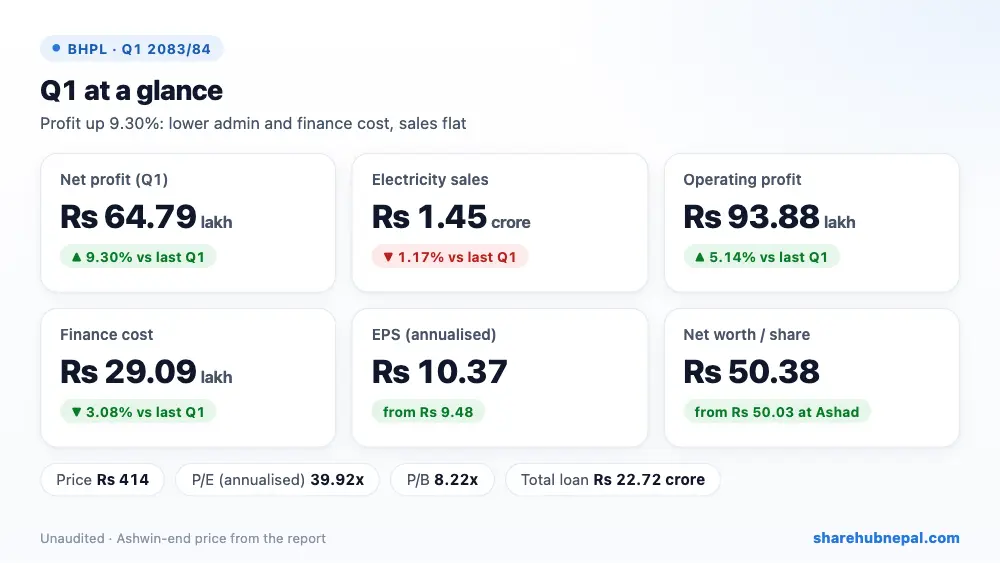
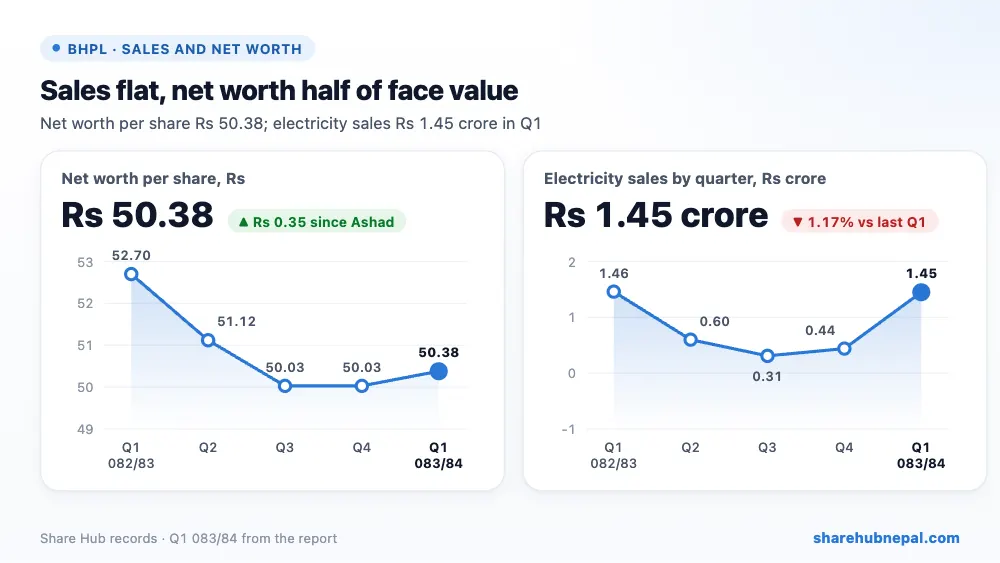
Barahi Hydropower earned a net profit of Rs 64.79 lakh in the first quarter of FY 2083/84, up 9.30% from Rs 59.28 lakh in the same quarter last year. Electricity sales slipped 1.17% to Rs 1.45 crore even though generation was 0.58% higher (27,71,170 units); NEA transmission-line tripping and heavy rain cost about 3,77,624 units. Admin cost fell 46.87% and finance cost 3.08%, which lifted profit. Quarter EPS is Rs 2.59 (Rs 10.37 annualised) and net worth per share is Rs 50.38.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sales | Rs 14,466,664 | Rs 14,637,927 | −1.17% |
| Cost of sales | Rs 1,237,809 | Rs 1,290,559 | −4.09% |
| Other income | Rs 3,954 | Rs 0 | – |
| Operating profit | Rs 9,387,792 | Rs 8,928,795 | +5.14% |
| Finance cost | Rs 2,908,608 | Rs 3,000,964 | −3.08% |
| Income tax | Rs 0 | Rs 0 | – |
| Net profit | Rs 6,479,184 | Rs 5,927,831 | +9.30% |
| EPS (annualised) | 10.37 | 9.48 | – |
| Net worth per share | 50.38 | 52.7 | – |
1. Where the profit came from
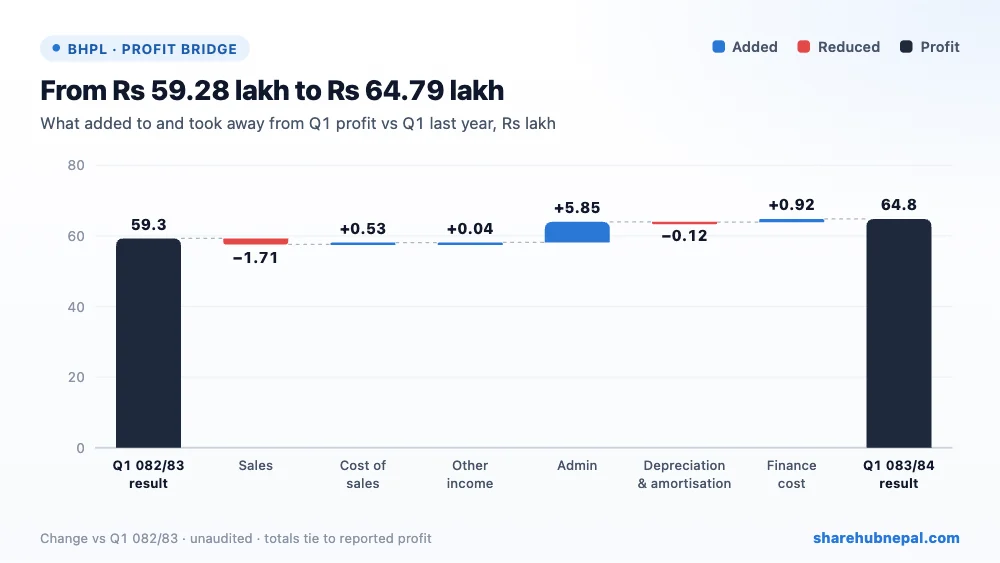
Lower sales took Rs 1.71 lakh from profit. Lower admin cost added Rs 5.85 lakh, lower operating cost Rs 0.53 lakh, lower finance cost Rs 0.92 lakh and other income Rs 0.04 lakh, while depreciation and amortisation took Rs 0.12 lakh. There was no tax or bonus in either quarter, so profit rose by Rs 5.51 lakh in all.
2. Profit through the year
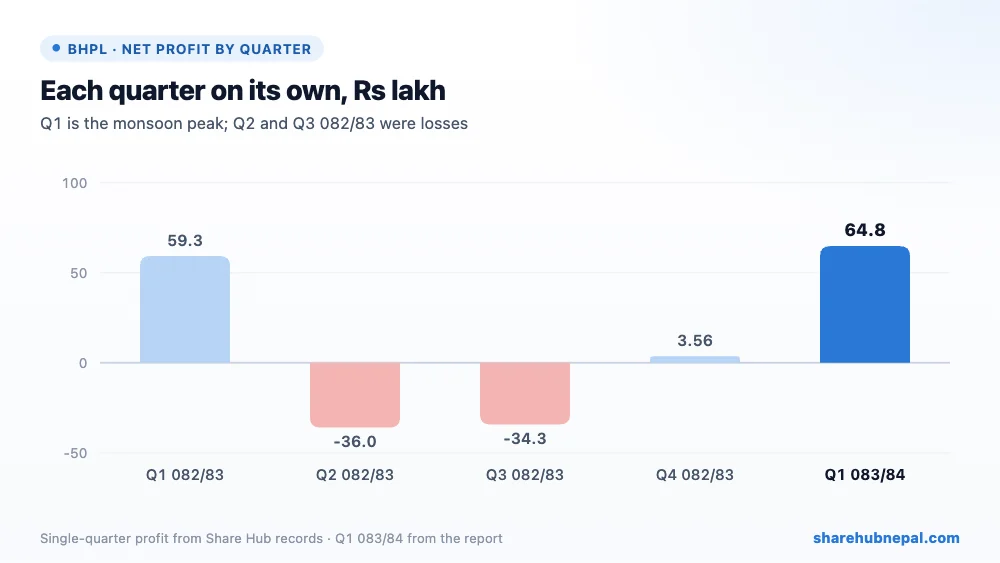
Profit by quarter (Share Hub records): Q1 082/83: Rs 59.28 lakh, Q2 082/83: −Rs 35.98 lakh, Q3 082/83: −Rs 34.28 lakh, Q4 082/83: Rs 3.56 lakh, Q1 083/84: Rs 64.79 lakh. Quarter figures are worked out from Share Hub year-to-date records. Profit is very seasonal: last year Q1 earned Rs 59.28 lakh, then Q2 and Q3 lost Rs 35.98 lakh and Rs 34.28 lakh, and Q4 earned only Rs 3.56 lakh, so FY 2082/83 ended with a loss of Rs 7.42 lakh. This Q1 is the best quarter of the five shown.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 358,970,994 | Rs 357,326,728 | +0.46% |
| Total equity | Rs 125,942,975 | Rs 125,082,441 | +0.69% |
| Long-term borrowings | Rs 180,393,202 | Rs 170,128,822 | +6.03% |
| Current borrowings | Rs 46,812,695 | Rs 0 | – |
| Cash and equivalents | Rs 1,789,604 | Rs 6,678,917 | −73.21% |
Total assets are Rs 35.90 crore (Rs 143.60 per share), mostly the Theule Khola project asset of Rs 28.08 crore. Equity is Rs 12.59 crore (Rs 50.38 per share), only half the Rs 100 face value because of accumulated losses of Rs 12.41 crore. Equity rose only Rs 8.61 lakh since Ashad (Share Hub record 7070) against a Q1 profit of Rs 64.79 lakh, a gap the report does not explain. Bank loans total Rs 22.72 crore (long-term Rs 18.04 crore and short-term Rs 4.68 crore), about 1.8 times equity. Cash is only Rs 17.90 lakh, down from Rs 66.79 lakh at Ashad end; current assets of Rs 7.64 crore cover current liabilities of Rs 5.26 crore 1.45 times.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 10.37 |
| Net worth per share | Rs 50.38 |
| Market price (Ashwin end) | Rs 414 |
| P/E (annualised) | 39.92x |
| P/B | 8.22x |
At the Ashwin-end price of Rs 414, the share trades at 39.92 times annualised EPS and 8.22 times net worth per share. The report's P/E of 156.66 uses the quarter EPS. Q1 is the strongest season and FY 2082/83 ended in a loss, so the annualised EPS of Rs 10.37 (P/E about 39.9 at Rs 414) overstates the likely full-year earnings; the price is 8.22 times net worth per share.
Conclusion
Positives: profit up 9.30%, generation up 0.58%, admin cost almost halved, finance cost lower, long-term loan down Rs 4.68 crore from a year ago, interest cover about 3.2 times in Q1.
Watch: a small single-plant company with accumulated losses of Rs 12.41 crore, net worth per share only Rs 50.38, dry-season quarters usually lose money, short-term loans up to Rs 4.68 crore, cash only Rs 17.90 lakh, equity rose much less than the Q1 profit; the report itself names NEA transmission-line tripping/outages and heavy rain as the main problems.
A decent monsoon quarter mainly because of lower costs, not higher sales. Last year the dry-season quarters wiped out the Q1 profit, so the full year depends on Q2 and Q3; watch transmission outages, the short-term loan and the low cash balance.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

